 Harper Brooks
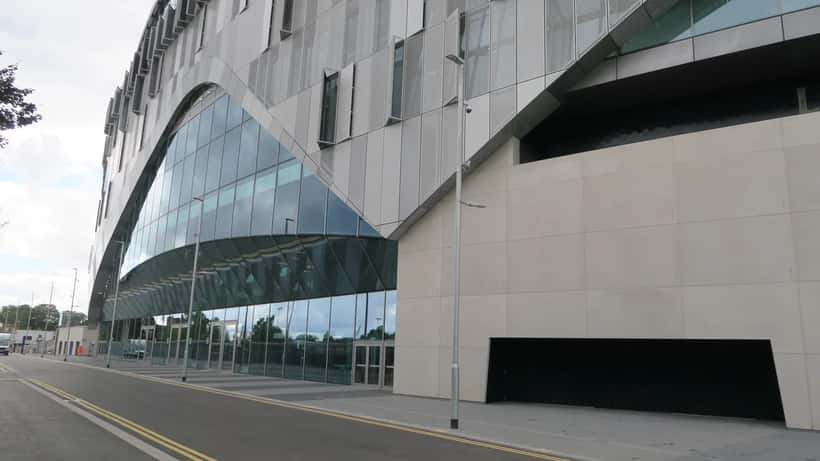
Today's Premier League clash between Tottenham Hotspur and Newcastle United at the Tottenham Hotspur Stadium is more than a Matchday 3 battle for position in the 2026-27 season. On the same day as kickoff, two radically different capital structures are competing for US investor attention: Saudi Arabia's Public Investment Fund has placed more than £300 million of Newcastle shares on the open market, while Tottenham is carrying £847.7 million in US private placement bonds issued at 3.30%—a rate that would cost 7.2-7.5% to replicate today. For American investors who track European football as an emerging alternative asset class, the timing of this fixture is no coincidence.
Britain's Richest Pitch: By the Numbers
The gap between these two clubs becomes visible the moment you examine the balance sheets rather than the league table.
| Metric | Tottenham Hotspur | Newcastle United |
|---|---|---|
| 2026 Valuation | £3–4.5 billion | £2+ billion |
| Primary Ownership | ENIC Group (private) | Saudi PIF (85%) |
| Long-Term Debt | £847.7M (US private placement bonds) | None (new stadium planned) |
| Original Bond Yield | 3.30% fixed (2019) | N/A |
| Implied 2026 Refinancing Yield | 7.2–7.5% | N/A |
| Minority Stake for Sale | N/A | £300M+ (approx. 21.25%) |
| Global Ranking | #9 (CNBC 2026) | Outside top 15 |
According to CNBC's 2026 Global Soccer Team Valuations report, Tottenham recorded total revenue of $726 million and EBITDA of $138 million, with debt representing 33% of overall club value. Newcastle, internally valued by Saudi PIF at more than £2 billion, has grown from its £305 million 2021 purchase price to become one of the fund's most closely watched sports investments globally—a return of more than 6.5x in under five years.
The contrast in how each club is managing its capital position in summer 2026 could not be starker. Tottenham is managing legacy debt from a completed stadium project. Newcastle is raising new equity to build one.
Why Both Clubs Are Restructuring Their Balance Sheets Simultaneously
Tottenham's financing story begins in 2019, when the club raised £847.7 million in long-term bonds via US private placement—directly from American institutional investors including insurance companies and pension funds. The weighted average coupon locked in was 3.30%, with maturities running out to 2051. At the time, that was the market rate. Today, given that twenty-year gilt rates sit at approximately 5.0-5.2% and credit spreads for stadium-backed football debt have not compressed, equivalent bonds would price at roughly 7.2-7.5%. Reports from industry sources indicate Tottenham is planning to refinance approximately £400 million of that existing debt in 2026. For US bondholders receiving 3.30% on the existing tranches, a refinancing event triggers both a reinvestment decision and a materially higher income opportunity on any rollover allocation.
Newcastle's capital story runs in parallel. Saudi PIF raised its shareholding to 85% after the 2021 acquisition alongside Amanda Staveley's PCP Capital Partners and the Reuben Brothers. The fund now values Newcastle at more than £2 billion—and according to reporting by SportsPro and Yahoo Sports from May 2026, PIF is actively seeking to sell approximately 21.25% of the club to external investors. That stake would generate approximately £318 million at the current implied valuation, with proceeds earmarked for a planned £1 billion stadium redevelopment that would replace or significantly expand St. James' Park.
Unlike Tottenham's completed and revenue-generating venue—which underpins the bond payments with matchday receipts, NFL fixtures, and hospitality income—Newcastle's new stadium remains a proposal. US investors evaluating Newcastle equity are buying exposure to a construction plan, a sovereign wealth fund's balance sheet, and a football team's future performance rather than a secured infrastructure asset.
A comparable analysis of how Chelsea's commercial expansion strategy has reshaped US franchise valuations is available in this Expert Zoom report on Premier League sports investment.
The $2 Million Decision: Equity vs. Credit
Consider the situation facing Sarah, a 48-year-old portfolio manager at a Chicago-based family office overseeing $40 million in total assets. In August 2026, her investment committee has approved a 5% allocation to alternative assets in the sports and entertainment sector—$2 million to deploy within the next twelve months.
Her wealth advisor has placed two realistic pathways on the table:
Pathway A: Newcastle equity exposure via a US-registered sports alternatives fund.
Several alternative investment vehicles now offer indirect access to Premier League club equity through fund structures meeting US accredited-investor requirements. At Newcastle's £2 billion valuation, PIF's 21.25% minority stake sale represents approximately £318 million ($400 million at current exchange rates). A fund purchasing a portion of that stake and accepting $250,000 minimum subscriptions could accommodate Sarah's $2 million allocation.
The if/then logic is direct: if Newcastle qualifies for the UEFA Champions League in 2026-27—a realistic scenario given the club's squad investment trajectory—broadcasting and commercial revenues would increase by approximately £40-50 million annually, pushing the implied club valuation toward £2.8-3.2 billion. Sarah's $2 million of notional exposure rises to approximately $2.8-3.2 million on a three-to-five-year horizon—a 40-60% gain.
If, however, Newcastle triggers a breach of the Premier League's Profit and Sustainability Rules (PSR) and faces a points deduction or UEFA investigation—risks that analysts flagged for several clubs in 2025-26—the valuation discount can be severe. Comparable PSR events have triggered corrections of 20-35% in affected clubs. Sarah's $2 million could fall to $1.3-1.6 million before any recovery window opens.
Pathway B: Spurs credit exposure through the refinancing window.
Tottenham's planned refinancing of approximately £400 million of stadium debt is expected to price new bonds at around 7.2-7.5% in the current interest-rate environment. For a family office with capital-preservation mandates, this pathway offers predictable income backed by a completed, revenue-generating stadium asset.
At a 7.3% blended yield on a $2 million position, Sarah's annualized income would be approximately $146,000. Over five years, with principal intact, that is $730,000 in cumulative income—without any equity upside, but also without the PSR concentration risk, sovereign governance questions, or construction timeline uncertainty embedded in the Newcastle stake.
The decision is not purely financial. Sarah's investment committee has an ESG policy that flags investments connected to sovereign wealth funds with governance concerns. Saudi PIF's majority ownership of Newcastle has drawn sustained scrutiny from US institutional investors, and some university endowments and public pension systems have adopted formal policies restricting indirect exposure to Saudi government-linked entities—an increasingly important factor as ESG screening tightens across institutional mandates.
For further context on how Premier League promotion and relegation economics affect US investor returns in English football, see this Expert Zoom breakdown of the Coventry-Hull Premier League windfall.
What US Investors Need to Know Before Acting
Premier League club investments sit at the intersection of several regulatory regimes that most US wealth advisors do not navigate routinely. Three issues require specialist advice before any capital moves:
PFIC treatment under US tax law. Most UK football clubs structured as private limited companies qualify as Passive Foreign Investment Companies (PFICs) under IRS rules. Without the correct annual elections—Mark-to-Market or Qualified Electing Fund—capital gains are taxed at the highest ordinary income rate plus an interest charge calculated from the year the gain accrued. On a $600,000 gain over five years, the difference between proper PFIC elections and default treatment can exceed $80,000 in additional US federal tax liability.
Premier League Profit and Sustainability Rules. Unlike US sports leagues, where franchise values are largely insulated from on-field financial penalties, Premier League clubs face binding spending constraints. A PSR breach can trigger immediate points deductions, transfer embargoes, and UEFA licensing risk—each of which affects equity valuations sharply and without the structured legal processes US investors expect from registered securities markets.
Illiquidity premium and exit horizon. There is no secondary market for Premier League club equity. Investment horizons of seven to ten years before any realistic exit opportunity are standard. Bond positions at Tottenham carry defined maturities, but early exits require finding a counterparty willing to take the position at market price—a process that can take months.
The SEC's investor education resources at sec.gov/investor provide foundational guidance on alternative and illiquid investments, including the key due diligence questions investors should ask before committing capital to any non-registered vehicle. What they cannot substitute is a wealth management advisor with direct experience in cross-border sports asset transactions.
Connecting the Match to a Consultation
At the Tottenham Hotspur Stadium today, both clubs are competing for Champions League ambitions, transfer credibility, and managerial momentum. For US investors watching from a trading desk or a sports bar in Chicago, the same fixture is a real-time signal: European football has evolved into a genuine asset class, one that rewards those who arrive with the right advisors.
A wealth management advisor on ExpertZoom can help you evaluate whether Premier League exposure—via equity, credit, or sports-adjacent fund structures—belongs in your 2026-27 alternative asset allocation. The conversation should happen before the capital call, not after.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Premier League club investments involve significant risk, including the possible total loss of capital. Consult a registered investment advisor and a qualified tax professional before making any investment decision.
