 Michael Campbell
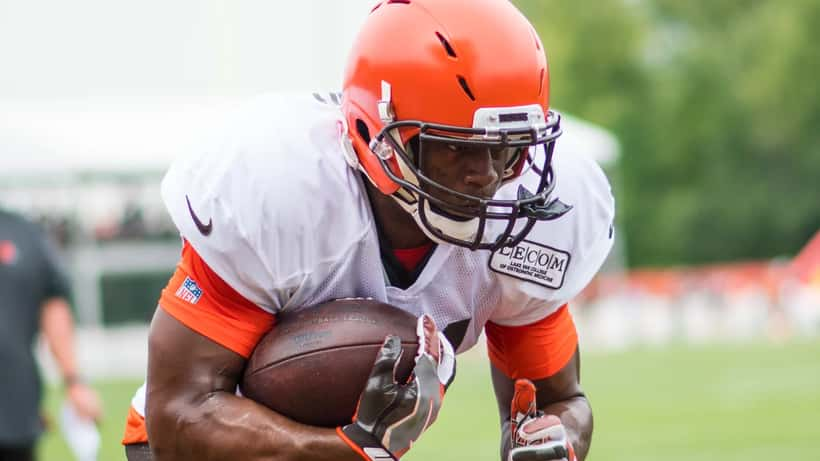
The announcement came on a quiet Friday in August 2026: Nick Chubb, once considered the best pure runner in the NFL, was done. At 30 years old, just three years after tearing his ACL, MCL, and meniscus in a single devastating Week 2 collision, Chubb posted on Instagram that he was "finally ready to share that I'm done playing football." The retirement was not a surprise. But the speed with which a career worth an estimated $47 million in earnings was curtailed by a single play should give every working professional, at every income level, serious pause.
What Actually Happened to Nick Chubb's Earning Trajectory
Chubb's financial story is deceptively instructive. At the time of his injury in September 2023, he had just entered the final year of a 2022 three-year contract extension worth $36.6 million with the Cleveland Browns — an elite deal for an elite running back. His 2023 base salary alone was $10.8 million, according to Spotrac. The injury ended his season after two games.
He returned in 2024, playing in eight regular-season games and rushing for 626 yards before the Browns cut him ahead of 2025. He signed with the Houston Texans on a restructured, incentive-heavy deal — the kind reserved for players proving they still have something left. He played 15 games. Then, in August 2026, he retired.
The underlying arithmetic is sobering. From the moment of his 2023 injury through the end of his career, Chubb's earning power dropped by an estimated 65 percent compared to what a fully healthy version of himself would have commanded. According to Over the Cap, the average annual value for a top-tier NFL running back in 2024–2025 ranged from $9 million to $14 million per year. Chubb's post-injury contracts came nowhere close to that range.
What a Wealth Advisor Sees in This Story
A wealth management expert asked to assess Nick Chubb's trajectory might note, first, what the public sees: a catastrophic injury. But financial planners see something different — a predictable risk category that was not sufficiently hedged against.
"This is exactly the scenario that disability income insurance exists for," says the framework behind modern career income protection. NFL players do have access to some disability coverage through the collective bargaining agreement negotiated by the National Football League Players Association. But that coverage is claim-dependent, structurally complex, and far less generous than the salary a player was earning at peak market value.
For professionals outside the sport — surgeons, pilots, engineers, attorneys, business owners — the parallel is direct and urgent. A senior software architect earning $220,000 a year has no guaranteed contract, no union backstop, and only what they have personally arranged.
Three planning tools address career-ending injury risk directly:
Own-occupation disability insurance. This type of policy pays benefits when you cannot perform your specific occupation — not merely "any work." A concert violinist with a nerve injury in her bow hand may technically be able to work retail, but an own-occupation policy pays regardless. The Social Security Administration reports that one in four 20-year-olds will experience a disabling condition before reaching retirement age. The SSA's disability program is a last-resort safety net — not income replacement.
Salary continuation and income riders. High earners should ensure policies include cost-of-living adjustments and a benefit tied to their peak earning period, not a static payout frozen at policy inception years earlier.
Diversified income streams before the injury happens. One structural lesson from Chubb's story: his income was 100% dependent on his physical ability to run a football. A wealth advisor reviewing his profile would have encouraged building a portfolio generating passive income — index funds, real estate investment trusts, or a private equity stake — so that an injury to the income-generating asset (his legs) did not collapse the entire financial structure.
The Concrete Scenario: A $180,000-a-Year Contractor in Atlanta
Take the hypothetical case of Marcus, a 34-year-old self-employed electrician in Atlanta who grosses $180,000 annually. In January 2026, he falls from scaffolding and fractures three vertebrae, resulting in permanent nerve damage that prevents him from climbing, lifting, or working at heights. His recovery takes 14 months. He is eventually cleared to take sedentary work, but he cannot return to the trade.
Without own-occupation disability insurance: Marcus qualifies for Social Security Disability Insurance (SSDI). But the average monthly SSDI payment as of 2026 stands at approximately $1,580 — roughly $18,960 per year. That is an 89.5% reduction from his prior income. His mortgage payment alone is $2,200 per month.
With an own-occupation policy covering 60% of pre-disability income: Marcus receives $9,000 per month, or $108,000 per year, tax-free if premiums were paid personally. The annual gap between these two outcomes: $89,040 — every year, for potentially 15 or more years until retirement.
The if/then logic is straightforward: if Marcus is self-employed without own-occupation coverage and suffers a career-ending injury before age 50, then he faces income at less than 11% of his former rate for the remainder of his working life. A one-hour consultation with a certified financial planner would have identified that gap. A monthly premium of $350 to $500 — roughly 0.2% of his annual income — could have locked in protection before the scaffolding gave way.
See also: Joe Mixon Cut and Unsigned: What Every NFL Player Should Know About Financial Planning
The Nick Chubb Parallel for Every Professional
Nick Chubb is not just a cautionary tale about the NFL. He is a case study in what happens when a single physical asset — whether it is a running back's burst, a surgeon's steady hands, or a carpenter's knees — takes a hit before a financial safety net is fully in place.
Timing matters enormously in these scenarios. Chubb was injured at 27, at the height of his market value and at the steepest point of his projected earning curve. Had he been 33 and planning to retire in two years, the financial impact would have been minimal. Instead, the injury struck when the forward value of future contracts was at its highest.
The same math applies to professionals in their 30s: statistically the decade of peak income growth, yet also the period when disability insurance premiums are cheapest to purchase. A 35-year-old physician buying a 30-year own-occupation policy in 2026 will pay substantially less per month than a 45-year-old with the same income and health profile. Waiting costs money — before anything goes wrong.
Four Steps You Can Take Before the End of the Month
The action items from Chubb's story are concrete:
Check whether you have own-occupation coverage. Group plans from employers almost never qualify — they typically pay only if you cannot perform any work at all, not your specific work. Read the policy language carefully.
Calculate your income replacement gap. If SSDI pays approximately $18,960 per year and you earn $140,000 per year, your gap is roughly $121,040 annually. Your disability policy should be sized to bridge that specific number.
Review the elimination period. Most disability policies have a 60- to 180-day waiting period before benefits begin. You need liquid emergency savings equal to that window multiplied by your monthly expenses.
Schedule a session with a fee-only financial advisor. This is a planning exercise, not a product pitch. A wealth management expert can audit your current coverage, identify the exact gaps, and model the scenarios that Nick Chubb's retirement makes suddenly vivid.
Chubb said he "wanted to end his career on a healthy note, along with a winning season." The financial note his career ended on was written in 2023, at the moment of impact. Your plan should be written before that moment arrives.
This article discusses general financial planning principles. For personalized advice tailored to your income and risk profile, consult a certified financial planner or licensed wealth management advisor.
