 Julia Vachon
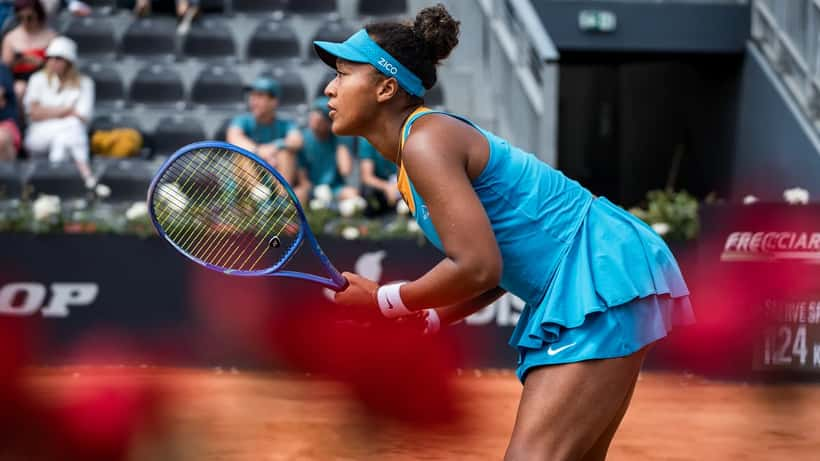
Naomi Osaka walked onto Wimbledon's Centre Court on July 5, 2026, for her fourth-round showdown against world No. 1 Aryna Sabalenka — and for Canadians watching, the match carried a financial subplot just as compelling as the tennis itself. Osaka, the 14th seed, has reached the round of 16 for the first time in her career. Yet her financial success tells a story that has almost nothing to do with prize money.
A Career Where the Brand Outearns the Racket
Between 2019 and 2025, Naomi Osaka earned an estimated $230 million — roughly $25 million from WTA prize money, and the remaining $205 million from endorsement deals with brands including Nike, Louis Vuitton, TAG Heuer, Mastercard, and Maybelline. In 2025 alone, she collected approximately $2.5 million on the WTA tour while her sponsorship portfolio generated a further $22 million, according to Forbes.
That is nearly a nine-to-one ratio in favour of endorsements. Her Nike deal alone is estimated at $10 million per year. Crucially, she held that financial position even through 2021 and 2022, when she stepped away from competition entirely to protect her mental health — and her WTA ranking dropped and prize money evaporated completely.
This is not just a curiosity about one elite athlete. It is a real-world illustration of something wealth management professionals discuss with high-earning Canadian clients every single day: what happens when your income is irregular, multi-sourced, and tied to your personal brand rather than a fixed salary?
The Tax and Investment Challenge of Variable Income
For most Canadians, income arrives in predictable bi-weekly paycheques with taxes deducted at source. But athletes, freelancers, commissioned professionals, and entrepreneurs face a fundamentally different reality — one where annual earnings can spike dramatically in a strong year and contract sharply in the next.
Osaka's career illustrates this perfectly. Prize money is performance-dependent and unpredictable. Endorsement income follows contract cycles and can be disrupted by injury or absence. Managing this kind of volatility demands a deliberate financial strategy that salaried workers rarely need to build.
In Canada, the Canada Revenue Agency's registered savings framework is particularly well suited to variable-income earners. Registered Retirement Savings Plans (RRSPs) allow contribution room to accumulate in low-income years and be deployed strategically in high-income years, reducing the tax burden over time. The CRA's RRSP guide outlines the contribution rules in detail — but applying them optimally to an irregular income stream is where a qualified wealth management adviser becomes genuinely valuable.
The Diversification Model Osaka Built
The deeper lesson from Osaka's career is about the layered structure of her income. At her peak, she was earning simultaneously from:
- Tournament prize money across four Grand Slam circuits globally
- Long-term corporate endorsements with multi-year, guaranteed minimums
- Her own fashion and entrepreneurship ventures, including her tennis apparel collaborations
This layered approach insulated her financially even during extended absences from competition. Her brand income continued uninterrupted through periods when her WTA ranking fell and on-court earnings dropped to zero.
For Canadians who are self-employed, commission-based, or building a personal brand — content creators, consultants, tradespeople, or small business owners — this structure holds directly relevant lessons. Multiple income streams mean no single disruption can unravel a financial plan. You can also read about how other athletes like Alexandra Eala managed prize money milestones into long-term wealth strategy, and how endorsement-first careers like Olivia Dunne's NIL deals reshaped athlete financial planning — patterns that increasingly apply to non-athlete high earners too.
The critical principle: put structures in place before the income surge arrives, not after. A certified wealth management adviser can identify the right account types — RRSP, TFSA, or corporate accounts for incorporated professionals — understand quarterly tax instalment obligations, and build a cash-flow plan that treats variable income as a feature to leverage rather than a problem to endure.
Wimbledon 2026 and What Comes Next
On grass, Osaka has looked increasingly formidable this season. Her run to the Bad Homburg final was the best of her grass-court career, and her arrival at Wimbledon's second week without dropping a set suggests a player who has rediscovered competitive momentum since becoming a mother in 2023.
The Sabalenka match is the most difficult test yet — the Belarusian won all three of their 2026 encounters prior to today. But regardless of today's result, Osaka has already locked in prize money deep into Wimbledon's second week, where round-of-16 payouts are estimated in the range of £330,000 from a total prize fund exceeding $85 million.
Yet even that figure pales beside what a single extended endorsement deal generates over a multi-year horizon. It is a reminder that in the modern sports economy — and the modern professional economy more broadly — financial security rarely flows from any one income source alone.
Five Questions Worth Asking a Wealth Management Adviser
If your income varies significantly from year to year, these are the conversations that matter most with a qualified Canadian wealth management professional:
- How much RRSP contribution room have you accumulated, and when is the right year to deploy it?
- Are you making quarterly tax instalments to avoid year-end CRA penalties?
- Do you have a cash reserve to bridge low-income months without touching long-term investments?
- Is professional incorporation the right vehicle to retain and distribute earnings over time?
- Have you stress-tested your financial plan against a year of zero income from your primary source?
Osaka answered that last question the hard way in 2021. The good news for Canadians is that the conversation does not have to start with a crisis.
This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial adviser for personalized guidance.
Expert Zoom connects Canadians directly with certified wealth management professionals who specialize in variable income, multi-stream earnings, and the tax planning that turns a high-earning year into lasting financial security.
