 Julia Vachon
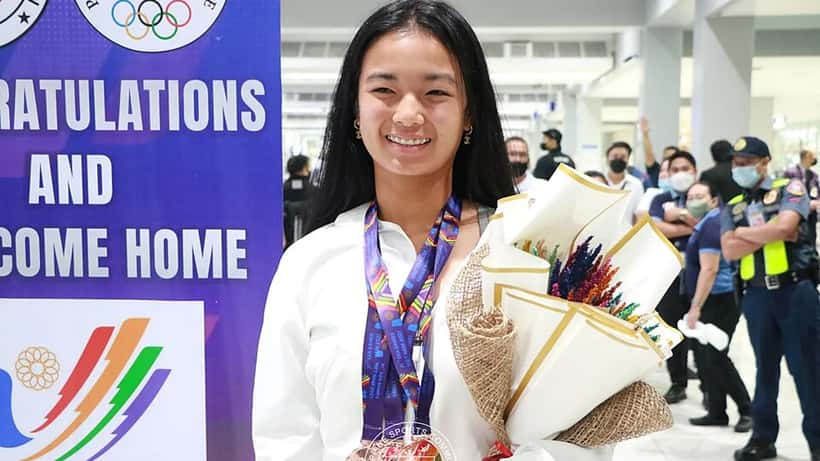
Alexandra Eala just made history in Berlin. On June 19, 2026, the 21-year-old Filipino sensation defeated World No. 2 Elena Rybakina in straight sets at the Berlin Open WTA 500. She then ousted Elina Svitolina 6-3, 6-4 on Friday to book her first WTA 500 semi-final spot. The prize: at least €57,395 — roughly C$85,000 — before today's match against Linda Noskova even begins.
With a 9-1 grass-court record this season, Eala's rise from WTA 125 champion to WTA 500 semi-finalist is one of sport's most compelling breakout stories of 2026. But beneath the headlines lies a financial reality that catches many young athletes off guard: managing tournament-based income requires a strategy most 21-year-olds simply don't have.
For Canada's rising generation of athletes — in tennis, hockey, skiing, or any sport — Eala's Berlin breakthrough is a lesson in both what is possible financially and what planning it takes to protect it.
Eala's Berlin Numbers: What €57,395 Looks Like in Practice
The WTA Berlin Open is a tier-500 event, sitting just below the Grand Slams and Premier Mandatory tournaments in prize money and ranking points. In 2026, the total purse stands at €1,049,075 — a 13.3% increase from 2025. Here is what Eala locked in at this event alone:
- First round: €11,045 + 1 ranking point
- Second round: €15,471 + 60 ranking points
- Quarterfinal: €29,110 + 108 ranking points
- Semi-final (guaranteed): €57,395 + 195 ranking points
That is €57,395 confirmed in less than a week. Should she win the final on June 21, she would pocket an additional €161,310. These figures exclude her Birmingham Open WTA 125 title from earlier this month, sponsorship income, and appearance fees.
At 21, Eala is already navigating a complex multi-stream income that most people won't encounter in a lifetime.
Why Tennis Prize Money Is Harder to Manage Than It Looks
Prize money in professional tennis is inherently unpredictable. A first-round loss earns roughly €11,000. A semi-final at a tier-500 event earns €57,000. The same player, two weeks apart, can face earnings that differ by a factor of five.
This volatility creates real financial planning challenges:
- Tax exposure varies by country: Tournament winnings are typically taxed where they are earned. A Canadian athlete competing in Germany faces different withholding requirements than one playing in the United States or the United Kingdom.
- No employer benefits: Unlike salaried employees, professional athletes have no pension, no employer-matched RRSP contributions, and no group health insurance.
- Career longevity is uncertain: The average professional tennis career lasts 8-12 years. Injuries can end it overnight — as Svitolina, Eala's opponent on Friday, knows well after her own extended recovery and return to the tour.
According to the Financial Consumer Agency of Canada, many young earners make the mistake of delaying financial planning until income "stabilises." In professional sport, income never fully stabilises — which means the early years are the most critical for building long-term security.
5 Wealth Management Lessons Every Rising Athlete in Canada Needs
1. Treat every tournament like a tax event
Each WTA cheque comes with withholding tax obligations in the host country, plus potential reporting requirements back home. A wealth manager experienced with athlete income can build a tax-efficient structure before the prize money arrives — not after. Waiting until tax season is one of the most expensive mistakes young athletes make.
2. Build a 12-month cash reserve first
Eala earned nothing from her second-round exit at last week's Queen's Club Championships, then secured €57,000 in Berlin days later. This kind of swing is entirely normal in professional sport. Maintaining a 12-month emergency fund — held separately from investment accounts — absorbs that income volatility without forcing you to liquidate assets at the wrong moment.
3. Maximise RRSP and TFSA contributions early
For Canadian athletes, the Registered Retirement Savings Plan and the Tax-Free Savings Account are two of the most powerful tax-sheltered vehicles available. Many athletes delay contributions, citing uncertainty about next year's earnings. A wealth advisor can calculate exactly how much earned income qualifies for RRSP deductions and ensure TFSA room is never left on the table.
4. Separate sports income from personal spending
Prize money, sponsorship payments, and personal expenses should never share a single account. When they do, it becomes nearly impossible to track true profitability — after coaching fees, physio, travel, and equipment costs are deducted — or to calculate taxes accurately. A simple two-account or three-account structure solves this immediately and costs nothing to set up.
5. Plan for the career after the career
Eala is 21, ranked inside the WTA top 40, and playing some of the best tennis of her life. Statistically, however, her peak earnings window is 5-10 years. A sound financial plan uses today's prize money to build passive income — through diversified investment portfolios — that continues well after her final match. Canadian players like Leylah Fernandez have navigated similar decisions early in their careers. Understanding how WTA prize money connects to long-term financial security is a skill as valuable as any shot in the game.
When to Bring in a Wealth Management Expert
If you — or your child — is generating C$30,000 or more per year from sport, a conversation with a wealth management specialist is warranted. Key questions to ask at that first meeting:
- Do you have experience structuring athlete income earned across multiple countries?
- How do you handle foreign tournament earnings and foreign tax credits?
- Can you model scenarios where income drops sharply — due to injury, poor form, or early retirement?
Alexandra Eala's Berlin semi-final is a moment of pure sporting joy. She came into this week as a qualifier-level outsider and leaves it as a WTA 500 finalist contender. But behind every €57,000 payday is a financial decision waiting to be made. For Canada's next generation of athletes, taking that decision seriously — and early — could be the most important move of their careers.
This article is for informational purposes only and does not constitute financial or investment advice. Consult a qualified wealth management professional for guidance specific to your situation.
