 Harper Brooks
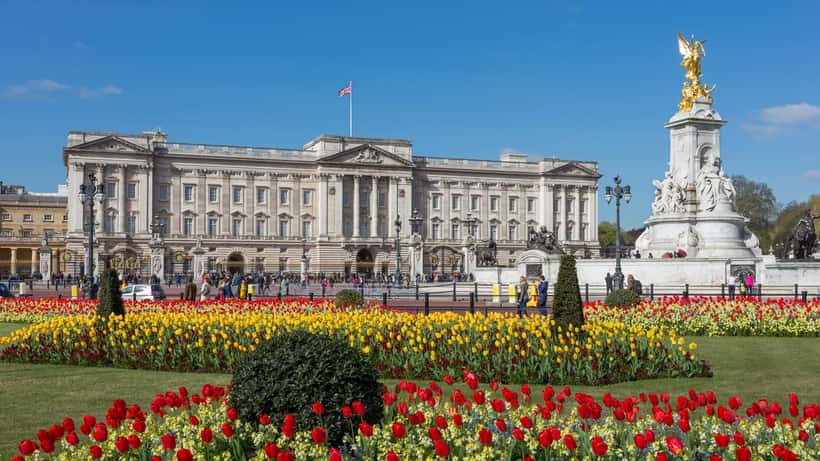
The British royal family has dominated headlines this September 2026 — from Duchess Sophie's high-profile diplomatic tour of Zambia to King Charles visiting Cairngorms National Park to thank wildfire responders, and Buckingham Palace's confirmation that Prince Andrew has been formally stripped of his royal titles. For most Americans, royal news is entertainment. But beneath every headline about succession disputes, estate disputes, and family fractures lies a set of financial and legal lessons that apply to anyone with a home, a retirement account, and people they love.
The Royal Headlines Behind the Lesson
King Charles, who was diagnosed with an undisclosed form of cancer in 2024, has continued public duties at a measured pace throughout 2026. His visit to Cairngorms National Park on September 29 came after an unusually destructive fire season: the summer of 2026 was the UK's warmest since records began in 1884, with multiple wildfires contributing to an estimated 2,877 heat-related deaths in England alone, according to the Royal Family's official site.
At the same time, the formal removal of Prince Andrew's titles — a process initiated in October 2025 — was confirmed by Buckingham Palace in September 2026. Andrew has been locked in a years-long dispute over Royal Lodge, where he continued to reside despite losing his taxpayer-funded security detail and income. The episode illustrates, in very public fashion, what happens when succession expectations are ambiguous, property rights are contested, and legal obligations were never clearly defined in writing.
Meanwhile, Prince William is quietly managing the Duchy of Cornwall — a billion-pound land holding generating approximately £23 million annually from farming, residential, and commercial properties — while simultaneously serving as the working heir to the throne. The contrast between Andrew's chaotic exit and William's structured inheritance is not accidental. It reflects decades of deliberate planning.
What the Crown's $28 Billion Strategy Actually Looks Like
The British royal family's estate is estimated at approximately $28 billion, held through a complex network of trusts, grants, and statutory mechanisms. Some of those trusts date back to the 14th century. The Sovereign Grant covers the operational costs of working royals. The Crown Estate — a separate entity managed by the government — generates billions in revenue that flows to both the Treasury and the Royal Household.
The key strategic element is the deliberate separation of ownership from personal wealth. Under UK law, assets passing from one sovereign to the next are entirely exempt from the 40% inheritance tax that applies to ordinary British citizens. That carve-out has allowed royal wealth to compound across generations without the erosive effect that inheritance taxes impose on most family estates.
"What the royals have done for centuries, high-net-worth American families are only beginning to implement," notes one wealth management attorney who specializes in multi-generational trusts. "The core principle is simple: separate ownership from control, and define the terms of succession before a crisis forces the issue — because once a crisis has started, your legal options narrow dramatically and your costs multiply."
The Andrew situation proves the point. A written succession framework, agreed to by all parties in advance, would have resolved the Royal Lodge question before it became a years-long public spectacle. For most American families, the equivalent isn't a castle — it's a house, a retirement account, or a small business that a second marriage or an estranged sibling could complicate overnight.
Three Royal Principles Any American Can Apply
1. Trusts aren't just for billionaires. A revocable living trust allows assets — a family home, investment accounts, business interests — to pass directly to heirs without going through probate court. According to the Trust & Will 2026 Estate Planning Report, only 33% of Americans have any estate plan at all, and fewer than half of those with minor children have updated their documents in the past five years. The cost to establish a basic revocable trust typically ranges from $1,500 to $3,000 with an attorney — a fraction of average probate costs.
2. Succession clarity prevents family conflict. The Andrew dispute is a high-visibility version of the disputes that play out in probate courts every week across the United States: competing claims, ambiguous expectations, and the assumption that "we'll work it out when the time comes." They rarely do. A clearly drafted will, an updated beneficiary form on every financial account, and a durable power of attorney are the minimum toolkit.
3. Define roles, not just assets. The royals don't only name who gets what — they define who manages what, and under what conditions. In American estate planning, a healthcare proxy and durable financial power of attorney serve the same function. These documents designate who makes decisions if the primary account holder is incapacitated — critical in any family with complex finances, a medical history, or a business that can't pause for a probate court's timeline.
Concrete Case: The $1 Million Blended Family Estate
Consider a 58-year-old homeowner in Ohio — call him David. He holds a home worth $450,000, a 401(k) with $310,000, and a life insurance policy with a $250,000 death benefit, for a total estate of approximately $1,010,000. He is in his second marriage. He has two adult children from his first marriage and a 15-year-old from his current marriage.
Without a trust or updated beneficiary forms, here is what happens at death under Ohio intestacy law if David has no current will: his surviving spouse receives the first $20,000 plus one-half of the remaining estate; the adult children split the remaining half. The minor child would require a court-appointed guardian to receive and manage their share until age 18 — a process that typically costs $3,000–$8,000 in legal fees and takes 12 to 18 months to resolve in probate court.
The 401(k) and life insurance are even more exposed. These assets do not pass through a will. They pass directly to whoever is listed as the named beneficiary on the account form. If David filed those forms during his first marriage and never updated them, his ex-spouse could legally receive the entire $250,000 life insurance payout — regardless of what any divorce decree, will, or trust says. Federal courts have consistently upheld beneficiary designations as superseding all other documents, including divorce settlements.
If David establishes a revocable living trust and updates all beneficiary forms, the house passes immediately to his named heirs with zero probate exposure. The 401(k) names his current spouse as primary beneficiary and his children as contingent. The life insurance is corrected. The minor child's share is directed into a custodial account managed by a named trustee until age 25 — David's preference, not a court's default. Total cost of the update: approximately $2,500 in legal fees and two hours of paperwork. The savings in avoided probate costs and potential litigation: potentially $40,000 or more.
When to Consult a Professional
Not every estate scenario requires an attorney, but several situations clearly do:
- You own real property in more than one state (each state has separate probate jurisdiction)
- You have a blended family with children from multiple relationships — as in the scenario above
- Your business has co-owners who haven't signed a buy-sell agreement
- Your estate is approaching the federal exemption threshold
For 2026, the federal estate tax exemption sits at $13.99 million per individual, as noted in the IRS estate tax guidance. However, that threshold is currently scheduled to drop to approximately $7 million per individual in 2026 when Tax Cuts and Jobs Act provisions sunset — a change that could expose a significantly larger number of American families to federal estate tax for the first time.
For anyone with a straightforward situation — married once, same-state property, assets well below $5 million — an online estate planning platform combined with a single attorney review session may be entirely sufficient. The goal isn't the complexity of the document; it's the completeness of the beneficiary designations and the recency of the review.
The Royal Reminder
Watching King Charles manage a cancer diagnosis while continuing public duties, seeing the Andrew dispute play out in slow motion over property and titles, and observing Prince William systematically preparing to inherit one of the world's most complex institutional estates — all of it is a reminder that succession isn't theoretical, and that clarity beats conflict every single time.
The royals have had centuries to build the legal infrastructure that protects their wealth across generations. Americans have the same tools available — trusts, beneficiary designations, powers of attorney, healthcare directives — at a fraction of the cost, through any qualified estate attorney or wealth management advisor.
If your estate documents haven't been reviewed in the past three years, or if your family structure has changed since you last updated them, the time to act is before a health scare or a family dispute forces the issue. A 90-minute consultation with a qualified professional can mean the difference between your family inheriting your legacy intact — or spending 18 months in probate court trying to recover it.
This article is for informational purposes only and does not constitute legal or financial advice. Consult a licensed estate attorney or certified financial planner for guidance specific to your situation.
