 Harper Brooks
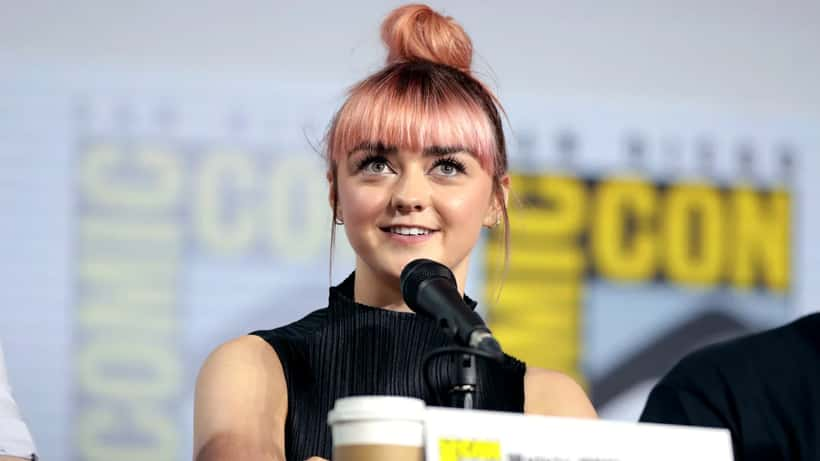
As Practical Magic 2 opens in theaters on September 10, 2026, its star Maisie Williams is marking a milestone beyond the silver screen: she is turning 30, closing the chapter on the two decades that began when she stepped onto a Game of Thrones set at the age of 11. Williams told Who What Wear UK that she has spent years building "a kind of more normal life" alongside her onscreen roles — a goal many former child stars find elusive, especially when it comes to their finances. The gap between what young performers earn and what actually remains accessible to them at adulthood is one of the most persistent problems in entertainment finance.
Williams' career trajectory — and the milestone of her 30th birthday — highlights a systemic issue that wealth management professionals identify every year: the disconnect between what a minor earns during peak earning years and what survives by the time they reach adulthood. California's Coogan Law mandates that employers withhold 15% of a minor performer's gross earnings in a blocked trust account, but the remaining 85% is entirely at the discretion of parents, guardians, or managers — and in many documented cases, it is largely gone long before the performer turns 18.
Practical Magic 2 and the Child Star Who Grew Up
Williams plays Antonia in Practical Magic 2 — the daughter of Sandra Bullock's character Sally Owens — alongside Joey King, in a Susanne Bier-directed sequel generating significant pre-release attention. The film arrives as Williams reflects publicly on balancing fame with a grounded private life in the English countryside.
Her story mirrors that of dozens of performers who built careers in youth and now find themselves assessing what those years left behind. Game of Thrones ran from 2011 to 2019, during which Williams rose from a newcomer to one of the show's most prominent stars. Her earnings during that period — like those of any minor working on a major US production — fell under the jurisdiction of California's child performer regulations. In 2026, those regulations were significantly updated through AB 1880, adding new transparency requirements: employers must now provide written verification of blocked trust deposits to both parents and the minor performer, closing a loophole that had allowed some Coogan Accounts to go unfunded for months before anyone noticed.
The Child Content Creator Rights Act (SB 764), signed into law in California in 2025, extended these protections further, applying Coogan Law requirements to minors earning income through YouTube, TikTok, Twitch, and other content platforms. As of 2026, any minor earning more than $1,500 in a 30-day period from content monetization triggers the 15% blocked trust requirement.
What the 15% Rule Protects — and What It Doesn't
Wealth management professionals who specialize in entertainment clients consistently describe the Coogan Law as a floor, not a financial plan. The 15% blocked trust is a legal safeguard, not an investment strategy. The trust does not automatically compound, it does not diversify across asset classes, and it does not account for the federal "kiddie tax" that applies to a minor's unearned income above a threshold ($2,600 in 2026) at the parents' marginal rate.
The blocked trust itself is not automatically placed in an investment account. Unless a parent or guardian specifically opens an interest-bearing Coogan Account through an institution — a bank, credit union, or brokerage — the funds may sit in a basic account earning minimal returns. According to the California Department of Industrial Relations, all employers of minor performers in California must establish or verify a Coogan Account within 15 business days of the minor's first payday — a deadline that has historically been loosely enforced but now carries heightened documentation requirements under the 2026 amendments.
Even under the protected structure, many child performers arrive at adulthood with only the Coogan Account to show for years of professional work. The remaining 85% is frequently absorbed by agency commissions (standard SAG-AFTRA agreements allow up to 10%), management fees (another 15–20% is common), coaching and workshop costs, production-related travel, and basic family living expenses. A performer who earns $300,000 over a six-year career might see only $45,000 sitting in a blocked trust when they turn 18 — with everything else already spent.
What Happens to a Child Star's Earnings: A Concrete Scenario
Consider a 13-year-old actress who books a recurring role on a major streaming series. Over five seasons spanning ages 13 to 18, she earns a total gross of $600,000.
Under California's Coogan Law as amended in 2026:
- $90,000 (15%) is deposited directly into a blocked Coogan Account. Her parents cannot touch it; she cannot access it until she turns 18.
- $510,000 (85%) is released to her parents or legal guardian and subject to no legal restriction on how it is spent.
If the Coogan Account is opened at a credit union earning a conservative 4.5% annual return starting at age 13, the $90,000 grows to approximately $175,000 by her 30th birthday — a meaningful but not life-changing sum.
Now apply the wealth management variable. Suppose her family engaged a fee-only financial advisor when she was 14, who structured even a modest $40,000 of the 85% pool into a broad-market index fund inside a custodial brokerage account earning an average 7% annually. By age 30, that $40,000 alone would grow to approximately $120,000 — without a single additional contribution. Together with the Coogan Account, she arrives at 30 with roughly $295,000 from childhood earnings instead of $175,000 — a 69% improvement from one strategic early decision.
The if/then logic is clear: if a family invests even a portion of the unprotected 85% through a properly structured custodial account when the performer is a minor, then the compounding over 12–17 years produces a materially different financial baseline at adulthood. The gap between a family that does this and one that does not is often the difference between a comfortable financial foundation and a performer who must start from zero at age 18.
What AB 1880 Changes for Families in 2026
The 2026 update to California's Coogan Law tightened several provisions:
- Written verification is now required within 15 business days of the first payment — not simply "upon hiring," which was previously interpreted loosely.
- Parents must receive a deposit statement each time a new contribution is made to the blocked trust.
- Minors aged 16 and older must receive their own copy of trust statements, separate from their parents — acknowledging that a near-adult performer has a legitimate interest in tracking their own finances.
- Content creator protections now apply to any minor earning more than $1,500 in a calendar month from platform monetization, closing the gap for a generation of young influencers whose earnings had previously gone entirely unprotected.
For families in entertainment industries in 2026, these changes generate more paperwork — and more opportunities to catch underfunded accounts before years pass without correction.
What Performers and Families Should Do Now
Maisie Williams' 30th birthday, coinciding with the release of a major studio film, is a useful cultural anchor for a financial question that applies to thousands of young performers across the country. Wealth management professionals recommend three specific steps for families navigating a minor's entertainment career:
Verify the Coogan Account before the first paycheck clears. California law requires this, but enforcement has historically been inconsistent. Request written confirmation of the account number, the institution, and the deposit amount for each payment cycle. Under AB 1880, this documentation is now mandatory — but families must ask for it.
Treat the 15% as the floor, not the plan. Work with a fee-only financial advisor to determine what portion of the 85% unrestricted earnings can be preserved in a UTMA (Uniform Transfers to Minors Act) account, custodial brokerage account, or other vehicle suited to the family's tax situation. Contributions to a UTMA account for a minor can be invested in equity funds and transferred to the child's sole ownership at 18 or 21, depending on state law.
Model the tax exposure early. Minor performers' unearned income above $2,600 (the 2026 "kiddie tax" threshold) is taxed at the parents' marginal federal rate — which can reach 37% for high earners. Quarterly estimated tax payments, proper deduction tracking for legitimate work expenses, and a dedicated savings buffer for tax obligations can prevent large year-end bills from consuming capital that might otherwise compound for two decades.
For performers who have already reached adulthood and are reviewing what their childhood career left behind, the checklist is different: confirm the Coogan Account was properly funded for every production, request full account history from the managing institution, and consult a wealth management professional about how to strategically deploy the trust balance in the context of their current tax situation and financial goals.
Much like the career path of young Hollywood actresses navigating both art and income, Maisie Williams' story reminds us that financial planning for performers cannot be an afterthought. The first professional paycheck a minor receives is also the first window in which compounding can begin working in their favor — and one of the few moments when a wealth management expert can make decisions that still have decades to grow.
This article provides general financial and legal information for educational purposes only and does not constitute financial advice. Minor performers' earnings involve complex tax, legal, and financial planning considerations that vary by state. Consult a licensed wealth management professional and a qualified tax advisor for guidance specific to your situation.
