 Michael Campbell
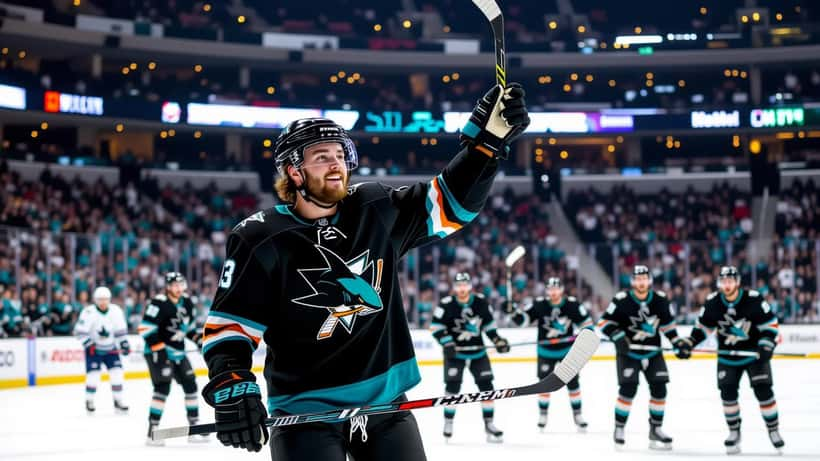
When San Jose Sharks defenseman Luca Cagnoni buried a five-hole shot past Florida Panthers goalie Akira Schmid 3:14 into overtime on October 2, 2026, he made franchise history: the first player in Sharks history to score their first-ever NHL career goal in overtime. He was 21 years old, playing just his 10th NHL game, and in one moment the entire hockey world knew his name.
But behind the highlight reel, the locker room celebration, and the Calder Trophy buzz now circulating in fantasy hockey circles, a different kind of clock is already ticking — the financial one. In a sport where the average NHL career lasts roughly 4.5 years, where entry-level contracts cap earnings during the most formative years, and where a single defensive-zone collision can end everything, the window to build lasting wealth is narrow, front-loaded, and surprisingly easy to miss.
The Entry-Level Contract: What the Numbers Actually Look Like
Most hockey fans imagine first-year NHL players earning millions. The reality under the current collective bargaining agreement is more constrained. For the 2026-27 season, the maximum total compensation on an NHL entry-level contract — NHL base salary, signing bonus, and games-played bonuses combined — is $1,025,000. The base salary cap alone is $950,000 per season.
For players aged 18 to 21 at signing, like Cagnoni, the ELC runs three years. That means a fourth-round pick who does everything right — makes the roster, produces at a solid pace, earns positive reviews — may generate total guaranteed NHL earnings of roughly $2.85 million over three seasons before performance bonuses.
According to the National Hockey League Players' Association (NHLPA), these structures are designed to balance franchise cost control with player access to the league — but they also mean that a breakout overtime goal does not translate immediately into financial security.
What a Wealth Advisor Sees While the Arena Celebrates
A financial planner specializing in professional athletes watching that October 2 overtime celebration would not be focused on the scoreboard. They would be thinking about the next 36 to 48 months — and specifically, the decisions Cagnoni and his family make in the first 90 days of his first full NHL season.
Professional athletes face a financial profile that is almost the reverse of a standard career: peak earnings arrive in the mid-twenties, tax exposure is immediate and spans multiple jurisdictions, and career-ending injury is a statistical reality rather than a hypothetical. For an NHL defenseman — a position requiring sustained physical contact — that risk is not abstract.
The pressure points a wealth management specialist flags immediately include: agent commissions of 3 to 4% of total contract value, state and municipal income taxes in every city where games are played (known in financial circles as the "jock tax"), the compressing of peak earning years into a very short window, and the absence of traditional employer-sponsored retirement vehicles beyond NHLPA collective programs.
Then there is what many call the lifestyle inflation trap — the shift from AHL wages ($187,500 per season) to an NHL salary that feels transformative but is substantially reduced by taxes, fees, and living costs in NHL cities. San Jose is among the most expensive cities in the United States.
For context on how other young NHL players have navigated financial turning points, see how the $90 million offer sheet changed the equation for Leo Carlsson — and what that illustrates about the wealth management decisions tied to contract leverage.
A Concrete Scenario: The Real Math Behind an ELC Season
Consider the financial picture of a 21-year-old fourth-round defenseman beginning his first full NHL season in San Jose in 2026-27.
Gross annual base salary: $950,000
Agent commission (4%): −$38,000
Federal income tax (marginal rate at this income level): approximately −$218,000
California state income tax (home games in San Jose): approximately −$113,000
Jock tax across away-game cities over 41 road games: −$14,000 to −$22,000
Health and disability insurance: −$8,000
Estimated net annual take-home: roughly $559,000 to $573,000
Now the critical if/then: if this player begins investing $200,000 per year in a diversified portfolio from the first month of the ELC — starting at age 21 — a wealth manager projecting a 6% annualized return would estimate roughly $720,000 in invested assets by the end of the three-year contract, before any second-contract earnings begin.
Change one variable: the player waits two years, spending freely in the early career excitement. The starting base at year three drops from $400,000 (two years at $200,000) to zero. The compounding head start is erased — and for a player whose NHL window may close at 26 or 27, those first two ELC years are irreplaceable. There is no version of this story where deferring wealth management until a second contract produces the same outcome as starting during the first.
The Multi-State Tax Reality Almost No One Explains to Rookies
The single most underestimated financial complexity facing young NHL players is the jock tax: the obligation to file income tax returns in every state where wages are earned through professional play. An 82-game NHL regular season touches more than a dozen states. A playoff run adds more.
California, where the Sharks play all 41 home games, has the highest marginal state income tax rate in the United States — 13.3% on income above $1 million, and 9.3% on income between roughly $68,000 and that threshold. At a $950,000 base salary, the California state tax exposure alone can exceed $110,000 annually.
For away games, states such as New York (up to 10.9%), Massachusetts (5%), and Minnesota (9.85%) each trigger their own filing requirements proportional to the share of games played there. A CPA who specializes in professional sports — or a wealth management professional who coordinates tax strategy across jurisdictions — builds estimated quarterly payments that prevent a six-figure tax bill arriving in April when a player expected a refund.
Many young athletes, entirely unfamiliar with multi-state tax mechanics, underpay throughout the season and face a cash shortfall at filing. This is not an edge case. It is one of the most common financial missteps in the first two years of an NHL career.
Endorsements: When New Income Complicates the Picture
Cagnoni's overtime winner, his Calder Trophy candidacy, and his now-national profile will almost certainly generate endorsement inquiries — a local automotive sponsor, an equipment deal, a regional financial institution. These can arrive quickly in the weeks following a breakout moment.
Endorsement income is not treated as salary income under U.S. tax law, but it adds directly to adjusted gross income and can push a player into higher federal and state brackets faster than anticipated. A $75,000 endorsement deal on top of a $950,000 salary crosses the $1 million threshold that triggers California's highest marginal rate — creating additional tax liability that an unprepared player may not have budgeted for.
A wealth management consultant can model how each endorsement deal interacts with base salary, structure payment timing to smooth tax exposure across tax years, and review the intellectual property terms of any agreement to ensure a player retains appropriate rights over their likeness and social media use in post-career contexts.
The Right Time to Consult a Wealth Management Professional
Conventional wisdom holds that financial planning is for when the big money arrives — the second contract, the first All-Star nomination, the extension year. The evidence from professional athlete financial outcomes says otherwise. The players who build durable wealth consistently begin formal wealth management during the ELC period, not after it.
An ExpertZoom wealth management advisor can help a young professional athlete — or their family — map the full three-year ELC picture in concrete numbers, identify multi-state tax filing obligations before they become penalties, compare individual investment vehicles with NHLPA-accessible retirement structures, and stress-test scenarios that most 21-year-olds would prefer not to think about: injury, AHL demotion, or an early career transition.
The question is not whether Luca Cagnoni will be successful — that overtime goal suggests he will be. The question is whether the financial decisions made in the 90 days after that goal will still be working for him when he is 40.
A Short Career, A Long Life After the Ice
The NHL median career length is approximately 4.5 years. A defenseman who reaches the league at 21 may be done by 26 or 27, with four to five decades of post-career life ahead. The compound interest advantage of beginning in the first ELC year versus waiting is not theoretical — it is the difference between financial security and financial pressure in the years that follow the last game.
Luca Cagnoni scored a goal that made Sharks history. The next goal worth celebrating may be a different kind of plan entirely.
Disclaimer: This article is for informational purposes only and does not constitute personalized financial, tax, or investment advice. Readers should consult a qualified wealth management professional, CPA, or financial advisor for guidance specific to their situation.
