 Michael Campbell
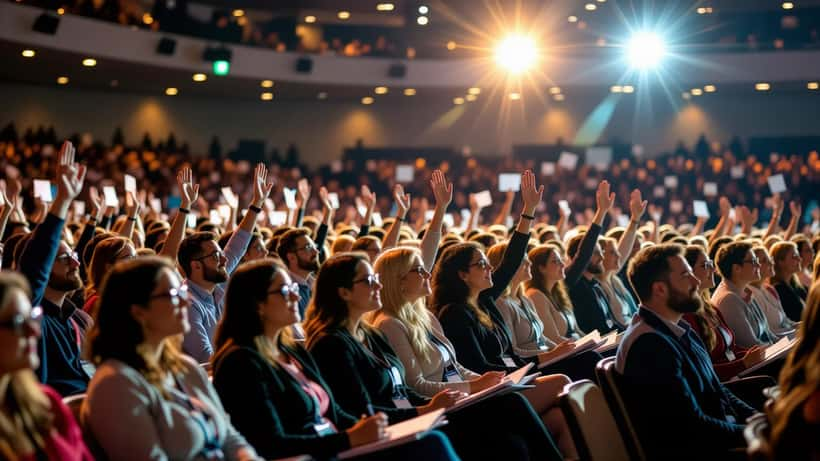
Life Surge Portland closed its doors on September 19, 2026, leaving nearly 5,000 attendees streaming out of the Oregon Convention Center with handwritten goals, fresh conviction, and — according to financial planners who work with faith-driven clients — a 72-hour window to make any of it stick.
The event is the latest stop on Life Surge's ambitious 2026 national tour, which has already rolled through Orlando, West Palm Beach, Los Angeles, Baton Rouge, Sacramento, and St. Louis. Each city, the same formula: one day, one arena, thousands of Christians focused on what the organization calls "the 4 W's of Kingdom impact" — Worship, Wisdom, Work, and Wealth.
The wealth piece is what's generating the most post-event conversation. And wealth advisors are paying close attention.
What Life Surge Is — and Why Financial Advisors Are Watching
Life Surge is a for-profit live events and education company that has found an underserved niche: the gap between Christian conviction about money and actual financial behavior. While most faith-based financial content stays at the level of principle — "be a good steward," "give generously" — Life Surge brings in speakers and educators who push into specifics: business strategy, investment vehicles, estate planning, and the mechanics of giving at scale.
That's unusual in this space, and it's clearly resonating. The Sacramento stop in 2026 saw 1,612 documented decisions — people publicly committing to financial changes, new giving goals, or business pivots. Portland appears to have followed the same pattern.
For certified financial planners and wealth advisors, the Life Surge moment represents both an opportunity and a challenge. The opportunity: clients who walk in motivated to make real changes to their finances. The challenge: motivation without a structured plan evaporates quickly, often within weeks.
"I've had clients come in the Monday after a Life Surge event fired up to give away $50,000 a year," one wealth advisor who has worked with multiple Life Surge alumni described. "That's a beautiful goal. But when I ask them what their current liquid assets are, or whether they have an emergency fund, the conversation has to shift pretty quickly."
The Pattern That Advisors See Every Time
The arc that financial advisors describe is consistent across faith-based financial events, not just Life Surge. Attendees leave with elevated ambition — a giving goal, a tithing pledge, a business idea, a target retirement date — but rarely leave with the underlying financial architecture to support those ambitions.
The gap is not about faith. It is about financial literacy and planning infrastructure.
According to the CFP Board, roughly 47% of Americans lack any written financial plan, and that percentage is higher among middle-income households — precisely the demographic most likely to attend a one-day event like Life Surge. Without a written plan, even the most sincere financial commitments suffer from what planners call "goal drift": the inspiration fades, competing expenses crowd out giving, and the commitments made on a Saturday in Portland quietly disappear by October.
What advisors who specialize in faith-aligned wealth management consistently say is needed is a structured translation — converting the emotional and spiritual commitments of an event like Life Surge into a documented, numbered, timeline-bound financial plan. That translation rarely happens automatically, because no one at the event is positioned to do it. That is precisely what a certified financial planner is for.
What Happens When a Portland Attendee Actually Books That Appointment
Picture a realistic scenario based on the typical Life Surge attendee: a 38-year-old married professional in Portland — let's call her Dana — who earns $95,000 per year, holds $40,000 in a savings account, contributes 6% to a 401(k) to capture her employer match, and carries no high-interest debt. At Life Surge on September 19, 2026, Dana commits publicly to a $10,000 annual giving goal — roughly double what she currently gives. She also jots a note to "look into Kingdom investments" and write a will before year-end.
If Dana goes home and takes no structured action in the next 72 hours, the data is not encouraging. Within three months, her giving will increase modestly — perhaps $200–$300 per month rather than the $833 per month required to actually hit $10,000 annually. The "Kingdom investments" note will stay in a notebook. The will won't be written.
If Dana books a 90-minute consultation with a certified financial planner within a week of the event, the math changes entirely.
A planner would identify that her $40,000 in savings splits into three buckets: $15,000–$18,000 should stay as a six-month emergency fund (the standard threshold at her income level), approximately $10,000 could fund her giving goal for Year 1 without touching monthly cash flow, and the remaining $12,000–$15,000 could be repositioned into a donor-advised fund (DAF) — a giving vehicle that lets her take the charitable deduction in 2026, grow the assets tax-free, and grant to nonprofits on her own timeline over the coming years.
The DAF strategy alone could save Dana approximately $2,800–$3,200 in federal taxes in 2026, depending on her itemization status — money that could itself be redirected toward the giving goals she set at the event. If she waits three months before acting, she will likely give $3,000–$4,000 this year and consider it a reasonable start. If she acts this week with a structured plan, she has a realistic path to $10,000+ in Kingdom impact with meaningful tax efficiency built in.
The difference is not willpower. It is infrastructure, and an advisor builds that infrastructure in a single session.
Three Moves a Certified Wealth Advisor Will Walk You Through This Week
Advisors who work with faith-aligned clients describe a consistent post-event playbook for Life Surge alumni.
Write the goals with numbers. "I want to give more" is a sentiment. "I want to give $10,000 by December 31, 2026" is a financial goal. "I want to build wealth for the Kingdom" is a value. "I want to contribute $25,000 to a donor-advised fund by age 50" is a planning target. Unquantified goals are not goals — they are intentions that evaporate under the pressure of real expenses.
Run the gap analysis. An advisor will look at current income, expenses, liquid assets, and debt and calculate the actual surplus available for giving and strategic investment. For many Life Surge attendees, this number is higher than expected — especially once tax-efficient giving vehicles like DAFs, charitable remainder trusts, or qualified charitable distributions from IRAs are factored in. The gap analysis reveals what is actually possible, which is often more than the attendee assumed.
Build the funding mechanism. The goal should not come out of willpower — it should come out of the budget, structured as an automated process. Automatic transfers on the 1st and 15th, pre-tax retirement contributions, or quarterly DAF contributions are mechanisms, not motivations. Mechanisms keep commitments intact in November when car repairs and holiday spending compete for the same dollars that felt so freely available in September.
None of these steps are spiritually complicated. All three are operationally specific. That specificity is exactly what the post-event moment requires — and what a certified planner delivers.
The Estate and Business Dimension Life Surge Opens Up
For attendees who also run businesses or hold significant assets, the post-event planning need extends into estate planning and succession. Life Surge's programming addresses Kingdom wealth transfer — the conviction that Christians should be intentional about where wealth flows after death, not only during life.
But intent without legal documentation is legally worthless.
A will, a revocable living trust, updated beneficiary designations on IRAs and life insurance policies, and a charitable bequest clause — together these require approximately three to five hours of attorney and planner time to implement correctly. Many attendees leave Life Surge with the sincere intent to do this. Very few have a scheduled appointment within the month. An estate attorney working in coordination with a wealth advisor can translate the "I want my wealth to outlive me for Kingdom purposes" conviction into legally enforceable documents.
That coordination is also something a wealth advisor can facilitate — connecting the dots between the event's spiritual framework and the legal, tax, and investment infrastructure that makes it durable.
Finding an Advisor Who Understands Both Worlds
Not every financial advisor understands the intersection of faith and finance. Some are skeptical of the giving ambitions that events like Life Surge produce. Others are unfamiliar with the mechanics of donor-advised funds, charitable remainder trusts, or values-aligned ESG investment screens that many faith-driven clients now prioritize.
The best fit for a Life Surge alumna like Dana is an advisor with demonstrated experience in charitable giving strategy and, if possible, familiarity with faith-aligned portfolio management. ExpertZoom's wealth management specialists include advisors who work specifically at this intersection — helping clients move from weekend inspiration to Monday-morning implementation with a concrete, numbered, deadline-bound financial plan.
The Oregon Convention Center has cleared out. The Life Surge 2026 tour continues toward its final stops. But for Portland attendees, the most consequential decision of the weekend is not the commitment written on a notecard on Saturday. It is whether a certified financial planner is on the calendar for this week.
That appointment is where inspiration becomes infrastructure — and where Kingdom impact stops being a goal and starts being a plan.
Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Individual circumstances vary. Consult a certified financial planner or qualified advisor before making financial decisions.
