 Bernard Stone
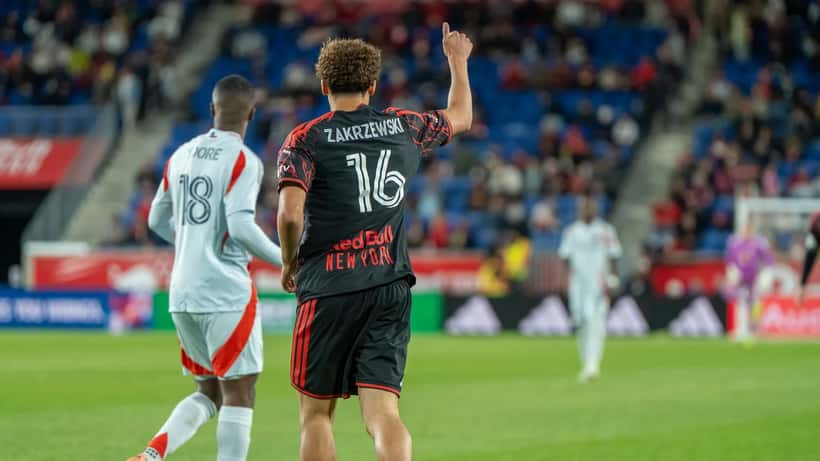
The moment Julian Hall stepped off the field on September 21, 2026 — having scored the decisive goal in a 1-0 Hudson River Derby win with the USMNT head coach watching from the stands — the 18-year-old New York Red Bulls forward became one of the hottest names in American soccer. Days earlier, Hall had received his first call-up to the US Men's National Team, capping a season in which he set the MLS record for youngest player ever to score a hat trick. Behind the headlines, a quieter but urgent story is playing out for families of young professional athletes like Hall: when extraordinary success arrives before your child turns 20, are you financially prepared?
The Rise That Rewrote the Record Books
Julian Hall's 2026 MLS season reads like a sports novel. At 18 years and 50 days old, he became the youngest player in league history to score a hat trick, netting three goals in a 3-2 win over Columbus Crew on May 13, 2026. He was named to the 2026 MLS All-Star Game roster as a commissioner's pick — the second youngest player in New York Red Bulls club history to receive the honor. By late September, he had racked up nine goals and four assists in 15 starts, logging over 1,200 minutes in an MLS season that hadn't yet reached the playoffs.
Then came the USMNT call-up on September 19, 2026, from head coach Mauricio Pochettino. Hall is reportedly still weighing his international options — but one thing is certain: his market value, earning potential, and public profile have never been higher.
What Wealth Advisors See When a Teenager Goes Pro
For wealth management professionals, Hall's trajectory represents a scenario they are increasingly asked to navigate: a minor or young adult who suddenly earns professional-level income with limited financial experience, surrounded by agents, sponsors, and family members with competing interests.
"The biggest mistake young athletes and their families make is treating the first big contract as arrival, not as the starting point of a financial plan," says the kind of independent wealth advisor you'd find through a platform like ExpertZoom. Several critical financial risks compound quickly at this stage.
Federal and state tax exposure is immediate. A professional athlete earning a significant salary in New York faces federal income tax plus New York State income tax (currently up to 10.9%) and New York City tax (up to 3.876%). Combined marginal rates can exceed 50 cents on every dollar above certain thresholds. Many young athletes discover this only when the first quarterly estimated payment is due — and the bill is larger than expected.
Agent fees and representation costs add up fast. MLS player agents are regulated by the league, but agents typically take 3-5% of base salary plus a negotiation fee on new contracts. On a $500,000 contract, that's $15,000–$25,000 before taxes — paid from after-tax dollars.
Endorsement income is treated differently from salary. If Hall signs an equipment deal or a commercial partnership, that income is typically paid to him as a sole proprietor or through an LLC, not as a W-2 employee. This creates self-employment tax obligations (15.3% on the first ~$170,000 of net earnings in 2026), separate quarterly filings, and the need for a financial structure that most teenagers have never built.
Concrete Case: The 18-Year-Old Who Didn't Plan Ahead
Consider this scenario — composite but entirely realistic given MLS pay structures in 2026.
A homegrown MLS player breaks out at 18, earning a base salary of $180,000 for the season, plus $40,000 in performance bonuses (goal bonuses, playoff appearances) and $60,000 in an equipment endorsement deal. His total gross income: $280,000.
If he does not engage a wealth advisor:
- Federal income tax (22-24% blended rate after deductions): approximately $55,000
- New York State + City taxes (combined ~14.5% effective): approximately $40,000
- Self-employment tax on the $60,000 endorsement (15.3% up to net): approximately $8,500
- Agent fee on base + bonus (4%): $8,800
- Take-home estimate: roughly $167,700
That's less than 60 cents on every dollar earned — and none of it has been structured for long-term growth, retirement savings, or career interruption (injuries are the most common financial catastrophe in professional sports).
If a wealth advisor is engaged from contract signing:
- An S-Corp or single-member LLC for endorsement income reduces self-employment tax by routing part as a distribution rather than wages, potentially saving $4,000–$6,000 annually
- A Solo 401(k) contribution up to $70,000 in 2026 defers taxation and begins compounding immediately
- Health and disability insurance policies structured correctly can protect against the income loss from a torn ACL — statistically, one of the top five most common career disruptions for attacking midfielders
- A formal "agent review" clause in the representation agreement, vetted by a sports attorney, protects against commission creep on future deals
The delta between planning and not planning in year one alone: $30,000–$50,000, and that gap widens every year the athlete is earning.
Why the Teen Years Are the Critical Window
Sports wealth advisors consistently identify the first 18–24 months of professional income as the make-or-break window. Habits set early — or not set at all — follow athletes throughout their careers. Several structural issues make this window particularly high-stakes for players like Hall.
The career is statistically short. The median MLS career length is under five years for outfield players. A teenager who earns $200,000+ annually from ages 18 to 25 — but does not save or invest systematically — can reach their late 20s with depleted earnings and no compounding base. A player who does save 25% of after-tax income from 18 onward, invested in diversified index funds, could retire from the game at 26 with over $500,000 in net investable assets, assuming modest 7% annual returns.
According to the IRS, athletes with income from multiple states (Hall plays road games across the US, making him liable for taxes in each state where he earns income) must file returns in each state and apportion income by games played there — a compliance burden that most people discover only after a penalty notice. Professional athletes are required to file in every state where they perform for compensation, per established nexus rules. See the IRS guidance on athletes and entertainers.
Dual eligibility decisions can have financial consequences too. Hall has publicly stated he is still weighing whether to represent the USMNT or another national team. While that is primarily a sporting decision, international representation can affect endorsement value, visa requirements for overseas transfers, and tax treaty status if he moves to a European league — all factors a wealth advisor should model before the decision is finalized.
What Families Should Do Now
If you have a teenager earning professional income — in any field, not just soccer — the steps are the same:
- Engage a fee-only fiduciary wealth advisor before signing any second contract. Fee-only means they are paid by you, not by commissions from products they recommend.
- Separate personal and business finances immediately. Open a dedicated business account and route all non-salary income there.
- Understand the tax calendar. Quarterly estimated tax payments are due in April, June, September, and January. Missing them triggers an underpayment penalty currently set at the federal funds rate plus 3 percentage points.
- Build a "career interruption reserve." Six months of gross expenses held in a high-yield savings account or short-term bond fund is the professional athlete equivalent of an emergency fund.
- Review agent contracts annually. A wealth advisor can work alongside a sports attorney to ensure representation agreements remain competitive as the athlete's market value grows.
The figures and scenarios in this article are illustrative only and do not constitute financial or tax advice. Consult a qualified financial advisor and tax professional for guidance specific to your situation.
ExpertZoom connects you directly with certified wealth managers and financial advisors who specialize in complex income situations — including young professionals, athletes, and anyone managing sudden significant earnings. You can book a consultation and get answers to your specific tax and investment questions from a vetted expert, without the upsell pressure of a traditional private bank.
Julian Hall's rise is a reminder that professional success and financial readiness are two separate skills. The first arrived in May 2026, on a grass pitch in Harrison, New Jersey. The second one takes a little longer — but it has to start just as early.
