 Harper Brooks
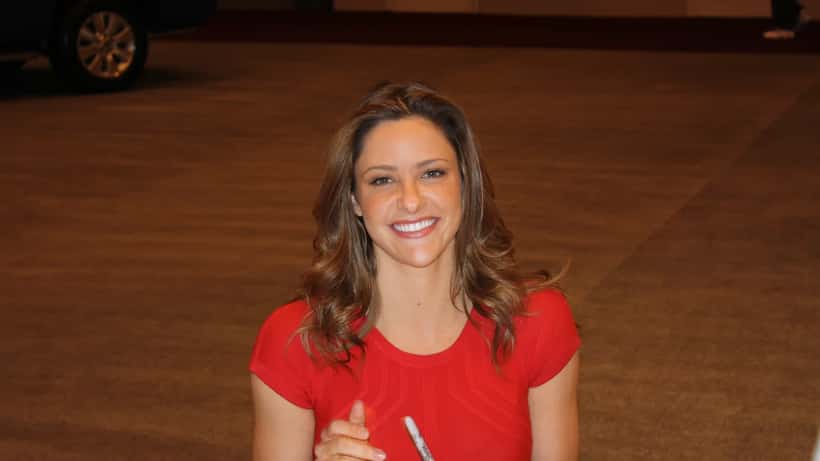
Fans scrolling through social media last week got a dose of genuine surprise: Jill Wagner, who plays the sharp and composed Kate in Taylor Sheridan's hit drama Lioness, spent six full seasons co-hosting ABC's obstacle-course chaos show Wipeout. The revelation ricocheted across Instagram and Reddit, with viewers marveling at how cleanly the actress had shed her game-show-host past. Wagner herself addressed the wave of disbelief with a lighthearted Instagram video — but behind the feel-good career story lies a financial transition that wealth advisors say is far more complicated than it looks.
The Career Pivot That Fans Missed — And the Money Behind It
Wagner co-hosted Wipeout from 2008 to 2014, a stretch that coincided with the reality-TV boom when unscripted programming paid surprisingly well for recognizable faces. Host fees on major network competition shows during that era ranged from $15,000 to $40,000 per episode depending on show ratings and network budget, according to entertainment industry reporting. At the high end of a 24-episode season, a principal host could earn close to $1 million in a strong year — but with significant tax exposure and zero residuals once the season aired.
Scripted drama is a different beast entirely. A guest or recurring role on a prestige drama like Lioness typically starts below network hosting rates. Series regular contracts for mid-tier drama cast members on streaming platforms or premium cable often begin in the $20,000–$50,000 per-episode range, with escalators built in across seasons. The key difference: residuals. Under the SAG-AFTRA Theatrical and Television Basic Agreement, actors in scripted content receive ongoing payments every time an episode re-airs, streams, or is licensed — income streams that game-show hosts simply don't generate.
For Wagner, the six-year gap between her last Wipeout season and her more prominent scripted work represents a transition window that financial planners say is one of the most financially precarious phases an entertainer can face.
What the Numbers Show About Hollywood Income Transitions
A 2025 SAG-AFTRA earnings report found that fewer than 15% of working actors earn more than $50,000 annually from acting alone. The top earners — those in series regular positions on prestige productions — benefit from a combination of upfront fees, backend participation, and residual streams that can continue paying for years after filming wraps.
The contrast with reality TV income is stark. The Screen Actors Guild-AFTRA distinguishes clearly between covered scripted agreements (which trigger residual obligations) and many unscripted formats (which often do not). A host who spends six years building income from a format with no residual tail enters any subsequent transition period without a passive income floor. When scripted bookings are inconsistent in the early years — which they almost always are — the earnings gap can be severe.
Wagner's trajectory, moving through Hallmark films, Teen Wolf, and eventually the Taylor Sheridan universe, is actually a textbook example of the "slow build" scripted transition. But each phase of that build carries distinct financial planning implications that many entertainers only address retroactively, often after costly mistakes.
The Concrete Case: What Happens When a TV Host Transitions Without a Plan
Consider this scenario, drawn from the profile of a composite entertainment client that wealth advisors frequently describe: a reality TV host earning $30,000 per episode over 20 episodes per year — $600,000 gross — for five consecutive seasons. Without proper structure, that income flows directly to the individual as W-2 or 1099 income, subject to federal tax rates up to 37%, plus California state tax of 13.3% for California residents, plus self-employment taxes if working as an independent contractor.
Now that host transitions to scripted work. The first scripted year might yield $180,000 from two guest arcs and a pilot that doesn't get picked up. The income drop is roughly 70%. If during the hosting years the host had not established a loan-out corporation — a standard S-corp or LLC structure used by most working actors — they likely overpaid federal and state taxes by $40,000–$80,000 annually compared to a properly structured peer earning the same gross. Over five years, that's $200,000–$400,000 in unnecessary tax exposure.
The loan-out also matters for the transition period itself. A corporation can carry forward losses, defer income across tax years, and provide a structure for maintaining health insurance continuity — a critical issue for entertainers losing union coverage during low-earning periods. If the host's SAG-AFTRA earnings drop below the threshold required for union health coverage ($26,470 in covered earnings as of 2026), they face a coverage gap that can cost $800–$1,500 per month on the individual market.
The if/then is clear: if a TV host transitions to scripted work without pre-established corporate structure and a 12–18 month income reserve, then the first scripted year — the one with the most irregular bookings — becomes financially catastrophic regardless of how high the headline rate appears.
How a Wealth Advisor Reads the Jill Wagner Story
Certified financial planners who specialize in entertainment clients identify three inflection points in a hosting-to-acting transition that require active management.
The tax-year bridge. In the final high-earning hosting year, proactive tax-loss harvesting, maxing out a Solo 401(k) contribution (up to $69,000 for 2026 for self-employed individuals), and accelerating planned business deductions can reduce the tax bill significantly before income drops. Many entertainers skip this because they're focused on the next project, not the current year's bill.
Residual enrollment and tracking. When scripted work begins, SAG-AFTRA requires residual payment tracking through specific channels. Entertainers who haven't worked under the Basic Agreement before sometimes miss residual checks entirely because they don't know to update their contact information with the union's residual department. Wagner's Lioness role, for instance, generates residuals each time an episode streams on Paramount+ — income that flows automatically only if the paperwork is properly filed.
Income smoothing via investment structure. A well-managed entertainment client in transition typically maintains a 12-month cash reserve in a high-yield account (currently paying 4.8–5.1% APY in 2026 for FDIC-insured products), while longer-term savings shift toward index funds or real estate investment trusts (REITs) that generate passive income independent of booking calendars. The goal is to ensure that a year with only two scripted bookings doesn't require liquidating retirement accounts — which triggers penalties and taxes on top of the income loss.
What This Means If You're Navigating a Major Income Shift
Jill Wagner's career story is genuinely inspiring — a successful reinvention from format television to prestige drama, built through patience and craft. But the financial scaffolding required to survive that transition is neither automatic nor intuitive, and most people navigating similar pivots — career changers, freelancers moving between industries, or self-employed workers experiencing income volatility — face the same structural challenges.
The core lesson that wealth advisors draw from stories like Wagner's isn't about celebrity: it's about the mismatch between how irregular-income earners are taxed and how they actually receive money. W-2 employees have taxes withheld smoothly throughout the year. Entertainers, freelancers, and independent contractors often receive large lump sums, underpay quarterly estimates, and face surprise bills — sometimes in the same year their income dropped.
A financial advisor specializing in variable-income clients can model the specific breakeven points for corporate structure, identify the optimal timing for income deferral, and build an investment allocation that provides income continuity during low-booking periods. These aren't abstract strategies: they're the difference between a career transition that's financially survivable and one that forces a return to any available work simply to cover expenses.
Whether you're an entertainer moving between formats, a consultant between retainers, or a professional changing industries, the underlying financial mechanics are identical. The income story hiding behind Jill Wagner's viral moment is one that plays out in some form for millions of workers — and the variables that determine whether it goes well are almost entirely within reach of proper advance planning.
Disclaimer: This article is for informational purposes only and does not constitute financial or legal advice. Consult a licensed financial advisor for guidance specific to your situation.
