 Michael Campbell
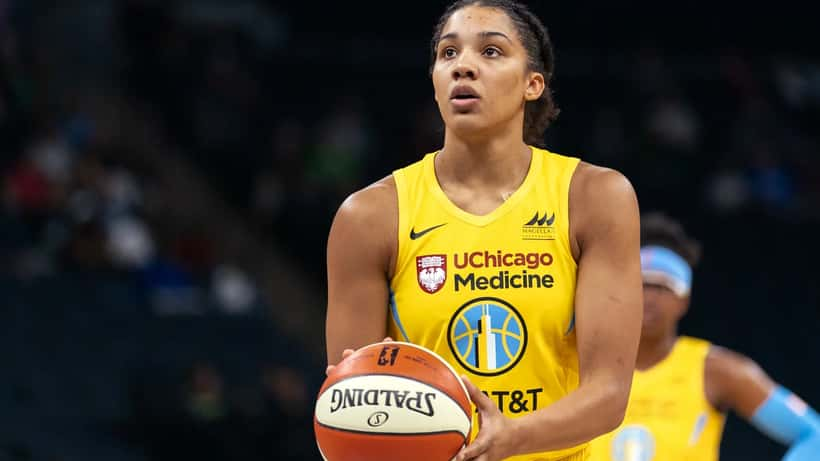
With the Golden State Valkyries leading the Las Vegas Aces 2-0 in the WNBA Semifinals as of October 9, 2026, Gabby Williams is closer to a WNBA Finals appearance than at any point in her nine-year professional career. The All-Star forward — who signed a multiyear deal with Golden State in April 2026 after six seasons with the Seattle Storm — averaged 15.8 points per game this season and delivered 25 points in Game 1 of the semifinal series. One win sends the franchise to its first-ever Finals.
Behind the crossover highlights and the sold-out Chase Center roars lies a financial calculation that applies far beyond professional basketball. Williams, like tens of millions of performance-driven earners across the U.S., is navigating something deceptively complicated: a sudden, unplanned windfall arriving at the worst possible moment on the tax calendar.
How WNBA Playoff Bonuses Actually Work
The 2024 WNBA Collective Bargaining Agreement restructured playoff compensation for the first time in nearly a decade. Under the new CBA, championship bonuses are split across the winning roster: the Finals champion shares a $1 million pool, with starter-level athletes like Williams typically receiving between $60,000 and $85,000 depending on games played and performance-based escalators.
Even reaching the Finals without winning triggers a $450,000 runner-up pool, translating to roughly $30,000 to $45,000 per key player. Semifinal exits pay significantly less — the losers' pool is $150,000 total — but every dollar still lands as supplemental W-2 wage income in Q4, subject to a 22% federal flat withholding rate that nearly always under-withholds for high earners.
The timing matters. October is the worst possible month to receive a large bonus with no planning in place. The fourth quarter is when estimated tax deadlines, annual contribution limits, and charitable giving strategies all converge — and the athletes and professionals who capitalize on those windows are the ones who planned before the windfall arrived.
Why High Earners Get This Wrong
Williams' story illustrates a phenomenon wealth planners call "income acceleration": a structured compensation plan that suddenly generates more money than projected, faster than tax infrastructure can absorb it.
According to FINRA's investor education resources, high-earning athletes are among the most financially vulnerable professionals in America — not because they lack financial aptitude, but because their income is irregular, geographically distributed, and time-compressed in ways that standard financial planning models don't anticipate.
Williams has navigated this complexity for years. She played in France's EuroLeague Pro A through the 2025-26 season, where French income tax obligations ran parallel to her U.S. filings. With her new multiyear Valkyries contract, she is now primarily U.S.-based — but the complexity of blended income streams doesn't disappear. The crossover point between European league earnings, WNBA salary, and endorsement revenue creates a filing picture that surprises even sophisticated earners.
For the millions of American workers who earn more than 30% of their total income through bonuses, commissions, or performance pay, the dynamics are identical. The bracket is different. The trap is the same.
The Q4 Bonus Trap: How $75,000 Becomes a Liability
The IRS taxes supplemental wages — bonuses, commissions, and performance pay — at a flat 22% withholding rate for amounts under $1 million. For a WNBA All-Star earning a base salary near the 2026 maximum of approximately $242,000 under the CBA, a $75,000 playoff bonus pushes total earned income to $317,000. At that income level, the effective marginal federal rate is 32% — not 22%.
The 10-percentage-point gap between withholding and actual liability means that on a $75,000 bonus, approximately $7,500 slips through the withholding system untouched. Add California state income tax at 9.3% for Williams' Bay Area franchise, and the unfunded liability climbs to around $14,750.
Without proactive planning before the bonus posts to her W-2, a $75,000 playoff check generates a five-figure surprise tax bill in April — often arriving in a month when athletes are navigating contract renewals and cash flow is at its seasonal low.
A Concrete Case: What This Looks Like Away From the Arena
Consider Jordan, a 31-year-old enterprise sales manager in Austin, Texas. Jordan's base salary is $110,000, and a major Q4 deal closure just triggered a $65,000 performance bonus — unexpected until mid-September when the pipeline finally converted.
Jordan's total 2026 W-2 income is now $175,000. Her employer withholds 22% on the bonus ($14,300), leaving $50,700 in hand. She moves it to a high-yield savings account and moves on.
Here is the problem. At $175,000 in gross income as a single filer, Jordan's marginal federal rate is 32%. The bonus alone creates $10,400 in federal under-withholding — $10,400 the 22% flat rate never captured. Texas has no state income tax, but Jordan still faces federal estimated tax obligations. If she does not make an additional Q4 payment by January 15, the IRS assesses an underpayment penalty on the shortfall, calculated at the current federal short-term rate plus three percentage points.
If Jordan does nothing before December 31: She owes approximately $10,400 in additional federal taxes at filing, plus an underpayment penalty of roughly $415 on the Q4 shortfall.
If Jordan spends 90 minutes with a Wealth Management advisor before December 31: She learns she can contribute $23,500 to her 401(k) (the 2026 employee contribution limit), reducing her taxable bonus income by the full amount. She can also fund a $7,000 traditional IRA contribution and time a $3,000 donor-advised fund contribution against the bonus before year-end.
Total pre-tax deferrals available to Jordan: $33,500. Federal tax savings on those dollars at her 32% marginal rate: $10,720. Typical cost of a flat-fee advisory session: $200 to $400.
Net financial advantage of a single 90-minute consultation: approximately $10,320 — before accounting for the avoided underpayment penalty and the long-term compound growth on deferred dollars.
The math scales proportionally whether the windfall is a WNBA Finals check, a Q4 sales commission, or a year-end corporate bonus. The window to act is always Q4. The deadline to maximize deferrals is always December 31.
What to Do Before the Check Clears
The steps a wealth advisor walks through are consistent across income types and industries:
Calculate your actual marginal rate first. Your employer's 22% withholding on bonus income is a floor, not a final figure. Add your base income and your expected variable pay; find the IRS tax bracket where the total lands. The difference between the withholding rate and your bracket rate is your exposure.
Maximize pre-tax deferrals before year-end. The 2026 employee 401(k) contribution limit is $23,500, rising to $31,000 for workers aged 50 and above. Every dollar contributed reduces the bonus's taxable footprint immediately.
Evaluate a traditional IRA contribution. For earners under the income phase-out thresholds, a $7,000 traditional IRA contribution (2026 limit) provides a direct deduction against the bonus income.
Consider timing charitable contributions strategically. Donor-advised funds allow multi-year charitable giving to be bunched into a single calendar year, generating a large itemized deduction against peak-income years. A $5,000 to $10,000 contribution before December 31 can meaningfully reduce the bonus's net tax cost.
File a Q4 estimated tax payment if necessary. If your bonus arrives after Q3 and pushes you into under-withholding territory, a quarterly estimated payment by January 15 eliminates the penalty entirely. An advisor can calculate the precise figure in under an hour.
The structural difference between athletes who build lasting wealth and those who face financial difficulty after their careers is not talent level or contract size — it is access to professional planning during the moments when unexpected income arrives. Gabby Williams' WNBA Finals push is one of those moments. For performance-based earners watching from home with a Q4 bonus on the horizon, it is a well-timed reminder that the check is not the finish line.
This article is for informational purposes only and does not constitute tax or financial advice. Consult a licensed financial advisor and tax professional for guidance specific to your situation.
For a deeper look at how the WNBA's new CBA affects athlete compensation structures, see our analysis of what the WNBA's $7M salary cap means for financial planning.
