 Jessica Johnson
When Station 42's crews rushed to rescue trapped residents from a sinkhole that opened beneath Edgewater's Main Street during Founders' Day celebrations on October 9, 2026, Fire Country's Season 5 premiere delivered exactly the chaos that has made the CBS drama a Friday-night staple. But the scene also mirrors a danger most American homeowners never see coming: their standard home insurance policy won't pay for any of it.
The Gap Between TV Disaster and Real Disaster Coverage
Fire Country has built its storytelling around the unpredictability of natural catastrophes — dam failures, wildfires, and now a catastrophic sinkhole opening under a populated town center. What the show dramatizes in 45 minutes can take homeowners years to unravel through insurance claims.
According to a Federal Reserve Bank of Philadelphia analysis, an estimated 70% of expected annual flood losses in single-family U.S. residences will go uninsured. This is not because Americans don't care about their homes — it's because they assume their existing homeowner's policy already covers them.
It does not.
A standard homeowner's insurance policy — the one almost every mortgage lender requires — explicitly excludes damage caused by flooding, surface water, or groundwater intrusion. This exclusion applies whether the water came from a burst river, a dam collapse, or a sinkhole-triggered inundation. According to FEMA, only about 4% of American homeowners carry a separate flood insurance policy through the National Flood Insurance Program (NFIP), the federal backstop it administers.
For many, the discovery comes too late.
What Flood Insurance Actually Covers — and What It Doesn't
The National Flood Insurance Program sets firm limits that even policyholders often misunderstand. The maximum NFIP coverage is $250,000 for building structure damage and $100,000 for personal contents. For a home worth $380,000 in the Sacramento Valley or $500,000 in coastal Florida, those caps leave a significant gap. The exclusions cut even deeper.
NFIP policies do not cover:
- Temporary housing or additional living expenses while your home is repaired
- Mold or moisture damage not directly caused by the covered flood event
- Currency, precious metals, or valuable documents
- Vehicles (those require separate comprehensive auto coverage)
- Property outside the building footprint: fences, pools, landscaping
A 2025 Federal Reserve study found that 23% of underinsured homeowners already carried the maximum allowable NFIP coverage and still faced large out-of-pocket costs after a flood event. The coverage gap persists even for those who did the right thing and purchased flood insurance.
Then there is timing. The NFIP enforces a 30-day waiting period before a new flood policy takes effect. If a homeowner in a town like Edgewater sees a weather system moving in and tries to buy a policy on a Tuesday, they will not be covered when the ground gives way the following Saturday.
Similar blind spots appear in how fire damage intersects with water damage from firefighting efforts — something the legal experts behind Joe Miñoso's Chicago Fire departure case have also noted when examining occupational injury claims that overlap with property damage disputes.
When Your Claim Is Denied: Legal Rights You Didn't Know You Had
When a disaster strikes and an insurance carrier denies a flood or sinkhole claim — or offers a payout far below repair costs — many homeowners assume the answer is final. It rarely is.
In most states, homeowners have the right to a comprehensive review of any denied claim. This includes demanding the insurer's written explanation and the specific policy language it relied upon. A public adjuster can reassess damage independently. But if the denial involves a coverage dispute rather than a valuation dispute, an attorney specializing in insurance bad faith becomes the more powerful tool.
The legal theory of "insurance bad faith" holds that an insurer has an implied duty of good faith and fair dealing when processing claims. When a carrier delays unreasonably, lowballs a settlement, or misrepresents policy terms — for example, by classifying flood-related structural damage as "settling" (generally covered) rather than "flood" (often excluded) — a policyholder may have grounds for a bad faith claim.
In some states, a successful bad faith claim allows recovery of the original claim amount, plus attorney fees and punitive damages. That changes the cost-benefit calculation of pursuing a denied claim significantly.
Homeowners also retain important rights under FEMA's Individual Assistance program. It can provide additional support for uninsured or underinsured disaster losses even when private insurance falls short. Understanding which programs apply — and in what sequence — is where a single legal consultation often pays for itself many times over.
The Homeowner Who Lost $87,000 — and How It Could Have Gone Differently
Consider Marcus, a 44-year-old homeowner in a Sacramento Valley suburb who bought his home for $420,000 in 2023. His mortgage lender required standard homeowner's insurance, which he maintained. His property sat just outside a FEMA-designated Special Flood Hazard Area, so no one required him to purchase a separate flood policy.
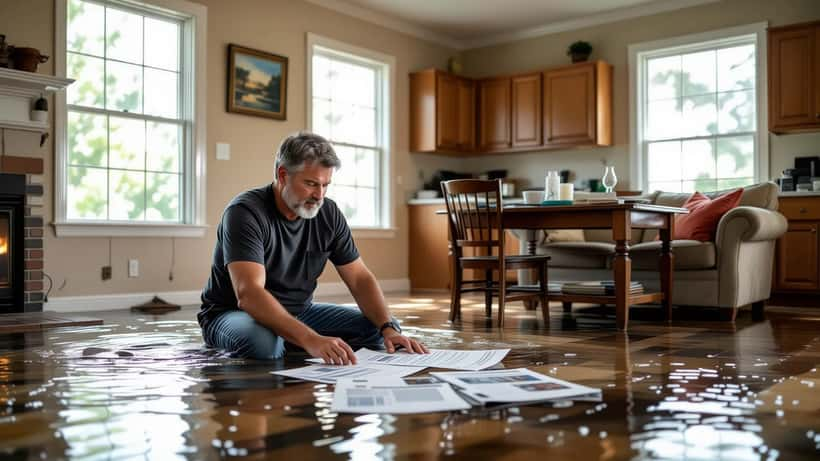
In September 2026, regional flooding caused by upstream infrastructure damage — the kind of event Fire Country depicts week after week — sent water into Marcus's basement and first floor. His damage assessment totaled $87,000, covering structural repairs, flooring, drywall replacement, and HVAC.
Scenario A — No flood insurance, no legal help: Marcus files with his standard homeowner's carrier. The claim is correctly denied: flooding is an excluded peril. He contacts FEMA, which provides $14,700 in Individual Assistance — near the program's average residential grant cap. He pays the remaining $72,300 out of pocket.
Scenario B — NFIP policy in place, purchased before the 30-day window: If Marcus had purchased an NFIP policy at the average premium of approximately $1,000 per year before any storm warning was issued, the $87,000 claim would have been largely covered up to the $250,000 building limit. His out-of-pocket cost drops to roughly $2,000 in deductibles and a few uncovered items. Annual cost of the policy: $1,000. First-year net benefit over Scenario A: approximately $70,000.
Scenario C — No flood insurance, but legal consultation within 60 days: Marcus's attorney reviews the denial and finds that 30% of the damage — water intrusion through compromised foundation joints — was arguably a covered "sudden and accidental" event rather than a flood exclusion. After a formal demand letter and a 60-day negotiation, the carrier settles for $26,100 on that portion. Attorney fees on contingency (15%): $3,915. Marcus recovers $22,185 net from the insurer, plus $14,700 in FEMA assistance. Total recovery: $36,885 — versus $14,700 in Scenario A. The difference from one consultation: $22,185.
The math is straightforward: the most expensive option is to own a home in a flood-risk area, carry no flood insurance, and never call a lawyer.
What to Do Before the Next Sinkhole Opens
The most actionable response to Fire Country's disaster storyline — and to the real risk data behind it — is a two-step check that takes less than one hour.
Check your actual flood risk, not just your FEMA zone. FEMA's flood maps show Special Flood Hazard Areas, but they update infrequently and don't account for aging infrastructure, subsidence risk, or the increasing frequency of flooding outside historically high-risk zones. Private risk tools such as the First Street Foundation's property-level flood scoring provide more current assessments.
Act on insurance before any weather event is in the forecast. Once a named storm is being tracked or a local weather advisory is issued, many private flood insurers suspend new policy applications immediately. The NFIP imposes a hard 30-day waiting period in most circumstances. If you want coverage, the time to buy it is a calm Tuesday in October — not the Friday when the ground starts shifting.
If disaster has already struck and your claim has been denied or undervalued, an insurance attorney can typically review your denial letter in a single consultation and identify whether the insurer's position holds up against the actual policy language. In states where flood and sinkhole events are increasingly frequent — California, Florida, Texas, Louisiana — the legal infrastructure for challenging bad-faith denials is well established and actively used.
Fire Country makes for compelling television precisely because its disasters feel just real enough. The sinkhole under Main Street, the dam collapse, the flooding that spills into people's living rooms — these are not purely fictional events. They are the scenarios that insurance attorneys navigate every hurricane season, every spring thaw, every year that infrastructure ages without replacement. The show never answers what happens to the homeowners after the cameras leave. That answer depends almost entirely on whether they called their lawyer.
This article provides general legal and financial information only. Individual situations vary. Consult a licensed insurance attorney or financial advisor for advice specific to your circumstances.
