 Harper Brooks
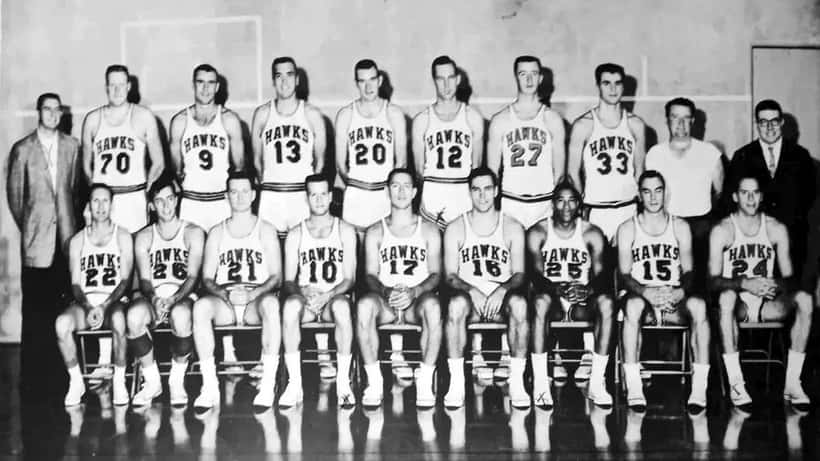
Bob Pettit, the St. Louis Hawks forward who became the NBA's first two-time Most Valuable Player, died on September 24, 2026, at age 93. Over 11 seasons — from 1954 to 1965 — he averaged 26.4 points and 16.2 rebounds per game, numbers that would command a $40 million-per-year contract in today's NBA. His actual peak salary was reportedly around $40,000 a year. The arithmetic of that gap is not just a historical curiosity — it is a financial lesson wealth advisors wish more Americans would internalize before their own peak earning years are over.
The Greatest Forward of His Era — and What He Earned Doing It
Bob Pettit did things on a basketball court that no one had done before. He was the first player in NBA history to score 20,000 career points. He led the St. Louis Hawks to four NBA Finals appearances and one championship — in 1958 — delivering one of the most celebrated individual performances in Finals history: 50 points in the deciding Game 6 against the Boston Celtics. He won the league's MVP award in 1956 and 1959, becoming the first player ever to claim it twice. When he retired in 1965, every major statistical category he touched set a new benchmark for what a power forward could do.
None of that translated into generational wealth by modern standards. In the 1950s and early 1960s, the NBA was a regional league with modest television rights and no global brand. The league average salary hovered between $8,000 and $15,000 per year. Stars like Pettit earned roughly two to three times that — likely under $50,000 per season at his absolute peak, according to historical sports economics analysis. Adjusted for inflation, that peak season was worth approximately $450,000 in 2026 dollars. That is real money — but not the kind that builds multigenerational wealth or sustains a 28-year retirement.
By contrast, the NBA minimum salary in the 2025–26 season exceeded $1.1 million. Supermax contracts for players of Pettit's caliber would now approach $60 million per year before endorsements.
What a Wealth Advisor Reads Into That Gap
The lesson financial experts draw from players like Bob Pettit is not that the old era was unfair — though structurally it was. The lesson is about time. Peak earning years are always finite, and the tools available today for converting those years into lasting financial security are more powerful and more accessible than at any point in history.
"The professionals who struggle in retirement are almost always the ones who treated peak income as permanent income," one certified financial planner recently explained. "Bob Pettit played 11 seasons. A surgeon might have 20 years at peak billing. A skilled contractor might have 12 good years before injury or market change. The number is always different. The structure of the problem is always the same: you are in a window, and the window closes."
Tax-advantaged retirement vehicles that are now standard — Roth IRAs, 401(k)s, SEP-IRAs for the self-employed — did not exist during Pettit's playing days. The Employee Retirement Income Security Act (ERISA), which created the modern framework for private pensions and retirement accounts, was not signed until 1974, nine years after Pettit's retirement. Many athletes and workers of his generation had no structured mechanism to defer income for tax-advantaged compounding growth. What feels routine today — contributing to a Roth IRA, maximizing a 401(k) match, setting up an SEP — was not available to them.
The IRS publishes a comprehensive guide to retirement plan options for individuals, employees, and small-business owners, updated annually with current contribution limits.
A Concrete Starting Point: Running the Actual Numbers
Take a professional earning $80,000 per year — the rough inflation-adjusted equivalent of what a top NBA player earned around 1960. That figure is also near the median household income in the United States today, making it a useful anchor for a real-world illustration.
The scenario: A licensed physical therapist, age 35, earns $80,000 gross annually and is just starting to think seriously about retirement. She contributes 15% of her income — $12,000 per year — to a diversified portfolio with a historical average return of 7% after inflation. At age 65, that portfolio is projected to reach approximately $1.13 million.
Now change one variable: she delays starting by 10 years, beginning at 45 instead of 35. Same annual contribution. Same investment return. Different result: approximately $565,000 at retirement — barely half the first scenario, despite saving for the same 30-year term.
If/then: If she starts at 35, $12,000 per year is enough to reach $1.1 million by 65. If she waits until 45, she would need to contribute roughly $24,000 per year — double the annual amount — to reach the same balance. At $80,000 gross, after taxes and living expenses, $24,000 in annual retirement contributions is effectively out of reach for most households.
Bob Pettit had no retirement savings infrastructure to plug into. The 35-year-old physical therapist has every one of these tools available — but only if she uses them now, not in the decade her schedule frees up.
Three Decisions That Determine Retirement Outcomes
Wealth management specialists who work with mid-income professionals consistently identify the same inflection points:
1. Starting age. Every year of delay between ages 30 and 45 reduces the eventual portfolio by roughly 4–6%, due to the non-linear nature of compounding. A 10-year delay does not cost 25% of the final portfolio — it costs approximately 50%. The math is permanently asymmetric.
2. Asset allocation. Holding retirement savings in a traditional savings account rather than a diversified investment portfolio is among the most common and most costly errors advisors encounter. At a 2% savings rate, $12,000 per year over 30 years yields approximately $490,000. At a 7% investment return, it yields $1.13 million. The same dollar amount, the same timeline, a $640,000 difference — driven entirely by where the money is held.
3. Fee awareness. A 1% annual management fee on a $500,000 portfolio costs approximately $100,000 in lost compounding over 20 years. Advisors who operate under a fiduciary standard — legally required to place the client's interest above their own — are a meaningfully different product from commission-based brokers. Asking whether an advisor is a fiduciary before signing a contract is one of the most valuable questions a new client can ask.
None of these decisions requires a professional athlete's salary or an advanced finance degree. They require honest information and a timely conversation with someone qualified to run the numbers against your specific situation.
The Longevity Premium Nobody Plans For
Bob Pettit's death at 93 is, among other things, a reminder of what modern longevity means financially. He lived 28 years beyond the traditional U.S. retirement age of 65. The average American retiring today at 65 has a life expectancy of approximately 84 to 86, according to Social Security Administration projections — a 20-year runway. But a meaningful share will live to 90 or beyond, as Pettit did.
Standard retirement planning models frequently assume a 20- to 25-year drawdown period. A retirement that lasts 28 years — Pettit's post-65 lifespan — requires 15 to 40% more in assets than most projections target. Healthcare costs alone in the final decade of a long life can exceed $200,000 in out-of-pocket expenses even with Medicare coverage.
That mismatch between planning assumptions and actual longevity is precisely why wealth advisors recommend reviewing a retirement plan every three to five years — and more frequently after any major life change: a job transition, a health diagnosis, an inheritance, or a market correction that materially alters the portfolio's trajectory.
Financial Disclaimer: The projections in this article use historical averages for illustrative purposes only. Actual investment returns vary and are not guaranteed. Consult a qualified financial advisor before making retirement investment decisions.
What to Do Now
Bob Pettit built his legacy through 11 seasons of exceptional discipline and thousands of hours of preparation. Building financial resilience in 2026 demands far less raw effort — but it demands beginning earlier than most people do and seeking guidance from someone who understands the full picture.
Expert Zoom connects individuals, contractors, and small-business owners with certified wealth management advisors who specialize in retirement planning, tax-efficient savings strategies, and estate structuring. You do not need significant existing assets to benefit from an initial consultation — you need clarity about where you are, what the window looks like, and which tools are worth activating now.
The NBA changed the economics of basketball. The tools available for protecting your own financial future have changed too. The question Bob Pettit's story quietly asks is whether you are using them.
