 Carl Graham
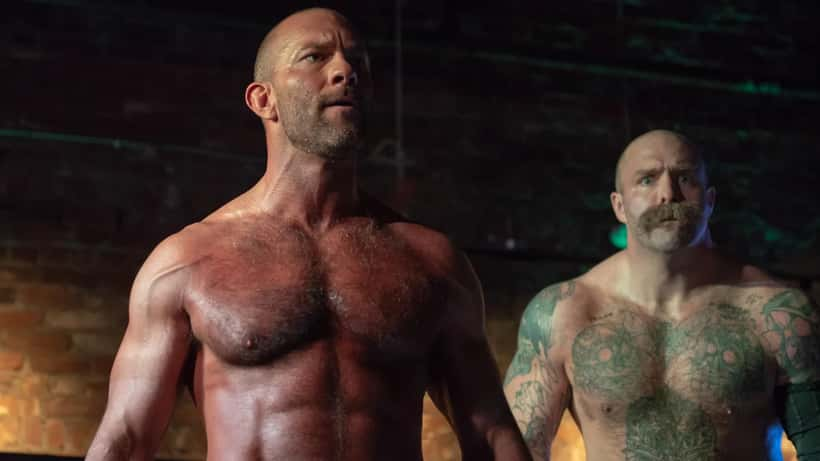
Saturday evening at Mr. Smalls Theatre in Millvale, Pennsylvania, an Enjoy Wrestling tag team match ended in tragedy. Andy Williams — known to professional wrestling fans as "The Butcher," a former AEW star and accomplished rock guitarist — collapsed near the conclusion of his bout alongside partner Jesse Guilmette ("The Blade") and never recovered. Williams was 48 years old. Medics on site administered CPR, paramedics deployed a defibrillator, and an ambulance rushed him from the venue, but he died that night. A cause of death has not yet been announced.
The tributes from AEW, from indie promotions, from fans around the world have poured in swiftly. But as the initial wave of shock fades, a harder set of questions begins to surface — questions that every professional wrestler, event promoter, and entertainment-industry worker should be asking right now.
The Legal Limbo Most Wrestlers Don't Know They're In
Andy Williams, like the vast majority of working professional wrestlers in the United States, was almost certainly classified as an independent contractor — not an employee. That classification shapes everything that happens next for his family, and it exposes a legal gap that is larger than most performers realize.
Under U.S. labor law, employees whose workplace deaths are caused by on-the-job conditions are covered by workers' compensation death benefits — a structured payout system that provides families with income replacement, funeral costs, and ongoing support regardless of fault. Independent contractors receive none of this by default. Pennsylvania's Workers' Compensation Act explicitly limits coverage to employees; promoters who classify wrestlers as ICs have no legal obligation to carry workers' comp on their behalf.
This is not a technicality. It means that when a wrestler collapses during a match, his family's legal options are dramatically different depending on a piece of paper — the independent contractor agreement — that most wrestlers sign without fully understanding its implications.
The U.S. Department of Labor's independent contractor rule, updated in January 2024, established a six-factor economic reality test for determining whether a worker is truly independent or functionally an employee. The rule has reshaped liability in industries from rideshare to healthcare — but its application in professional wrestling, where promoters routinely set match outcomes, travel requirements, and appearance obligations, remains deeply inconsistent. (For the full framework, see the Department of Labor's guidance on independent contractor classification.)
What the Enjoy Wrestling Promoters May Be Responsible For
Here's where the analysis becomes genuinely urgent for promoters: even if Andy Williams was legally classified as an independent contractor, the Enjoy Wrestling organization is not necessarily shielded from all liability.
Under OSHA's General Duty Clause (29 U.S.C. §654(a)(1)), employers — and in some interpretations, venue operators controlling the work environment — must provide conditions free from recognized hazards. A professional wrestling event, by any measure, is a setting with recognized hazards. The presence of medics at the Enjoy Wrestling show suggests the promoters understood this, and rapid response may ultimately mitigate legal exposure significantly.
But "some medical presence" is not the same as adequate emergency preparedness. A critical legal question in the weeks ahead will be: Was a functioning AED (automated external defibrillator) within the federally recommended 3-to-5-minute access window? Were the medics specifically trained in cardiac emergency response? Was there a written emergency medical protocol for performer incidents?
Under Pennsylvania wrongful death law (42 Pa. C.S. § 8301), the Williams family can pursue a civil claim if they can demonstrate that the promoter, the venue, or another third party was negligent and that this negligence was a cause of death. Wrongful death in Pennsylvania allows recovery of:
- Medical and emergency response costs incurred
- Funeral and burial expenses
- Lost earning capacity over the deceased's projected working life
- Compensation for loss of companionship, guidance, and services to surviving dependents
This is a civil claim, separate from workers' comp, and it can proceed against a third-party promoter even when a workers' comp claim is unavailable. According to Pennsylvania law, these claims do not conflict with one another — they are parallel pathways.
A Concrete Scenario: Running the Numbers for a Wrestler's Family
Consider a representative indie wrestler — call him Mark — who earns $2,500 per booking and works 30 shows per year. That puts his annual gross income at approximately $75,000 before taxes, similar to the range many working indie performers in the 40-to-50 age bracket report. Like most IC wrestlers, Mark carries no employer-provided health insurance, no workers' compensation protection, and holds a $250,000 term life insurance policy he purchased independently.
If Mark dies during a match at age 48, classified as an independent contractor:
- Workers' comp claim against the promoter: Unavailable. Pennsylvania law does not extend this protection to ICs. The promoter has no policy for him.
- Term life insurance: $250,000 paid out to his named beneficiary — a one-time payment. At a typical household expenditure rate, this covers roughly three to four years of family expenses, nothing more.
- Wrongful death claim against the promoter: Potentially viable if negligence can be shown. Pennsylvania courts have used lost earning capacity as a core damages figure — in this case, $75,000 × approximately 17 remaining projected working years (to age 65) = $1.275 million in base lost earnings, before adjustments for inflation and career trajectory.
- If negligence is found: Families may additionally recover pain and suffering damages, loss of companionship, and funeral costs. Pennsylvania's Survival Act (42 Pa. C.S. § 8302) allows the estate to bring claims for losses the decedent suffered personally before death.
The critical if/then: If Enjoy Wrestling had a functioning AED accessible within five minutes AND trained emergency medical personnel (not just basic first aid) on site AND a documented emergency response protocol — the wrongful death claim becomes substantially harder to establish. If any of these elements were absent, liability exposure climbs sharply.
This calculus is not hypothetical. It will play out in real time for the Williams family in the weeks ahead, and similar calculations are happening for the families of every performer who has died or been seriously injured at a live event in recent years.
What Wrestlers Need to Do — And Why Most Haven't
The professional wrestling industry operates on a culture of toughness and risk acceptance. Asking about insurance, workers' comp, or what happens if something goes wrong is treated — still, in 2026 — as a sign of weakness or mistrust. That culture is costing people's families their financial lives.
Here is what legal and financial professionals consistently advise for any independent contractor performing in a physically demanding field:
For performers:
Term life insurance at 5–10× annual income: For a wrestler earning $75,000/year, this means $375,000 to $750,000 in coverage. Annual premiums for a healthy 40-year-old typically run $500 to $1,200/year — a manageable cost compared to the alternative.
Disability income insurance: Covers a portion of lost bookings during injury recovery. Monthly premiums for indie-income ranges typically run $150 to $400, depending on the benefit amount and waiting period.
Understand your contracts: Every independent contractor agreement you sign defines what the promoter owes you — and how little that often is. Review these with an attorney before signing, not after something goes wrong. Legal fees for a contract review are typically $200 to $500. A wrongful death lawsuit costs far more.
Request emergency protocols in writing: Before performing at an event, confirm in writing that the venue has a functioning AED, trained emergency medical staff, and a written emergency response plan. Promoters who balk at this question are telling you something important.
For promoters:
- Ensure your general liability policy includes an entertainment-specific endorsement covering performer medical emergencies — standard GL policies frequently do not
- Document your emergency preparedness procedures at every event
- Consult with an employment attorney about whether your performer classifications hold up under the 2024 DOL six-factor test — misclassification creates liability exposure beyond this specific scenario
The Larger Warning
Andy Williams was a beloved figure in professional wrestling — a performer who combined genuine athletic skill with rock 'n' roll charisma, and who gave everything he had every time he stepped through the curtain. His death is a tragedy for everyone who knew him and for the sport.
It is also a warning. Tens of thousands of independent contractors — wrestlers, musicians, comedians, circus performers, stunt professionals — take on physical risk every weekend without the legal protections that the employment system was designed to provide. The gap between "independent contractor" and "employee" is not bureaucratic paperwork. It is the difference between a family that is financially protected and a family that is left to piece together a legal case from scratch during the worst weeks of their lives.
When something goes wrong in a gig-economy setting, a lawyer who understands entertainment employment law and wrongful death litigation can be the single most important resource a family has. The statute of limitations in Pennsylvania for wrongful death claims is two years from the date of death. The clock is already running.
For the Williams family, and for every performer who steps into a ring, ring the bell on these conversations now — not after.
For wrestlers and gig-economy performers wondering how their own contracts, insurance gaps, or estate protections stack up, read how WWE's independent contractor model creates legal blind spots — and what happened when another performer faced the insurance gap that independent contractors inherit by default.
Legal and financial disclaimer: This article is for informational purposes only and does not constitute legal or financial advice. Workers' compensation, wrongful death, and independent contractor law vary significantly by state and individual circumstance. If you or a family member is affected by a workplace death or serious injury, consult a licensed attorney in your jurisdiction before taking any legal action.
