 Michael Campbell
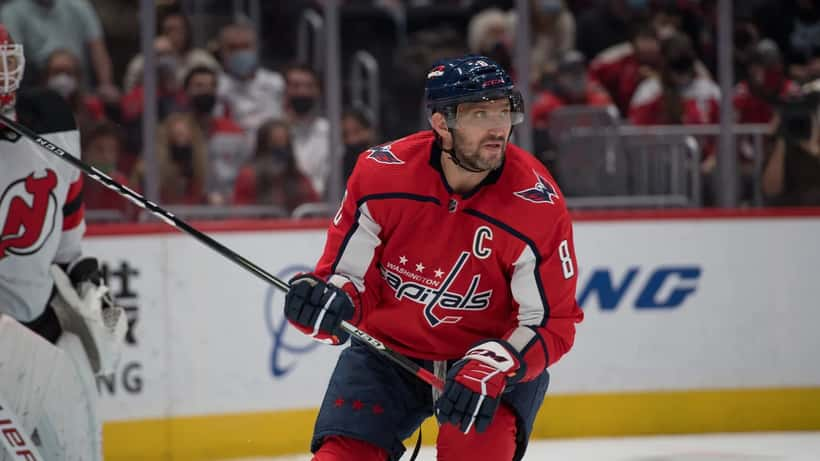
Alex Ovechkin made one of the most significant announcements in NHL history on October 5, 2026, telling his Washington Capitals teammates that the 2026-27 season will mark the end of his 22-year career. At 41 years old and holding 929 career goals — a record that eclipsed Wayne Gretzky's 894-goal mark in April 2025 — Ovechkin is stepping away from professional hockey with a legacy that may never be matched.
For hockey fans, the news is bittersweet. For financial planners and wealth managers, it raises a question far more common than it might appear: what does it take to retire at 41, and what financial infrastructure must be in place before you leave your peak-earning years behind?
Why Retiring Before 50 Is an Entirely Different Problem
The traditional retirement model was built around a simple assumption: you work until 65, collect Social Security, draw down a pension, and live on roughly 70-80% of your pre-retirement income for 20-25 years.
Retiring at 41 — as Ovechkin is doing — blows that model apart. According to the Social Security Administration, the average 41-year-old American today can expect to live well into their 80s. That means Ovechkin is looking at roughly 40 years of retirement. In financial planning terms, that is not a retirement. That is a second life that requires a completely separate funding strategy.
A 40-year retirement horizon means your assets must work harder and longer than any standard retirement calculator anticipates. Inflation compounds over four decades, not two. Healthcare costs — which typically rise sharply after 65 — will arrive mid-retirement rather than at the end. And the tax environment you enter retirement in may look nothing like the one you face 20 years later.
For the millions of Americans who retire before age 50, these are not hypothetical concerns. They are the defining financial challenges of a new kind of retirement that existing tools were never built to handle.
The Peak-Earning Window Problem Every High Earner Faces
Ovechkin's career illustrates a phenomenon that financial advisors increasingly see beyond professional sports: the compressed peak-earning window.
Over 22 seasons, Ovechkin earned an estimated $140 million in NHL salary alone, with additional income from endorsements, investments, and business interests. But the critical insight is not the total figure — it is how quickly those earnings arrived and how early they must fund everything that follows.
Athletes are the most visible example, but the same dynamic plays out across sectors. A software engineer in San Francisco who peaks at $350,000 per year in their mid-30s, a hedge fund analyst who commands seven-figure compensation before 40, or a surgeon who spends a decade building a high-volume private practice — all face a version of the same equation Ovechkin does. A finite window of exceptional income must fund a retirement that could span half a century.
Research from Fidelity's 2026 Retirement Savings Assessment indicates that Americans who retire before 55 are significantly more likely to exhaust their savings by age 70 than those who retire at 65. The gap is not primarily explained by reckless spending — it is explained by a systematic underestimation of the time horizon.
The Three Wealth Management Gaps That Catch Early Retirees Off Guard
Financial advisors who specialize in early retirement consistently identify three structural gaps that derail otherwise well-funded exits.
The healthcare bridge gap. Medicare eligibility begins at 65. An early retiree must fund private health insurance coverage for 20 or more years before that safety net arrives. For a 41-year-old in good health, private marketplace coverage typically costs between $600 and $1,200 per month in 2026, depending on the plan and state. Over 24 years, that represents $173,000 to $345,000 in premiums alone — before accounting for out-of-pocket costs.
The account access gap. Standard 401(k) and IRA accounts carry a 10% early withdrawal penalty for distributions before age 59½. An early retiree who relies on these accounts too heavily must either pay the penalty, execute a Roth IRA conversion ladder, or use a 72(t) SEPP distribution. Each approach has tax implications that compound significantly over a 40-year horizon.
The Social Security optimization gap. Social Security benefits are calculated using your 35 highest-earning years. For someone who retires at 41, those 35 years will include zeros for every year from retirement until age 62. Research from the Center for Retirement Research at Boston College found that early retirees with gaps in their earnings record receive benefits averaging 18-24% lower than continuous workers with identical total lifetime earnings.
The Ovechkin Scenario: What Early Retirement Costs a High Earner at 43
Consider Marcus, a 43-year-old principal engineer at a Seattle technology company who has accumulated $3.2 million across a 401(k), a brokerage account, and a restricted stock unit portfolio. Marcus earns $310,000 per year and is planning to retire in 2027 after a major stock vesting event.
Without a wealth management plan, the picture looks straightforward: $3.2 million at a standard 4% withdrawal rate supports $128,000 annually — roughly 41% of his current income — across a 30-year retirement.
The problem is that Marcus is not facing a 30-year retirement. He is facing 40-plus years, and the numbers shift sharply under a proper early retirement analysis.
Healthcare bridge: Marcus's private insurance will cost an estimated $9,600 per year at current rates, rising to an estimated $22,000 per year by the time Medicare eligibility arrives in 2047. Modeled across 24 years with conservative premium inflation, this represents approximately $380,000 in uncaptured costs — a line item that does not appear in the standard 4% rule calculation.
Roth conversion cost: To avoid early withdrawal penalties on his $1.8M 401(k), Marcus should begin converting tranches to a Roth IRA starting now. Each conversion creates ordinary income and must be calibrated against his marginal tax rate each year. Without planning, a single-year lump conversion could push him into the 37% bracket unnecessarily, costing an additional $60,000-$90,000 in avoidable federal tax.
Social Security reduction: Marcus's 35-year earnings record will include 22 years of zeros if he retires at 43. This reduces his projected benefit from approximately $3,200/month to $2,150/month — a difference of $12,600 per year every year after he turns 62. Taken to age 85, that is over $289,000 in lost Social Security income.
If Marcus addresses all three gaps with a certified financial planner before his retirement announcement, projections show his sustainable withdrawal rising from $128,000 to approximately $152,000 annually — a difference of $24,000 per year, or roughly $960,000 over 40 years. If he ignores them, conservative analysis projects a meaningful portfolio shortfall before age 75.
The parallel to Ovechkin is direct: the best time to assemble your financial team is not the day you clear out your locker — it is several seasons before.
Note: This article is for informational purposes only and does not constitute financial advice. Individual retirement situations vary significantly. Consult a licensed financial advisor before making decisions about retirement timing, tax strategy, or withdrawal planning.
What to Do Before You Announce Your Last Season
Ovechkin spent years preparing for this transition. The decisions that will fund the next 40 years of his life were not made in October 2026 — they were made when he was still scoring 50 goals a season.
For anyone approaching a peak-earning exit — whether from a corporate role, a professional practice, or an entrepreneurial venture — the actionable steps follow the same logic.
Start your Roth conversion ladder at least five years before retirement. Each dollar converted costs ordinary income tax now, but eliminates future required minimum distributions and preserves tax-free access during retirement. The earlier you begin, the lower each year's conversion amount and the lower the marginal rate applied.
Model your true healthcare costs explicitly. Most early retirement calculations underestimate this line item by a factor of two or more. A wealth manager experienced in early retirement planning can run a detailed bridge scenario that accounts for premium inflation, out-of-pocket exposure, and the gap before Medicare.
Review your Social Security strategy before you stop earning. If your retirement will create gaps in your earnings record, you need a specific plan — either delaying claiming beyond 62 to offset the reduction, or building a separate income bridge that makes claiming at 70 financially viable. Even one or two additional earning years can meaningfully increase your lifetime benefit.
Stress-test the 4% rule against your actual horizon. The 4% withdrawal rate was derived from 30-year retirement scenarios. A 40-year horizon requires a 3.3-3.5% withdrawal rate to achieve the same statistical survival probability. Applied to a $3M portfolio, that difference — $30,000 per year — determines whether you are comfortable or constrained in your 70s and 80s.
Ovechkin's announcement is a reminder that the game ends for every high earner eventually — and the financial scoreboard that matters most is the one you never see during your playing years. ExpertZoom connects individuals planning early retirement with certified wealth management professionals who specialize in long-horizon planning, tax-efficient withdrawal design, and the structural gaps that standard retirement tools miss.
