 Olivia Tremblay
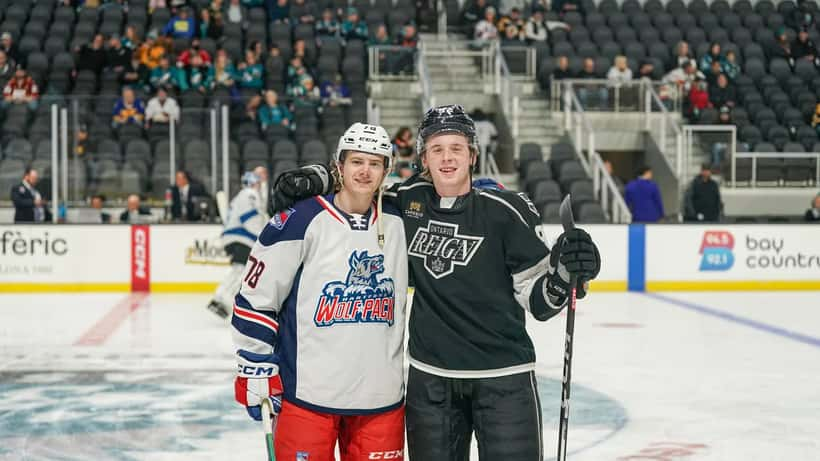
When Brandt Clarke agreed to a five-year, $37 million contract extension with the Los Angeles Kings in June 2026, the 22-year-old defenseman did more than secure his future in the NHL — he joined the small, statistically rare club of young professionals whose income shifts from promising to life-changing before they turn 25. What happens next financially can define the rest of his life, on and off the ice.
What $37 Million Actually Looks Like After Taxes and Fees
The headline number never tells the full story. Clarke's $7.4 million average annual value (AAV) is the figure that makes the sports pages. What lands in his bank account after all deductions is a fundamentally different number — and that gap is where young athletes most often get into trouble.
In California, where the Kings are based, state income tax reaches 13.3% for high earners. Add the federal rate (up to 37%), agent fees (typically 3–4% of the contract), escrow withheld under the NHL Collective Bargaining Agreement (currently 6%), and player association dues, and a $7.4 million salary can net to roughly $3.5–4 million per year in take-home pay — less than half the headline figure.
This is not unusual. Industry research widely cited by financial regulators — including the Financial Consumer Agency of Canada in its athlete financial literacy materials — estimates that a majority of professional athletes face serious financial difficulty within five years of retirement. For hockey players, whose careers average fewer than six seasons at the top level, the stakes are compressed further.
Clarke's five-year deal runs through the 2030–31 season. By the time it expires, he will be 27 — with potentially two decades of post-hockey life ahead, and significant financial decisions already locked in.
The Planning Gap That Derails Young Athletes
The critical window for financial planning is not after the contract is signed. It is during the negotiation phase — ideally 12 to 18 months before ink meets paper.
Most 22-year-olds, regardless of talent, have never managed wealth at this scale. They understand performance, competition, and sacrifice. They have spent their formative years in arenas, not financial literacy programs. The instinct is to trust the agent who negotiated the deal, the business manager a teammate recommended, or family members who have always been in their corner.
Each of those relationships can be genuine and valuable — and still be wholly inadequate for the complexity of a multi-million-dollar compensation package with cross-border tax implications, deferred compensation structures, and long-term investment planning requirements.
Clarke's contract presents specific challenges common to high-earning athletes under age 25 in North America:
- Multi-jurisdiction taxation: Players pay taxes in every city where they play an away game in the US — known as the "jock tax." This requires tracking income allocation across dozens of annual tax filings.
- Endorsement income layering: Additional commercial deals create a second income stream with different tax treatment than salary.
- Escrow unpredictability: NHL escrow rates fluctuate based on league revenue, meaning the gross number on any contract is partly theoretical until the season ends.
- Entry-level transition: Clarke transitions from a structure with lower earnings to one where a single poor financial decision — a bad real estate investment, over-leverage on a business venture, or simply not saving — can have decade-long consequences.
A certified financial planner who specializes in professional athletes is equipped to model these variables together. A generalist wealth manager with experience in public equities and retirement planning is not the same thing. Similar high-stakes contract situations — like Shane Wright's recent RFA trade scenario with the Kraken — have highlighted how multi-layered the financial and legal decisions are for young NHL players navigating major deals.
Concrete Case: What Happens When a 22-Year-Old Signs Without a Plan
Consider this scenario: a 22-year-old Canadian player — call him Marc — signs a five-year deal worth $6 million AAV with an American NHL club. He is Canadian, lives in the US during the season, and maintains a residence in Ontario for the off-season. He has an agent but no dedicated financial planner. In Year 1, he:
- Fails to file a Competent Authority agreement between Canada and the US, resulting in double taxation on approximately $400,000 of income earned during the Canadian off-season period.
- Buys a $2.2 million property in Los Angeles using a standard mortgage, without a tax advisor flagging that as a non-permanent resident, he may face additional withholding requirements on future sale proceeds under FIRPTA (Foreign Investment in Real Property Tax Act).
- Invests $500,000 in a restaurant venture recommended by a friend. Two years later, the restaurant closes. No professional had evaluated the risk profile in the context of his overall net worth or career length.
Total avoidable financial exposure in Year 1 alone: roughly $800,000 to $1.2 million — before he has turned 24. None of these outcomes required bad intentions from anyone involved. They required only the absence of the right specialist at the right time.
If Marc had engaged a wealth manager specializing in professional athletes before signing — one who coordinated with a cross-border tax attorney and reviewed his investment risk appetite against his contract length — each of those three scenarios would have been identified and mitigated during onboarding. The restaurant investment might still have happened, but at a capped exposure of 5–10% of investable assets, not a single illiquid bet.
The first contract is when habits form. Those habits are expensive to undo five years later.
What Clarke's Signing Means for Any Young High Earner
From a hockey perspective, Clarke's deal is widely regarded as excellent value for the Kings. At $7.4 million per year, the LA front office locked in a top-pairing defenseman projected for continued offensive growth at a number that looks reasonable for a player of his caliber and age.
But the contract's structure — five years, no movement clause reported — also creates a degree of geographic and financial stability unusual for an athlete his age. That stability is an asset. It means Clarke can establish a long-term financial plan without the disruption of annual relocation, which simplifies tax planning, real estate decisions, and investment structuring considerably.
For other young athletes watching this signing, the lesson is structural, not cautionary. The question is not whether you will face these decisions — you will — but whether you have the right team around you when they arrive. An agent manages the contract. A financial planner manages what the contract becomes over a lifetime.
According to data from the National Hockey League Players' Association (NHLPA), the average NHL career for players who make the league is approximately 5.5 seasons. That means the majority of contracts signed today will be among the last major compensation packages a player ever negotiates. As Mitch Marner's $96M sign-and-trade deal showed this past offseason, the biggest deals in the sport still require expert navigation on both the legal and financial sides.
The five-year deal that looks like the beginning often is, in financial terms, the middle.
What to Do After a Major Contract Is Signed
Whether you are an NHL player, a young executive receiving equity vesting, or a professional earning significantly more at 25 than you expected to at 35, the playbook is the same.
In the first 90 days after signing:
- Engage a fee-only financial planner — someone compensated by flat fee or hourly rate, not commission on products they sell you.
- Conduct a full cross-border tax assessment if you work in more than one jurisdiction.
- Freeze major illiquid investment decisions (real estate, business ventures) until a financial plan is in place.
- Set a savings rate before setting a lifestyle. Reverse-engineering a budget from lifestyle expectations is one of the most common and destructive patterns in athlete finance.
In the first year:
- Build an emergency reserve of 18–24 months of living expenses in liquid assets. Career-ending injuries happen. Escrow clawbacks do too.
- Begin long-term investing through tax-advantaged accounts where eligible (RRSP for Canadians, IRA structures for US-based earners).
- Review beneficiary designations and basic estate planning. These are not morbid concerns at 22 — they are foundational.
The opportunity that Brandt Clarke's contract represents extends beyond hockey. Any young professional entering a major earnings phase faces the same variables, compressed into a smaller window than they realize. Getting the right advice at the right moment is not a luxury item. At $37 million, it is the most cost-effective decision in the contract.
This article discusses general financial planning concepts and does not constitute personalized financial or legal advice. Individual circumstances vary. Consulting a licensed wealth management professional is advisable for guidance tailored to your situation.
