 John Green
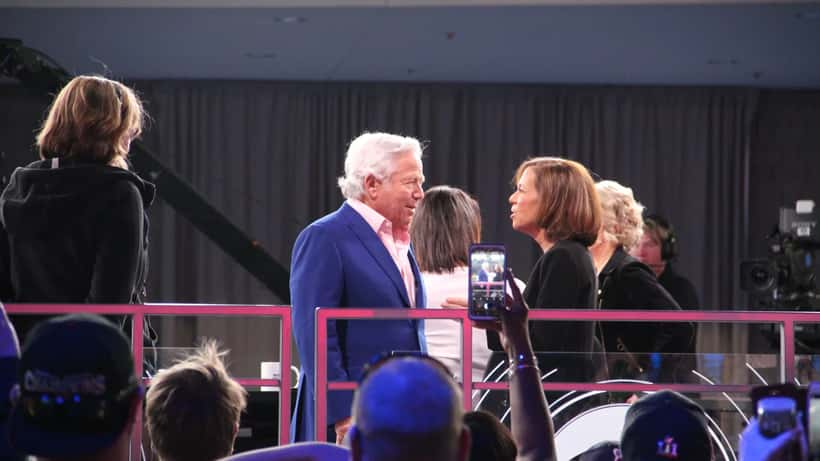
When New England Patriots owner Robert Kraft chose not only to match but to double rapper Macklemore's $1 million donation to Palestinian humanitarian relief on 16 September 2026, the internet reacted with surprise. Financial planners were not surprised at all. Matching gifts are one of the most powerful tools in the philanthropist's playbook, and they are available to ordinary UK donors — not just billionaires. Here is what the Kraft story can teach anyone who gives to charity.
The Donation That Made Headlines
Macklemore — who had controversially been barred from performing at Kraft's Gillette Stadium in Boston — publicly challenged the Patriots billionaire to match his $1 million donation to Palestinian humanitarian relief. Kraft's response was swift and larger than expected: he did not just match it; he committed $2 million, doubling the original pledge. That gesture followed a separate arrangement brokered with musician Ed Sheeran, who also pledged $2 million to the same humanitarian cause. Kraft matched that commitment too, bringing the total donations linked directly to his actions to $4 million in under a week.
The story circulated widely, partly because of the underlying tension — Kraft is a prominent Jewish philanthropist publicly aligning with Palestinian relief efforts — but also because of the sheer speed and scale of the giving. For wealth advisers watching from Britain, however, the more instructive story is how such donations are typically structured, and why matching gift mechanics matter far beyond billionaire circles.
Why Billionaires Use Matching Gifts — And Why UK Donors Should Too
Matching gifts are not simply good optics. They are a proven mechanism for multiplying charitable impact while also maximising tax efficiency. Robert Kraft's family office operates through a Donor-Advised Fund (DAF) structure common in the United States, which allows large gifts to be staged and deployed strategically over time. The UK equivalent exists — and is used by a fraction of the people who would benefit from it.
A UK Donor-Advised Fund, offered by organisations such as CAF (the Charities Aid Foundation) or Charities Trust, allows a donor to make a lump-sum contribution into a tax-efficient account, claim immediate Gift Aid and income tax relief, and then distribute funds to any registered charity over months or years at the donor's discretion. You retain control over timing; HMRC contributes on your behalf from day one.
According to HM Revenue & Customs, Gift Aid allows registered charities to reclaim an additional 25p for every £1 donated — at no extra cost to the donor. For higher-rate taxpayers earning above £50,270 in the 2026/27 tax year, the benefit is greater still: they can reclaim the difference between the basic and higher rate of tax through their Self-Assessment return, reducing the real cost of a £1,000 donation to just £600.
These are not obscure loopholes. They are government-backed incentives designed specifically to encourage charitable giving — and most UK donors are not using them to their full potential.
The Expert Angle: Strategic Philanthropy Is Not Just for Billionaires
Wealth managers identify three core mechanisms that explain how donors like Kraft structure transformative giving, each of which has a direct UK equivalent.
Bunching donations means concentrating several years of charitable giving into a single high-income tax year rather than spreading small amounts annually. This is especially effective for self-employed professionals, executives receiving a bonus, or anyone who has sold an asset. By bunching five years of planned giving into one tax year, a donor can claim maximum relief in a year when they have the highest marginal tax rate.
Donating appreciated assets rather than cash is legal in the UK and significantly more efficient than writing a cheque. If you donate shares listed on a UK or foreign stock exchange directly to a registered charity, you pay no Capital Gains Tax on any gain in the share value, and you receive income tax relief on the full current market value of the shares. For a higher-rate taxpayer donating shares bought for £2,000 now worth £10,000, the total tax benefit — CGT saved plus income tax relief — can exceed £6,000 on a single transaction.
Payroll giving (also known as Give As You Earn) allows employed donors to make contributions from gross salary before income tax is deducted. A basic-rate taxpayer giving £100 per month pays just £80; a higher-rate taxpayer pays just £60. The charity receives the full £100 in every case. For people with steady employment, this is the simplest mechanism available, and many employers will match payroll donations pound-for-pound — effectively doubling charitable output without any extra spending.
A qualified wealth management adviser with expertise in tax planning and philanthropy can identify which of these mechanisms fits a client's specific situation, often unlocking thousands of pounds of additional giving capacity within existing budgets. An article on related wealth planning strategies from our Cody Gakpo wealth management guide illustrates how high earners structure financial decisions more broadly.
When £5,000 Becomes £12,500: A UK Scenario
Consider a 43-year-old marketing director based in Manchester, earning £78,000 in the 2026/27 tax year. The Kraft donation story prompts her to act on a long-standing intention to give meaningfully to a registered humanitarian relief charity. She plans to donate £5,000.
If she donates £5,000 in cash with Gift Aid: The charity reclaims £1,250 from HMRC at 25%, receiving £6,250 in total. She claims higher-rate relief of £1,250 on her Self-Assessment return. Her actual out-of-pocket cost: £3,750 to deliver £6,250 to the charity — a leverage ratio of 1.67:1.
If, instead, she donates shares currently worth £5,000 that she originally bought for £1,500: She avoids CGT on the £3,500 gain (saving up to £840 at 24% higher rate). She also receives income tax relief at 40% on the £5,000 market value, worth £2,000. Her total benefit reaches £2,840, reducing her effective cost to roughly £2,160 while delivering the full £5,000 market value to the charity.
If she also activates a 1:1 employer donation match — a scheme offered by many large UK corporations and public sector bodies that most employees never activate — the story changes again. Her £3,750 out-of-pocket cash donation now generates:
- £5,000 received by the charity directly
- £1,250 from HMRC via Gift Aid
- £5,000 matched by her employer
- £1,250 Gift Aid claimed by the charity on the employer match (if eligible)
Total reaching the charity: up to £12,500, at a personal cost of £3,750. That is a 3.3:1 leverage ratio, achieved through standard mechanisms that require no investment vehicle, no trust structure, and no financial sophistication beyond one conversation with a qualified adviser.
The difference between an uninformed donation and a strategically structured one in this scenario exceeds £8,750 in charitable impact — without spending a single pound more.
What the Kraft Moment Tells Us About the UK Giving Gap
The Robert Kraft-Macklemore story is not just celebrity drama. It is a signpost about how public matching challenges work at every level. Research published by the Charities Aid Foundation found that matching gift campaigns increase total donations by an average of 19% compared to equivalent non-matched appeals, and that they consistently attract first-time donors who would not have acted without the visible social momentum.
For the UK, this matters. Charitable giving as a share of household income has been declining since 2019. High inflation years reduced discretionary giving further. Yet the structural mechanisms to make existing giving far more efficient — Gift Aid, DAFs, payroll giving, asset donations, employer matching — remain in place and are largely unused.
Robert Kraft did not give $4 million this week because he discovered a new motivation. He acted quickly, at scale, because he has the infrastructure and the advice to do so. UK donors at every income level can build a proportionate version of that infrastructure. A conversation with a wealth management expert is where that process starts.
What to Do Now
If the Kraft donation story has prompted you to reconsider how you give, the most useful immediate step is not to make a donation — it is to schedule a review of your giving strategy with a qualified financial adviser who specialises in tax-efficient philanthropy.
Questions to raise in that conversation: Am I claiming higher-rate Gift Aid relief I am entitled to? Does my employer offer donation matching? Would donating shares rather than cash make sense given my current portfolio? Is a Donor-Advised Fund appropriate for my situation? Would bunching multiple years of charitable giving into this tax year reduce my overall tax bill?
These are not complicated questions. The answers can make an extraordinary difference to how much reaches the causes you care about — and how much remains in your pocket.
Disclaimer: This article is for informational purposes only and does not constitute financial or tax advice. Tax rules are subject to change and individual circumstances vary. Please consult a qualified, regulated financial adviser before making charitable giving or tax planning decisions.
