 John Green
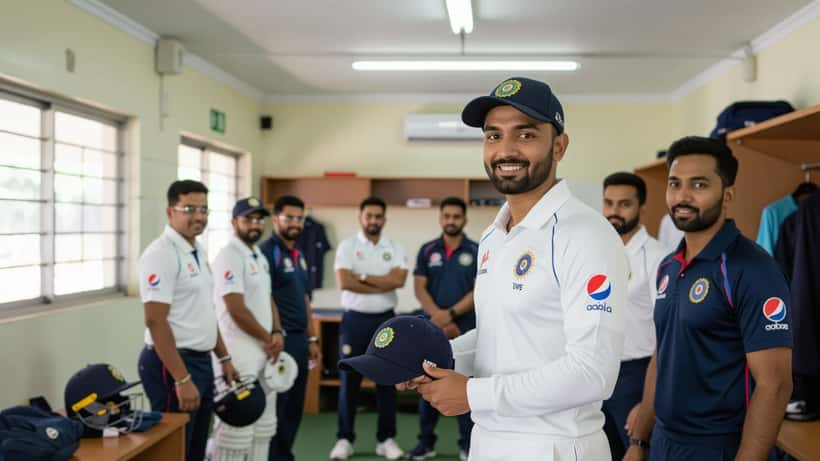
When Shubman Gill placed the India cap on Naman Dhir's head at Thiruvananthapuram's Greenfield International Stadium on 27 September 2026, the 26-year-old from Ambala, Haryana became India's 264th men's ODI cricketer. "I got to know yesterday that I'll be making my debut," Dhir said after receiving the cap. "It was a little difficult to sleep at night, obviously." What Dhir may not have anticipated losing sleep over is the financial complexity that accompanies his meteoric career arc — a story with striking parallels for British South Asian professionals navigating sudden income growth.
From ₹20 Lakh to ₹5.25 Crore: Cricket's Fastest Pay Jump
The arithmetic of Dhir's IPL career is staggering. In November 2024, Mumbai Indians bought him at his base price of ₹20 lakh — approximately £18,600 at prevailing exchange rates — a modest starting point for an uncapped domestic player from Haryana. Twelve months later, at the IPL 2025 mega-auction, MI triggered the right-to-match (RTM) clause to retain him for ₹5.25 crore, roughly £492,000. That is a 26-fold increase in a single contract cycle.
His performances justified every rupee. In the 2025 IPL season, Dhir accumulated 252 runs at a strike rate of 182.61, cementing his role as one of the franchise's most destructive finishers. His 24-ball 46 against Lucknow Super Giants in 2024 had already signalled his capability under pressure. The ODI call-up — selected by head coach Gautam Gambhir to fill the all-round gap created by Washington Sundar's absence for the Asian Games in Japan — confirmed he had crossed the threshold from domestic talent to international commodity.
The cricketing progression is clear. The financial journey, however, is a different story entirely — and for the millions of UK cricket followers who watched his debut, a surprisingly instructive one.
Why International Debuts Trigger a Wealth Planning Emergency
Dhir's income stream, like that of most elite South Asian cricketers, now includes multiple simultaneous layers: an IPL franchise retainer, BCCI centrally contracted fees, match fees for each India appearance, and what will rapidly become a pipeline of endorsement and image rights deals. According to the ICC's player payment framework, a full India international can expect match fees to add a further ₹15 lakh (approximately £14,000) per ODI to their earnings — on top of existing contracts.
Each income stream carries different tax treatment under Indian law. For any player who holds UK tax residency or British citizenship, additional reporting obligations arise under HMRC's foreign income rules and, where applicable, the India-UK Double Taxation Convention (DTC). The DTC prevents earnings being taxed twice, but it does not eliminate reporting requirements — and failure to declare foreign source income on a UK self-assessment return carries penalties starting at £100 and escalating to 200% of the unpaid tax where HMRC determines deliberate concealment.
"The moment wealth arrives suddenly, three things happen simultaneously," notes the Money and Pensions Service (MaPS) in its guidance on sudden financial windfalls. "The decisions feel urgent, the complexity feels overwhelming, and the support networks around you may not have experienced anything similar." Without structured professional input, the result is frequently wealth erosion: poor tax planning, premature lifestyle inflation, and under-diversified assets.
This dynamic is not confined to professional cricketers. It plays out every quarter in the careers of UK-based South Asian professionals in technology, finance, and business — wherever a salary event, equity vesting, or business exit compresses years of wealth-building into a single tax year.
The UK Professional's Equivalent: When the Windfall Arrives
Britain's South Asian community, numbering over 1.5 million people of Indian heritage according to the 2021 England and Wales Census, maintains a close cultural connection to Indian cricket — and a disproportionate presence in the sectors where sudden wealth events are most common. According to HMRC's income distribution data, approximately 862,000 UK individuals filed self-assessment returns for 2024-25 reporting income above £100,000, a threshold at which the personal allowance begins tapering at a rate that creates an effective 60% marginal rate on income between £100,000 and £125,140.
For young professionals who have built careers in the same time frame as Dhir's IPL arc — roughly 2022 to 2026 — this threshold is increasingly reachable. A senior software engineer joining a scale-up at £65,000 in 2022 who sees salary growth, equity grants, and a liquidity event converge in the same year as a promotion now faces structurally identical decisions to those facing the India cricketer.
The question is not whether the money is significant. It is whether the right decisions are made in the narrow window before the tax year closes.
For further context on how cricket wealth events have been analysed in recent months, England's Jacob Bethell navigated a similar trajectory at 22 — and the financial principles that applied there apply with equal force to any young high earner watching their income double in a single cycle.
Priya's £185,000 Vesting Event: A Concrete Case
Consider the scenario of Priya, 31, a software architect based in Birmingham. In Q2 2026, her employer's acquisition triggered a vesting event on restricted stock units she had accumulated over four years. The shares vest simultaneously — £185,000 gross, all falling into the 2026-27 tax year.
Without professional advice, the outcome is stark. Her £185,000 vesting adds to her existing £68,000 base salary, taking total earnings to £253,000 for the year. At that level: her personal allowance is fully withdrawn (tapered entirely between £100,000 and £125,140), she pays 45% additional-rate income tax on all income above £125,140, and her employer withholds income tax on the share vesting event but typically uses an emergency code that under-withholds against her actual marginal rate.
Her estimated HMRC liability on the vesting event alone: approximately £83,250. Without a self-assessment plan lodged by 31 January 2027, late payment penalties begin accruing. If she failed to notify HMRC of the income source separately, a potential compliance investigation follows.
The if/then logic is direct. If Priya engages a qualified wealth manager and tax adviser before the tax year closes on 5 April 2027, a structured set of interventions becomes available: maximise pension contributions up to the 2026-27 annual allowance of £60,000, reducing taxable income and partially restoring the personal allowance; allocate the £20,000 Stocks and Shares ISA allowance to shelter future growth tax-free; and assess whether charitable giving under Gift Aid relief further reduces the liability. With those three steps executed correctly, her net tax bill on the windfall falls by an estimated £22,000–£27,000. The advisory cost for this service typically runs £2,500–£5,000.
If she waits until the January self-assessment deadline without specialist input, she pays full marginal rates on every pound of the windfall — forfeiting a net saving of £17,000–£25,000 for the cost of a single professional consultation.
What the Experts Recommend
Wealth managers who specialise in sudden wealth events consistently highlight the same sequencing error: most people address the immediate tax bill first, then look for investment advice, and then — sometimes never — address protection and estate planning. The correct order inverts this entirely.
Protection first: income protection, critical illness cover, and life assurance should be reviewed or initiated before any discretionary investment is made. A sudden £492,000 income event or a £185,000 RSU vesting is meaningless if it is followed by six months of long-term illness with no income replacement policy in place.
Tax planning second: as Priya's case illustrates, the pension and ISA moves that reduce a windfall's tax exposure are time-sensitive. They expire at the end of the tax year and cannot be backdated.
Investment structuring third: only once protection and tax efficiency are secured does portfolio construction — equities, bonds, property, alternatives — become the right focus.
Estate planning fourth: for UK residents with family networks that span India and the UK, the interaction between UK inheritance tax (IHT at 40% above the nil-rate band), overseas assets, and dual domicile questions requires specialist advice that goes beyond what a generalist accountant can provide.
For anyone who watched Dhir receive his debut cap and felt a sense of recognition — the young professional suddenly at the centre of decisions they have not encountered before — the most valuable step mirrors the one Dhir took before his ODI selection: surround yourself with a skilled support team before the pressure moment arrives.
The Financial Conduct Authority maintains a public register of authorised wealth managers and independent financial advisers in the UK. Verify any adviser's authorisation status before engagement.
For wealth management guidance tailored to sudden income events, high-income tax planning, or the intersection of UK and overseas assets, qualified advisers are available through ExpertZoom without referral requirements or minimum asset thresholds.
This article is for informational purposes only and does not constitute financial advice. Always consult a qualified, FCA-authorised financial professional before making investment or tax planning decisions.
