 Imogen Bennett
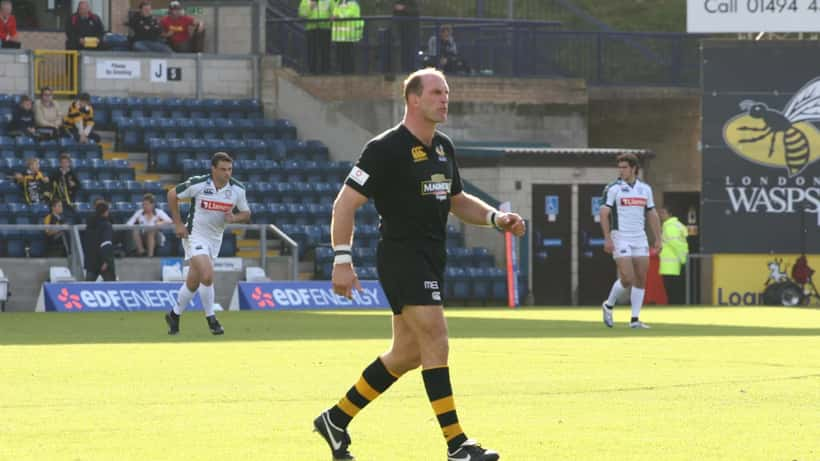
Lawrence Dallaglio, the former England rugby captain and 2003 World Cup winner, had his bankruptcy restrictions extended until 7 August 2026 after a London High Court ruled he spent approximately £200,000 in just six months — without setting aside a single penny for tax obligations or court-ordered maintenance payments. The case has drawn scrutiny not merely as a celebrity story but as a textbook illustration of how even high earners can fall into serious financial difficulty without professional guidance.
What the Court Revealed
Declared bankrupt in May 2025, Dallaglio would ordinarily have seen his restrictions lifted after 12 months. But following an application by joint-trustee Nick Parsk, a judge added three months to his term, extending restrictions until August 2026.
Court filings describe what trustees called "excessive spending" between August 2025 and January 2026. The former England captain allegedly spent approximately £1,000 per month on clothing and footwear, £1,000 per month on travel and transport, £800 per month on groceries, and £500 per month on alcohol — totalling around £3,300 in monthly discretionary outgoings alone, before rent, legal fees, or debt service.
Over the same six-month period, Dallaglio reportedly earned around £200,000 through broadcasting and commercial work. Every penny of it, according to court filings, was spent. A court-ordered spousal maintenance payment to his former wife Alice has reportedly been in arrears since August 2025.
Trustees also noted that the 53-year-old was "largely uncooperative," cancelling multiple appointments for the valuation of his rugby memorabilia. When the assessment finally took place, "one significant item was missing." The portrait that emerged in court was not of someone unable to earn — but of someone unable to separate earnings from expenditure in a structured, legally compliant way.
Why High Earners Are Surprisingly Vulnerable
It can seem paradoxical that someone earning £200,000 in six months faces bankruptcy. But this pattern — high income, unrestricted spending, no provision for structured obligations — is one that wealth management specialists encounter frequently.
Professional athletes and broadcasters often experience what advisers call "income compression shock": a career that generates six-figure sums ends or contracts, but a lifestyle built on that income doesn't scale down at the same pace. Add a divorce, spousal maintenance orders, and accumulated tax liabilities, and the arithmetic becomes hostile very quickly.
According to the UK Insolvency Service, approximately 8,500 individuals entered bankruptcy in England and Wales in Q1 2025 alone. A significant share are self-employed professionals and former high earners — people who, unlike salaried employees, have no employer automatically withholding tax, pension contributions, or other structured deductions. When income arrives in large, irregular amounts, the temptation is to treat the gross sum as spendable. For most UK higher-rate taxpayers, up to 45% of earnings above the £125,140 threshold belongs to HMRC before any lifestyle cost is incurred.
The Dallaglio case also highlights how court-ordered obligations — unlike a mortgage or credit card — don't send monthly reminders. They accumulate silently until a trustee or judge forces the reckoning.
The £200,000 Gap: A Concrete Illustration
Consider a freelance broadcaster earning £200,000 between August 2025 and January 2026 — roughly £33,000 per month gross. After applying a 45% higher-rate tax band to earnings above the £125,140 threshold, and accounting for National Insurance, the estimated after-tax take-home on that sum is closer to £120,000.
Now add the following monthly obligations: a court-ordered maintenance payment of £2,000 per month (six-month total: £12,000), a tax reserve for the current tax year of at least £3,300 per month (six-month total: approximately £20,000), and the alleged discretionary spending of £3,300 per month. That is £8,600 per month in structured and discretionary outgoings, or £51,600 over six months — leaving a net position of roughly £68,400 from after-tax income.
If those structured obligations are ignored and the full after-tax income is treated as spendable cash, then a £200,000 earner can end 2026 with debts in excess of £30,000 to HMRC, £12,000 in maintenance arrears, and no assets set aside — precisely the position described in court filings. This is not a problem of insufficient income. It is a problem of financial architecture: the absence of ringfenced accounts for tax, debt service, and protected savings before discretionary spending begins.
A qualified wealth manager, engaged when income first becomes irregular — at the point of retirement from professional sport, the start of a divorce, or the transition to self-employment — would typically establish separate holding accounts for each obligation category. The test is simple: can you see, at any moment, how much of your income is already committed before it arrives? Most people who reach insolvency cannot.
Three Warning Signs That Should Prompt a Wealth Management Consultation
Financial advisers consistently identify three patterns in clients who come to them too late:
Irregular income without a tax reserve account. Moving from a stable salary to consultancy, broadcasting, or commercial work means the employer no longer withholds PAYE. Without a dedicated account automatically receiving at least 30–40% of each payment, tax liabilities accumulate invisibly. The UK Self Assessment deadline does not forgive six months of unbudgeted spending.
Court or contractual obligations that don't arrive as direct debits. Maintenance orders, litigation settlements, and contractual penalty clauses don't appear on a bank statement until they become arrears. A wealth manager sets up calendar-triggered reviews and payment structures so that no obligation drifts unattended past its due date.
Illiquid assets that look like wealth but can't pay bills. Dallaglio's rugby memorabilia is a clear example: potentially valuable, but not accessible without active management. A financial adviser helps clients understand which assets can be realised, on what timeline, and at what cost — before insolvency forces a distressed sale or court-ordered valuation.
You can read more about how England sports professionals navigate financial transitions after their playing careers in Liam Dawson's England Recall at 35: The Financial Case for Career Flexibility.
What Trustees Actually Do — and Why Non-Cooperation Compounds the Problem
When a bankruptcy restriction order is issued in England and Wales, the appointed trustee has significant powers: to investigate financial affairs, access bank records, compel the valuation of assets, and report non-compliance to the court. The trustee does not need a court order to request cooperation — but a pattern of missed appointments and missing assets can trigger exactly the kind of court intervention that extended Dallaglio's restrictions.
Under the Insolvency Act 1986 and related guidance from the UK Insolvency Service, a bankrupt individual is legally obliged to cooperate fully with trustees, disclose all assets honestly, and refrain from obtaining credit above £500 without disclosing their status. Breaches can result in extended restriction periods — or, in serious cases, prosecution.
This is where legal and financial advice intersect most critically. An insolvency solicitor can ensure that communication with trustees is properly managed, that asset disclosure is complete, and that any ambiguities — such as the whereabouts of a "missing significant item" — are resolved before a court hearing rather than at one.
What to Do If You're in a Similar Financial Position
The Dallaglio case is a public reminder that financial vulnerability doesn't correlate with income level. Whether you are a recently retired professional, a self-employed consultant managing irregular income, or someone navigating divorce while maintaining business obligations, the structural risks are the same.
The right moment to consult a wealth management expert is not when a court extends your bankruptcy restrictions. It is the first month in which your income becomes irregular, your obligations become complex, or your outgoings begin to approach your gross rather than your net.
ExpertZoom connects you with vetted, independent UK wealth management specialists who can model your tax exposure, structure your cash flow, and help you separate what you earn from what you owe — before the gap closes against you.
This article provides general financial information for educational purposes only. It does not constitute financial or legal advice. For guidance tailored to your personal circumstances, consult a qualified independent financial adviser or solicitor.
