 Julia Vachon
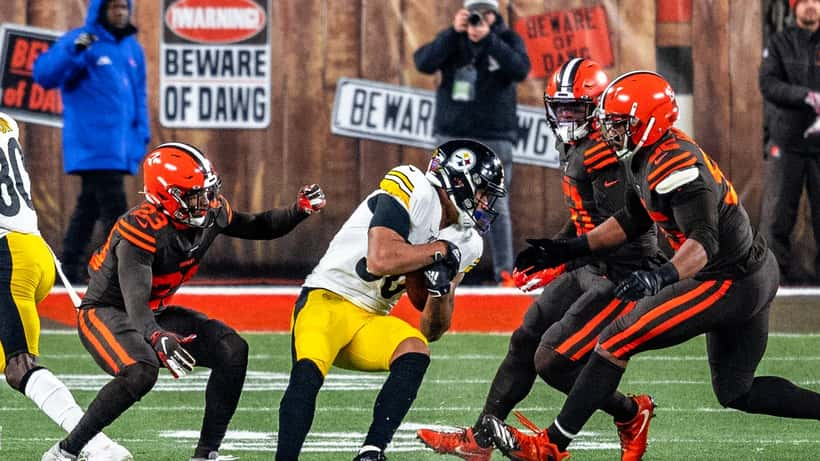
The Pittsburgh Steelers and Cleveland Browns renew one of the NFL's most passionate rivalries this October 2026 — and while fans across Canada are picking their side, wealth management experts warn that betting on your favourite team is one of the most expensive habits in behavioural finance. The real game, they say, isn't being played on the field.
The Numbers Behind Canada's NFL Betting Surge
Few matchups in professional football generate the raw emotional intensity of a Steelers-Browns game. With 146 meetings since 1950, the AFC North rivalry is built on decades of visceral moments: the 2016 brawl, the "Immaculate Reception" lore, the Myles Garrett helmet incident. In 2026, the Week 6 clash at FirstEnergy Stadium in Cleveland is already drawing extraordinary betting interest from Canadian fans.
According to the Alcohol and Gaming Commission of Ontario (AGCO) 2025–2026 iGaming Market Report, NFL games account for 34% of all single-event sports bets placed through licensed Ontario operators — a figure that climbs to 47% during rivalry matchups. Total legal NFL wagering in Canada exceeded $1.1 billion CAD in the 2025 season alone, a number that has grown 28% year-over-year since Parliament passed Bill C-218 in 2021.
The scale of the market means that when fans bet emotionally on games like Steelers-Browns, the aggregate losses are substantial — and pattern-driven enough that financial planners now routinely address sports betting in household budget reviews.
What Behavioural Finance Says About Team Loyalty
Fan bias is a formally studied cognitive error in behavioural economics. It occurs when a bettor systematically overestimates the probability of success for entities they are emotionally attached to — their favourite team, their employer's stock, their home city's real estate market. The mechanism is identical whether it's a $300 NFL wager or a $30,000 over-weight position in Canadian bank stocks.
Research published in the Journal of Economic Psychology (2024) found that self-identified "passionate fans" of specific NFL teams bet on their team to win in 68% of matchups — even when the lines clearly identified them as the underdog. Over a full 17-game regular season, this fan-biased strategy underperformed neutral, odds-based betting by an average of $847 per bettor.
The neurological explanation is the "familiarity heuristic": the human brain conflates emotional proximity with informational advantage. A lifelong Steelers fan genuinely believes they know more about their team than oddsmakers do. In rare cases — for dedicated insiders — that may be marginally true. For the vast majority of recreational bettors, this feeling is a cognitive illusion, not a predictive edge.
"Emotional attachment creates what we call the illusion of knowledge," explains a Toronto-based Certified Financial Planner who works with professional athletes and sports industry clients. "You feel like you know the Steelers better than any analyst because you've watched every game for 20 years. But familiarity isn't data — it's just feeling. And feeling is not an investing edge."
This same bias appears in client portfolios every week. Concentrated positions in employers' company stock, regional overweights driven by local pride, underweighting of foreign markets because they "feel less familiar" — these are all structurally identical to betting on the home team at unfavourable odds.
The Steelers-Browns game, then, is not just an event. It's an annual case study in how emotion overrides probability for hundreds of thousands of Canadians. As we've already seen with Canadian NFL bettors during the Eagles-Bears matchup, the financial consequences extend well beyond the final score.
Concrete Case: A Hamilton Fan's $1,800 Season
Consider this realistic composite, drawn from scenarios described by Ontario financial counsellors in 2026.
A 38-year-old construction foreman from Hamilton — a Steelers fan since relocating from Pittsburgh in 2018 — places $300 on Pittsburgh to beat Cleveland in Week 6 at –140 odds (implied probability: 58.3%). He wins. He feels validated.
Emboldened, he bets $450 on the Week 14 return matchup. He loses. Convinced his team "owes him one," he places $600 on Pittsburgh in a wild card game. Another loss.
By season end: $1,800 wagered, $1,100 lost net. Return on investment: –61%.
If those same $1,800 had been contributed to a Tax-Free Savings Account (TFSA) invested in a broad TSX Composite ETF — which returned approximately 9.2% year-to-date through October 2026 — he would have generated roughly $166 in gains rather than absorbing $1,100 in losses. The total swing in outcomes: $1,266 CAD, enough to cover a month of groceries and utilities for his family.
The core dynamic at work: his $300 Week 6 win was treated by his brain as "skill confirmation." The subsequent losses were treated as "bad luck." This asymmetric attribution is a textbook manifestation of the self-serving bias — the same pattern that causes investors to attribute gains to personal intelligence and losses to market anomalies, compounding poor decision-making over time.
The Tax Exposure Most Bettors Never See Coming
Here is where the stakes escalate beyond the betting app. Canadian tax law is ambiguous on sports betting in ways that can trap high-frequency recreational bettors.
Under CRA Interpretation Bulletin IT-483R and the Income Tax Act Section 3, recreational gambling winnings are generally non-taxable. However, if the CRA determines that a taxpayer is engaged in a "system or scheme" of betting — characterized by consistent large wagers, detailed record-keeping, and a profit motive — those winnings become taxable business income.
Since single-event betting was legalized in 2021, the CRA has incrementally increased scrutiny on high-volume sports bettors. The threshold is not clearly defined in statute, which means taxpayers who bet consistently and at scale may receive reassessment notices years after the fact.
Tax professionals generally flag cases involving more than $500 per game per week in consistent wagering, documented betting systems or spreadsheets, or self-promotion as a "professional bettor" on social media. If you fall into any of these categories heading into a high-emotion game like Steelers-Browns, a one-hour consultation with a tax accountant before you wager is worth more than any odds research you could do.
This risk profile mirrors what we covered in the Falcons-Steelers legal analysis earlier this season: the intersection of sports events and Canadian law contains surprises that most fans are simply not aware of.
What to Do Before Sunday
Wealth advisors and certified financial planners who work with sports-engaged clients offer a consistent pre-game protocol for big rivalry bets:
1. Apply the "stranger test." Would a stranger with no team allegiance place this exact bet at these exact odds? If the answer is no, you need to honestly assess whether your edge is data-based or loyalty-based.
2. Set a season loss limit, not a game limit. Fan bias compounds across 17 weeks. A $150-per-game limit becomes a $2,550 seasonal exposure. A season cap of $600 forces genuine selectivity and mimics how a disciplined investor size-limits positions.
3. Understand the registered account opportunity cost. Every dollar placed on a Steelers moneyline bet at –140 odds is a dollar not compounding in a TFSA, RRSP, or FHSA. For Canadians under 50, the compound growth gap between a recreational betting habit and index fund investing is measured in tens of thousands of dollars over a career.
4. Consult a professional if your seasonal wagering exceeds $2,000. At that level, the tax exposure, the behavioural patterns, and the portfolio impact are worth a structured conversation with a licensed financial planner or tax accountant. The CRA reporting risk alone justifies the consultation fee.
The AGCO-licensed platforms are legally required to offer deposit limits, cooling-off periods, and self-exclusion tools under Ontario Regulation 406/21. These are free, effective, and underused. Visit your operator's responsible gaming section before Sunday.
The Steelers and Browns will settle their rivalry on the field. Make sure that result does not also settle your RRSP balance.
This article is for informational purposes only and does not constitute financial or legal advice. For guidance tailored to your situation, consult a licensed financial planner or tax professional in your province.
