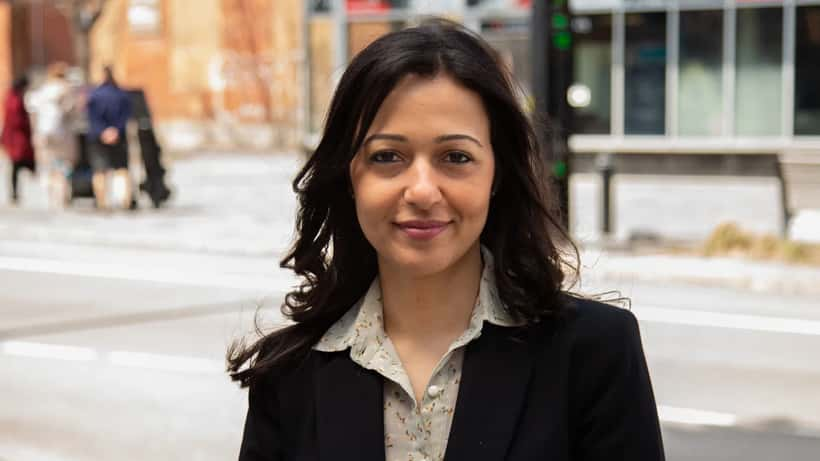
 Julia Vachon
Ruba Ghazal, co-spokesperson for Québec solidaire (QS), secured her riding of Mercier in Monday's provincial election, as the Canadian Press projected her victory on October 5, 2026. The result — coming as the Parti québécois was simultaneously projected to form government — puts Québec solidaire in a uniquely influential position: a credible opposition voice, and potentially a future coalition partner, whose economic platform is among the most ambitious in Quebec's recent political history.
For workers, landlords, business owners, and investors across the province, the QS agenda is not an abstract political exercise. Its flagship proposals — a wealth tax on assets above $25 million, a minimum wage increase to $20 per hour, and hard caps on annual rent increases — could reshape the financial landscape of everyday Quebec life in ways that wealth advisors are already flagging as urgent.
What QS Won — and What They're Promising
Ruba Ghazal's Mercier win was widely anticipated; her broader political significance was not. At 44, the Palestinian-born environmental scientist became the first person of Arab descent to lead a major Quebec party, entering the campaign trail as spokesperson after veterans Manon Massé and Gabriel Nadeau-Dubois stepped aside. Under her leadership, QS contested every Quebec riding with a platform built on three economic pillars.
First, a wealth tax targeting households with net assets above $25 million — a threshold capturing roughly 4,000 Quebec families. After intense internal debate at a May 2026 congress in Montréal, QS rejected a lower $5 million threshold, keeping the levy focused on the province's wealthiest tier while leaving the door open to revisit that floor in a future term.
Second, a $20 minimum wage — up from $15.75 in 2026, representing a 27 per cent increase that would touch nearly every sector of the Quebec economy: retail, food services, care work, and construction subcontracting.
Third, rent caps tied to the Consumer Price Index, replacing the existing Tribunal administratif du logement (TAL) formula. QS also committed to adding 50,000 social and community housing units in a first mandate. Where the current system allows for TAL-calculated annual increases that have ranged between 2.8% and 5.9% in recent years, QS's proposed ceiling would track inflation — which averaged 2.1% in Quebec in 2025, according to Statistics Canada.
Why Wealth Advisors Are Taking Notice Right Now
For Quebec's top 4,000 households, the wealth tax is a direct concern. But wealth managers across the province say the downstream effects of the full QS platform are broader — and more immediate for ordinary Quebecers than the headline wealth-tax figure suggests.
The minimum wage increase creates wage compression: workers currently earning $18 to $22 an hour see their relative advantage over entry-level positions shrink. In sectors where skilled workers negotiate compensation above minimum, this typically triggers a cascade of salary review demands. For business owners, it means payroll projections that were fixed 12 months ago may need to be redrawn before the first quarter of 2027.
The rent cap proposal, meanwhile, affects anyone holding a residential income property in Quebec — from an individual landlord with a Montréal duplex to incorporated real estate holding companies with dozens of units. The QS proposal would compress the revenue ceiling precisely when property taxes, insurance costs, and maintenance expenses are rising.
"The issue isn't just the wealth tax itself," notes one Montréal-based certified financial planner familiar with Quebec's landlord community. "It's the compound effect of capping rental income, raising wage floors, and constraining business margins simultaneously. Three pressure points at once creates a planning window that won't stay open forever."
For more context on how Quebec's provincial and federal elections shape the financial outlook for residents, our analysis of Paul St-Pierre Plamondon's economic platform covers the parallel planning questions raised by the PQ's projected win.
When the Rent Math Actually Changes: A Montréal Landlord Scenario
Consider the case of Marc, a 48-year-old Montréal contractor who purchased a triplex in Rosemont in 2019 and rents out two of the three units to partially cover his mortgage. His current rents: $1,750 and $1,900 per month.
Under the existing TAL framework, Marc could apply for increases of approximately 4.3% in 2027 — adding roughly $75 and $82 to each unit's monthly rent, for a total increase of $157 per month, or $1,884 per year in additional gross rental income.
Under QS's proposed CPI cap, if Quebec's inflation rate in 2027 aligns with the Bank of Canada's 2% target, Marc's allowable increase would be $35 and $38 respectively — totalling $73 per month, or $876 per year.
The gap: $1,008 annually in forgone rental income. Across a 10-year financial planning horizon, that difference compounds to more than $10,000 in lost gross revenue — before accounting for rising property taxes, maintenance costs, and the capital gains implications when Marc eventually sells.
The if/then logic is clear:
- If you hold one or more income properties in Quebec and your gross rental income exceeds $20,000 annually → a structured wealth review (typically $200–$400 for an initial session with a certified financial planner) could identify legal restructuring options — dividend strategies, accelerated depreciation elections, or corporate ownership changes — that offset the revenue compression.
- If your rental property sits inside a corporation → the interaction between passive income rules and a revised rental revenue ceiling makes a tax planning review particularly urgent before any bill reaches the National Assembly floor.
Beyond Real Estate: Three Other Financial Ripples to Watch
Incorporated small businesses. A $20 minimum wage will increase payroll costs substantially for small restaurants, care facilities, and retail operators. Business owners who currently blend salary and dividends to minimize their effective tax rate will need to model whether the optimal compensation structure changes as wage floors rise.
Registered savings strategy. If Quebec's investment climate shifts under a more interventionist government, some financial advisors recommend reviewing geographic diversification within registered accounts — through pan-Canadian equity exposure or income trusts operating outside Quebec. The interaction between RRSP contribution room and provincial tax calculations also makes a review worthwhile for high earners.
Estate planning for growing families. For families whose net worth is on track to approach the $25 million threshold over a 10- to 20-year horizon — a category that includes successful Quebec entrepreneurs in real estate, manufacturing, and professional services — an estate freeze conversation should now be on the agenda. An estate freeze locks in the current value of a family business for tax purposes, protecting heirs from future tax on appreciation that accrues after the freeze date. The earlier this is structured, the more effective it tends to be.
Your Next Steps Before the Legislative Session Opens
Quebec's new government will form in the coming weeks, and the National Assembly's first session of the new term is expected before the end of 2026. Financial advisors consistently say the window between an election result and a sitting is the optimal time to plan — not to react after a bill has passed.
Three immediate steps worth taking:
Audit your Quebec income streams. Map rental income, business revenue, and employment earnings against a $20/hr wage scenario and a CPI-only rent increase trajectory. Where are the gaps?
Book a consultation with a wealth management advisor who knows Quebec's specific tax code. Quebec's provincial tax rules — administered by Revenu Québec — diverge from federal rules in ways that matter significantly for incorporated professionals, landlords, and anyone approaching the wealth-tax threshold.
Check lease renewal dates. If any rental agreements are up for renewal in the first half of 2027, understanding your current rights under the TAL before new legislation passes gives you optionality that disappears once a bill becomes law.
As QS's Ruba Ghazal takes her seat in the National Assembly and the province's new government forms, the financial implications of October 5 will unfold over months, not days. The Quebecers who act on the planning signals now — rather than waiting for legislation to land — will be best positioned to navigate whatever the new legislature brings.
