 Julia Vachon
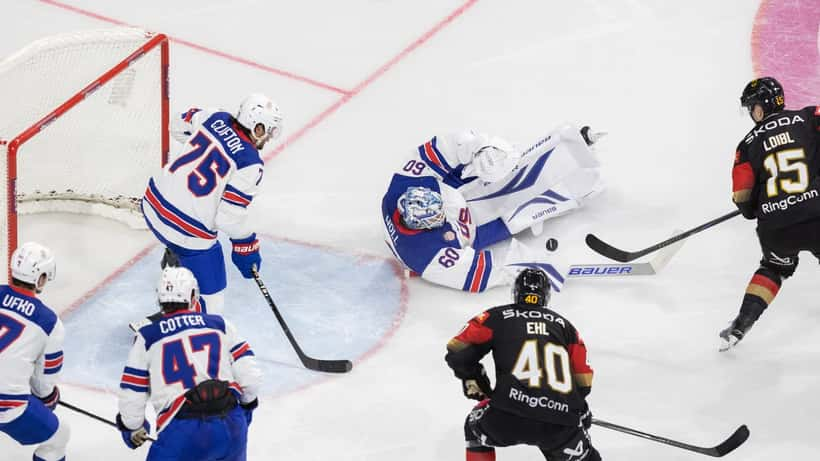
Paul Cotter scored the Vancouver Canucks' first goal of the 2026-27 NHL season on September 27, 2026 — a milestone moment for a player who, just three months earlier, had been shown the door by the New Jersey Devils. In July, the Devils non-tendered the 26-year-old forward, effectively ending his contract without a renewal offer. Cotter then signed a one-year, $2.15-million deal with Vancouver, instantly becoming a centrepiece of the Canucks' rebuild. His story is a crash course in what short-term contracts reveal about income volatility — and why Canadians in contract-based or variable-income roles should be paying close attention.
From Stanley Cup to Prove-It Deal: Cotter's Career Reality
Cotter is no journeyman. He won the Stanley Cup with the Vegas Golden Knights in 2023, was a productive piece of two playoff-calibre teams, and opened the Canucks' season as a starting forward. Yet despite those credentials, he enters 2026-27 on a one-year "prove-it" deal with no guarantees beyond June 2027.
In the NHL, one-year contracts are standard currency for players in Cotter's position: too experienced to carry an entry-level salary, not yet established enough for a multi-year extension. At 26, Cotter is betting on himself — betting that a strong season earns him something longer and more lucrative next summer. It is the same gamble made every year by millions of Canadian contract workers, freelancers, and commission-based professionals who earn well today and have no certainty about tomorrow.
The Canucks reportedly pursued Cotter specifically for his ability to balance skill with physical play — a hybrid profile the team's coaching staff valued heading into the season. He arrived at training camp in Penticton in September telling reporters: "We're going to surprise a lot of people." What he did not say publicly is what every smart professional athlete must already know: the time to plan for what comes after a one-year deal is the day you sign it.
The $2.15 Million Illusion: What the Number Actually Means
When Paul Cotter earns $2,150,000 in 2026-27, the gross figure looks extraordinary. The financial reality is more instructive. Between Canadian federal and British Columbia provincial income taxes — BC's combined marginal rate on income above $240,000 runs approximately 53.5 percent — and standard NHL agent fees of three to four percent of contract value, the actual disposable income is substantially lower.
A rough breakdown:
- Gross salary: $2,150,000
- Agent fees (3.5 percent): approximately $75,250
- Combined income tax on the marginal portion: approximately $870,000–$950,000
- Estimated net-of-tax, net-of-fees income: approximately $1.1 to $1.2 million
That is still a significant sum. But it must cover housing in one of North America's most expensive real estate markets, year-round training and equipment costs, and — critically — investment and savings that must carry through 2027-28 if Cotter is non-tendered again. The Financial Consumer Agency of Canada notes that nearly 40 percent of Canadian households could not cover three months of essential expenses from savings alone. For a professional athlete on a single-year deal, or a contractor earning variably, that vulnerability is structurally identical — only the dollar amounts differ.
The Prove-It Contract and the Canadian Contractor
The one-year prove-it deal is not unique to professional sports. It is the structure that underlies a significant portion of Canada's workforce. According to Statistics Canada's 2025 Labour Force Survey, self-employed workers and contract professionals represent approximately 15 percent of Canada's employed population — roughly 3.1 million people. Many of them earn well in high-contract years and face abrupt income cliffs when engagements end.
The financial risks they share with Paul Cotter include:
- No employer-matched pension contributions
- No severance protection under the Canada Labour Code
- Mandatory CRA quarterly installment payments once net tax owing exceeds $3,000
- Full RRSP and TFSA contribution planning responsibility resting entirely on the individual
The difference between a professional athlete and a Canadian contractor is not the structure of the risk. It is that NHL players earning $2 million typically have an agent and a financial team pushing them toward a plan. Most contractors navigate these decisions alone.
When the Contract Ends Without Warning: A Concrete Case
Consider a 34-year-old IT consultant in Calgary — call her Michelle — who has just wrapped a 12-month contract at $130,000 with an energy sector company. The company decides not to renew in October 2026. No misconduct, no severance, no transition package — just an email saying the project is ending. Michelle's situation mirrors Cotter's non-tender structurally in every relevant way.
If Michelle entered her non-renewal with no financial plan in place:
- Net income after federal and Alberta provincial tax (approximately 39 percent combined effective rate on $130,000): approximately $79,300
- Monthly living expenses (mortgage, vehicle, childcare, utilities): $6,100/month
- Emergency fund available: $8,500
- Months of runway: approximately 1.4 months
By January 2027, Michelle faces a cash crisis — even though she earned $130,000 in 2026. And her CRA installment obligation still arrives: contractors who owe more than $3,000 in federal net tax must pay quarterly installments, and missing them triggers compound interest at the prescribed rate, currently 9 percent annually.
If Michelle had consulted a wealth management expert at the start of her contract year and structured her income differently:
- TFSA contribution (2026 room: $7,000): fully funded at $7,000
- RRSP contribution (18 percent of 2025 earned income, approximately $23,400): fully funded
- Tax installment escrow account (set aside at 35 percent of gross monthly invoices): $45,500 in reserve
- Remaining liquidity after contributions and escrow: approximately $3,400/month for expenses and discretionary savings
Michelle's runway extends to over 18 months. Her CRA obligations are pre-funded. She enters 2027 with structured assets rather than a looming tax bill. The difference between these two paths is not income. It is advice applied at the right moment in the contract cycle.
What a Wealth Manager Would Tell Paul Cotter — and You
NHL players at Cotter's salary tier increasingly work with certified financial planners who specialize in variable-income structures. The playbook they use is not proprietary to professional sport. The core tools — tax-loss harvesting, RRSP optimization, TFSA maximization, and professional corporation structuring — are available to any Canadian contractor or self-employed professional earning above $60,000 annually.
For context, the wealth management decisions facing athletes like Brett Howden on similar one-year, performance-contingent contracts follow the same structural principles: maximize deductible contributions during high-income years, establish liquidity buffers before the contract year ends, and build a diversified investment base that sustains the gap between engagements.
Canada's inflation environment — sitting near 3.1 percent in 2026 according to the Bank of Canada's most recent data — means every dollar left idle in a standard chequing account is losing purchasing power. A wealth manager's first priority is to ensure that a high-income contract year is not silently eroded by inaction and bracket creep.
For Canadians with variable or short-term contract income, the questions to address with a financial advisor before the contract year ends include:
- What is the optimal RRSP contribution to reduce this year's taxable income? For someone earning $130,000, full RRSP contributions can reduce federal taxable income by up to $23,400 — a tax deferral worth approximately $8,970 at marginal rates.
- Should I incorporate as a professional corporation? At incomes above $100,000, a PC can allow income-splitting with a spouse and defer personal tax on retained earnings.
- What is my CRA installment schedule for 2026 income? Missing installments triggers 9 percent interest — avoidable with a 30-minute review.
- How much liquidity buffer do I need? Canadian contract professionals report an average of 3.4 months between engagements, according to the Financial Consumer Agency of Canada's 2025 data. A minimum six-month liquid buffer is advisable; eight months is safer.
The Right Time to Act Is Before the Contract Expires
Paul Cotter signed his Canucks deal on July 1, 2026 — the first day of NHL free agency. If he is working with a skilled wealth manager, a plan for June 30, 2027 already exists. The same logic applies to any Canadian whose income is tied to a fixed contract term, a performance bonus structure, or self-employment revenue.
The most expensive financial mistake made by high-income contract workers is timing: waiting until the contract ends to think about what comes next. By then, the RRSP contribution window for that tax year may have passed, the CRA installment schedule is already behind, and the liquidity runway is shorter than it should be.
Paul Cotter arrived at Rogers Arena believing the Canucks will surprise people. Whether or not the team delivers on that promise, the financial structure he builds around this one year will determine whether $2.15 million becomes a foundation or a footnote. For Canadians in contract-based roles, the same window — and the same stakes — exist right now.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Consult a certified financial planner or wealth management professional before making investment or tax decisions.
