 Julia Vachon
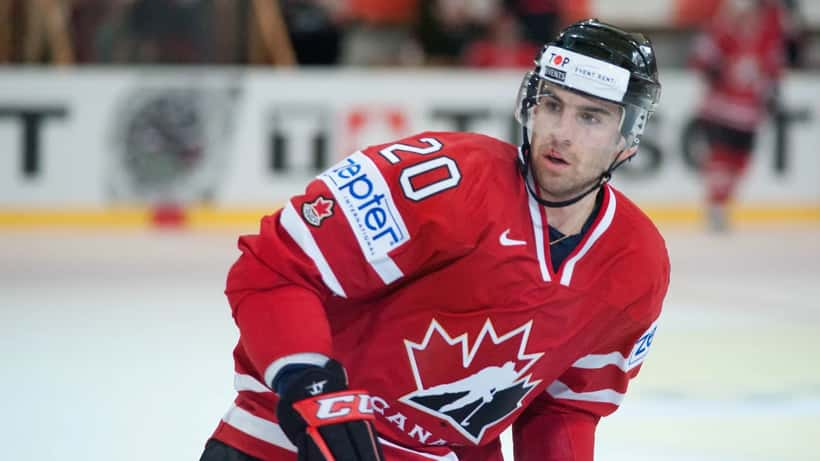
The 2026-27 NHL season is barely two weeks old, and John Tavares has already made history. On October 3, Toronto's veteran captain played his 600th game in a Maple Leafs uniform — joining franchise legends like Mats Sundin and Doug Gilmour in the club's record books. What makes the milestone remarkable is context: Tavares is 36 years old, in the first year of a four-year contract extension he signed at 35, and showing no signs of decline after finishing last season with 31 goals and 71 points in 82 games.
That contract — worth approximately $17.5 million over four years — raises a question that goes well beyond hockey circles: what does disciplined financial planning look like when you're deep inside a defined peak earning window? And what can high-income Canadians learn from how professional athletes structure their finances when they know, to the year, exactly when the salary ends?
The Tavares Deal in Context
When the Maple Leafs locked up Tavares in June 2025, the sports media largely focused on the hockey question: could a 35-year-old centre sustain top-line production? His $4.4-million annual cap hit carries through the 2028-29 season, meaning he'll be 38 or 39 when the deal expires. That's unusual longevity in the NHL, where most franchise centres are managed out of major commitments by their mid-30s.
But the financial planning dimension of the story has gone largely undiscussed. Tavares now has a four-year, clearly bounded income window. He knows exactly how long the principal earnings last. He can model every scenario — injury, retirement, trade — against a fixed endpoint. That kind of clarity is, paradoxically, one of the biggest planning advantages a high earner can have.
Earlier this summer, the Maple Leafs made similarly large commitments to other key players. As covered in our analysis of Jack Roslovic's $8M Maple Leafs deal, different contract structures create meaningfully different financial planning considerations for players at different career stages. Tavares's situation differs from a younger player's primarily because the runway is shorter — and the post-career income cliff is closer.
Why the Peak Earnings Window Is a Planning Emergency
Statistics Canada's most recent income data shows that the median after-tax family income in Canada sits at approximately $74,400 annually. A professional in the top income bracket — whether an NHL captain, a senior partner at a law firm, or an executive at a Bay Street investment firm — faces a federal marginal tax rate of 33% on income above $246,752, layered on top of provincial taxes that push combined rates in Ontario to approximately 53.5%.
At those rates, an unmanaged high-income period doesn't just miss opportunities — it actively destroys wealth. A $100,000 bonus with no plan becomes $46,500 after tax, sitting in a chequing account earning less than inflation.
The challenge for high earners isn't knowing they need to save — it's building the structure to convert active income into passive, long-term wealth before the window closes. Athletes face this more acutely than most: they have bigger numbers, shorter timelines, and an industry full of cautionary tales. The rest of us have the same problem with different magnitudes.
What Wealth Management Advisors Focus On
Professionals who specialize in high-income financial planning consistently return to four core strategies for clients in their peak earning decades.
Maximize registered vehicles first. The RRSP annual contribution limit for 2025 was $32,490, calculated as 18% of the previous year's earned income up to the annual ceiling. The Tax-Free Savings Account (TFSA) provides $7,000 of additional tax-sheltered room per year. For someone earning $380,000 annually, these ceilings are reached quickly — but unused RRSP room carries forward indefinitely, meaning earlier years of under-contribution can be caught up in high-earning years.
Shift from lifestyle assets to income-producing assets. The most common wealth destruction pattern among high earners is converting peak income into depreciating lifestyle purchases — upgraded homes, vehicles, travel. Advisors push toward dividend-producing equities, real estate income trusts, and private equity positions that generate income independent of employment. The goal is building a base of assets whose cash flow continues after the salary stops.
Understand provincial tax structuring options. Professional corporations, spousal RRSPs, and family trusts can legally reduce effective tax rates when structured properly. These arrangements require specialist knowledge, and the Canada Revenue Agency has tightened scrutiny of arrangements that lack genuine economic purpose beyond tax minimization — making qualified guidance more important, not less.
Model the income cliff explicitly. The single most valuable exercise a financial advisor can run for a high earner is a detailed model of their income trajectory, including the exact year active earnings will drop. For Tavares, that's 2029. For a 44-year-old surgeon planning to retire at 58, it's 2040. Either way, the analysis forces a concrete conversation about the gap between projected expenses and sustainable passive income.
The Case Most Canadians Recognize
Consider Sarah, a 43-year-old regional director at a pharmaceutical company in Mississauga. Her total compensation including bonus is $340,000 per year. She expects to remain in a senior role for another eight to ten years before transitioning to a lower-stress position or stepping back entirely. She owns her home (current value: $1.2 million, with $380,000 remaining on the mortgage), has an RRSP balance of $225,000, and a TFSA that's funded to roughly 60% of its total available room.
Sarah's never had a formal wealth strategy. She's made reasonable decisions — contributing to registered accounts, paying down the mortgage — but has no model for what her income picture looks like at 60.
Scenario A — No action. Sarah continues her current contribution pattern for eight more years, adding approximately $32,000 annually to her RRSP and $7,000 to her TFSA. Her mortgage is paid off by 57. By 62, her registered savings total roughly $900,000 in nominal terms. Against a lifestyle that cost $340,000 in gross income to support, a safe 4% withdrawal rate generates $36,000 per year — a gap of well over $100,000 annually before CPP and any occupational pension.
Scenario B — Two sessions with a certified wealth management advisor. The advisor identifies $85,000 in unutilized RRSP carry-forward room from earlier, lower-earning years. They recommend accelerating catch-up contributions over three years, restructuring $60,000 of annual non-registered savings into a dividend-paying portfolio, and establishing a corporate vehicle for a side consulting practice Sarah has been offered but hasn't formalized. By 62, her portfolio generates $147,000 per year in sustainable income — supplemented by a projected CPP benefit of approximately $17,200 annually at 65.
The arithmetic difference between Scenario A and Scenario B is $111,000 per year in retirement income. The conversation that produced Scenario B took less than four hours. If Sarah delays acting by three years — staying in Scenario A mode until 46 — she permanently loses approximately $340,000 in compound growth and catch-up contribution capacity. The window exists now; it narrows every year.
The CRA Clock Runs Parallel to Your Earnings Clock
One reality that catches many high earners off guard: the Canada Revenue Agency's rules around income splitting and registered accounts change regularly, and the strategies available to a 40-year-old may not be available to the same person at 50. Spousal RRSP attribution rules, for example, require a minimum three-year holding period before withdrawals are taxed in the lower-income spouse's hands — a detail that only matters if you start early enough.
The Canada Revenue Agency's guidance on RRSPs and registered plans provides the authoritative baseline for understanding contribution limits, attribution rules, and the conditions under which various structuring strategies remain compliant. It's a starting point, not a complete strategy.
What the CRA guidance doesn't do is model your specific situation against your income trajectory, your spouse's earnings, your corporate structure possibilities, or the optimal sequencing of registered and non-registered withdrawals in retirement. That's the conversation a wealth management expert provides.
When the Clock Is This Visible, Plan Now
John Tavares presumably didn't sign a four-year deal and then wait until 2028 to think about what comes after. The planning happens in parallel with the performance — building toward a post-career life that the contract years are meant to fund.
Most Canadians don't have an expiry date printed on their employment contract. But the peak earning window is just as real: incomes that rise through the 40s, plateau in the early 50s, and decline toward retirement. The Tavares principle applies regardless of whether you're playing in the NHL or running a department in Markham.
The earlier you engage a certified wealth management professional — especially while income is high enough to fund a real strategy — the more of that window you actually use.
This article is for informational purposes only and does not constitute financial or investment advice. Consult a qualified wealth management advisor and tax professional before making financial decisions.
