 Victoria Stewart
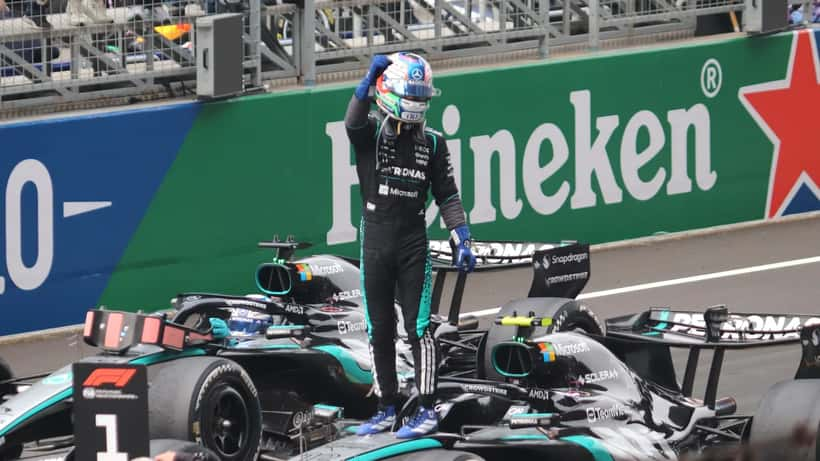
Kimi Antonelli arrives at the 2026 Azerbaijan Grand Prix in Baku on 26 September 2026 as Formula 1's most compelling storyline of the year: the 20-year-old Italian has piloted his Mercedes to a commanding Drivers' Championship lead of 292 points — 81 ahead of teammate George Russell — with nine races still on the calendar. With Mercedes also dominating the Constructors' standings at 503 points, the question in the paddock is shifting from whether Antonelli can win to what comes next. And in the world of professional sport, "what comes next" almost always begins with money.
The Stakes at Baku: A Championship and a Financial Milestone
The 2026 F1 season has rewritten expectations at every turn. Mercedes, revitalized under the new technical regulations introduced this year, has delivered one of the most dominant manufacturer campaigns since the hybrid era began. For Kimi Antonelli personally, clinching the championship would trigger a financial event that few people outside professional sport ever experience: a sudden, structured, and very large influx of wealth.
Formula 1 distributes its annual prize fund — which has grown to approximately USD $1.1 billion for the 2026 season — across the ten constructors, with payouts structured according to finishing position over a rolling multi-year period. Drivers themselves earn through their team contracts, and virtually every top-tier F1 agreement includes performance bonuses: clauses that activate upon winning a championship, a race, or reaching points thresholds. For a driver of Antonelli's profile, those bonuses run to millions of dollars, stacked on top of an already multi-million-dollar annual base salary.
Baku City Circuit adds its own drama. Historically one of the most chaotic venues in the calendar — long straights, tight castle walls, and unpredictable safety car periods — it has overturned championship leads before. As of today's race, Antonelli's math is straightforward: finish, avoid catastrophe, accumulate points. The championship could well be decided before the season reaches its final rounds in late November.
But outside the paddock, the story resonates beyond motorsport. The financial dynamics playing out around Antonelli — sudden wealth, professional management, structured planning — mirror a situation Canadians encounter every year in very different circumstances.
Sudden Wealth and the Expertise Problem
Lottery winners, inheritance recipients, business founders closing a sale, and professionals receiving large severance packages all face the same challenge that Antonelli's financial team navigates for him: sudden wealth is not the same as managed wealth, and the gap between the two can be enormous.
Financial planners call it "sudden wealth syndrome" — a well-documented pattern in which recipients of large, unexpected financial assets make decisions driven by emotion, social pressure, or simple inertia rather than sound strategy. Some act too quickly, making reactive investments in assets they don't understand. Others act too slowly, leaving significant sums in low-yield accounts while inflation quietly diminishes the real value of their windfall.
In Canada, sudden wealth arrives in a variety of ways. An inheritance after a parent's passing. The sale of a rental property held for two decades. A major legal settlement. A severance package after a restructuring. In all of these scenarios, there is typically a window — emotional, legal, and financial — during which the decisions made have outsized long-term consequences. Acting well in that window requires expertise.
This is precisely why wealth management professionals exist. For Canadians outside the top wealth brackets, the instinct is often to go it alone: a GIC here, a mutual fund there, maybe a conversation with a bank advisor who also sells mortgages. But for significant financial events, the stakes demand qualified guidance from a specialist who is legally accountable for the suitability of their recommendations.
The Regulatory Framework: What Your Advisor Must Provide
Wealth management in Canada is among the most tightly regulated in the world. Advisors must be registered with the Investment Industry Regulatory Organization of Canada (IIROC) — recently consolidated into the Canadian Investment Regulatory Organization (CIRO) — or with provincial securities commissions. These registrations impose a formal suitability standard: every investment recommendation must be documented as appropriate for the specific client's situation, goals, and risk tolerance. The Financial Consumer Agency of Canada provides official guidance on what Canadians can expect from qualified financial professionals and how to verify an advisor's credentials.
For a windfall recipient in Canada, the first conversation with a wealth management advisor will typically map the following terrain:
Immediate tax exposure: In Canada, inherited cash itself is not subject to income tax — the estate settles any capital gains before assets are distributed. However, all investment income generated after the inheritance is in your hands is fully taxable. An advisor helps structure holdings to minimize ongoing tax drag.
Registered account optimization: The TFSA and RRSP remain the two most powerful tax-sheltering tools available to Canadians. For 2026, accumulated TFSA contribution room for those who have never contributed can exceed $100,000. An RRSP contribution generates an immediate tax deduction — potentially returning thousands of dollars the following spring. Maximizing both before placing funds in taxable accounts is a foundational step.
Portfolio diversification: Concentrating a windfall in a single asset class — even real estate, which Canadians have historically trusted — introduces unnecessary risk. A diversified portfolio spanning domestic equities, international indices, and fixed income is standard professional practice. Specific allocations depend entirely on the recipient's timeline and income needs.
Mapping the Numbers: A Canadian Windfall Scenario
Consider a specific situation that plays out across Canada more often than most people realize.
Marie is a 41-year-old nurse in Calgary. In November 2026, she receives an inheritance of $300,000 following her mother's passing — cash, net of any estate tax obligations. She has a TFSA with $40,000 in contribution room remaining (she made partial contributions in earlier years), RRSP room of $35,000, and a marginal tax rate of approximately 43% given her income.
If Marie takes no action and parks the $300,000 in a high-interest savings account at 3% annual return, she earns roughly $9,000 per year — but this is fully taxable at her marginal rate, netting approximately $5,130 annually after tax. Over ten years, her $300,000 grows to around $351,000 in nominal terms. Adjusting for 2.5% average annual inflation, her real purchasing power at year ten is barely higher than the day she received the inheritance.
If Marie consults a registered wealth management advisor within 30 days, the picture shifts substantially:
- She contributes the full $40,000 TFSA room immediately, sheltering all future growth and withdrawals from income tax
- She makes a $35,000 RRSP contribution, generating a tax refund of approximately $15,050 (at 43%) — which she reinvests
- The remaining $225,000 is invested in a diversified portfolio targeting a 6.5% average annual return
Under this scenario, over ten years: the TFSA alone grows to approximately $74,000 tax-free; the RRSP to roughly $65,000 before withdrawal tax; and the taxable portfolio to approximately $422,000 before tax. Total nominal value: around $561,000. After estimated tax liabilities on withdrawal, Marie's real position is significantly stronger — and the $15,050 tax refund she reinvested immediately added compounding returns of its own.
The difference between the two paths exceeds $150,000 over a decade. That gap is not the result of exotic investments or aggressive risk-taking. It is simply the result of using the tools that Canadian tax law makes available — tools a qualified advisor is trained to deploy.
The exact numbers will vary with interest rates, market returns, and individual circumstances. But the structural logic holds: professional guidance on windfall management consistently outperforms the default of inaction or self-direction, particularly in a tax environment as nuanced as Canada's.
Taking the Next Step: Finding a Qualified Expert in Canada
For Kimi Antonelli, the infrastructure of professional management is built into his career from the moment he signs a contract. A team of accountants, tax advisors, and wealth planners ensures that every euro earned is allocated strategically. That infrastructure doesn't emerge by chance — it exists because the stakes justify the investment.
For Canadians managing their own financial turning points, the barrier to professional guidance has never been lower. Platforms like Expert Zoom connect clients directly with qualified wealth management specialists across Canada, allowing you to find an advisor matched to your specific situation — whether that involves a recent inheritance, a business sale, or a significant employment payout.
When evaluating an advisor, confirm their CIRO registration, ask about their specific experience with windfall clients, and clarify their fee structure upfront. A qualified advisor works in your interest — and in Canada, they are legally required to demonstrate it.
As Antonelli takes his place on the Baku grid today with the championship in sight, the financial story unfolding in the F1 paddock is more familiar than it might seem. The fundamentals — sudden wealth, professional planning, maximizing what you have — apply regardless of whether the windfall is nine figures or six.
This article is for informational purposes only and does not constitute financial, tax, or investment advice. Consult a registered wealth management professional for guidance specific to your situation.
