 Julia Vachon
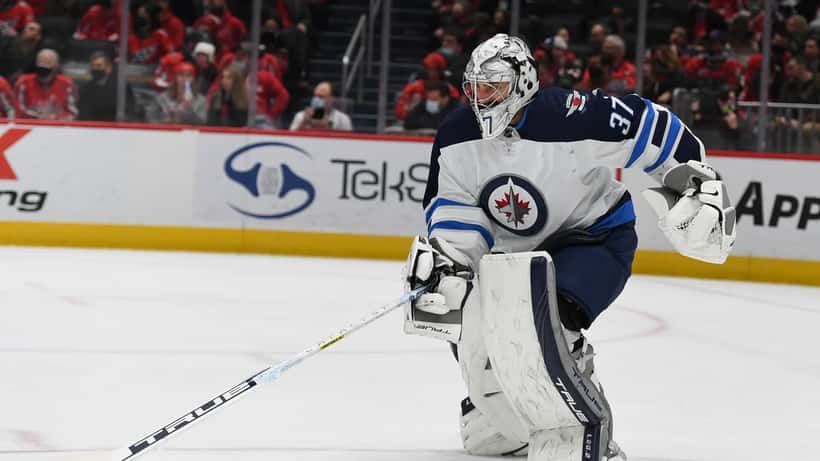
Connor Hellebuyck is forfeiting $39,000 every day he refuses to report to the Winnipeg Jets — and he's doing it deliberately. The three-time Vezina Trophy winner and 2025 Hart Trophy MVP has now missed the first week of the 2026-27 regular season without a trade, his voluntary absence already costing him more than $156,000 in forfeited salary while his agent continues quiet negotiations with Jets management and potential trade partners.
The Holdout Costing Him Thousands Every Morning
Hellebuyck publicly confirmed his trade request in late August 2026, stating that "moving on is the best path forward for me and my family." He had reportedly submitted the request months earlier. The Jets suspended him in September for failing to report to training camp — a standard escalation that signals just how serious the standoff has become.
His contract, a seven-year, $59.5 million deal with an $8.5 million average annual value running through 2030-31, contains a full no-movement clause this season. No trade can happen without his explicit approval — a clause that simultaneously protects him and traps him. He is voluntarily surrendering salary he is legally owed to force his own exit, calculating that the long-term benefit of playing elsewhere outweighs the daily bleeding.
A deal with the Buffalo Sabres appeared close at the 2026 NHL Draft but collapsed on the eve of the opening round, according to The Hockey News. Trade talks have since gone quiet. With no resolution in sight, each regular-season game day costs Hellebuyck another $39,000 — a number that sounds staggering until you examine what it reveals about how top earners actually navigate career crossroads.
Why Elite Earners Face Unique Career-Transition Risks
Hellebuyck's situation is dramatic, but the underlying dynamic is familiar to any Canadian earning significantly above the median: financial disruption at the top of the income bracket carries consequences that are categorically different from those at average earnings. At $8.5 million annually, federal and provincial income tax consumes roughly 47–54% of every dollar over the top marginal threshold. The real after-tax cost of his holdout — approximately $18,000–$21,000 per day after taxes — is still substantial, but roughly half the headline figure that dominates sports headlines.
The deeper risk, however, is structural. Long-term professional contracts create what wealth managers call income concentration risk: a compounding reliance on one employer, one sport, or one income stream. When that stream is interrupted — by a trade demand, a layoff, a contract non-renewal, or a disability — high earners often discover that their lifestyle spending, asset allocations, and tax arrangements were all calibrated around an income that has now stopped, or is about to.
According to the Financial Consumer Agency of Canada, high-income Canadians are consistently underserved by generic financial planning tools designed for median earners — basic RRSP advice, standard budgeting frameworks — that fail to address the complexity of deferred compensation, no-movement contract clauses, image rights, or multi-year income trajectories crossing different marginal-rate thresholds.
When Your Contract Becomes a Cage
Hellebuyck's full no-movement clause illustrates a counterintuitive principle in high-income financial planning: the same protections that safeguard you in one scenario can limit your options in another.
His clause converts to a modified no-trade clause on July 1, 2027, which would give the Jets significantly more flexibility to move him next summer. The financial implication is specific: if Hellebuyck holds out long enough that this season's loss becomes irreparable, the team gains more trade leverage next July — but Hellebuyck would have forfeited a full season of earnings in a contract whose salary peaks at $10 million in 2027-28 before declining to $6 million in the final year.
This kind of year-by-year income structure — high in the middle years, declining toward the end — is common not just in pro sports but in executive compensation, sales commission agreements, and deferred bonus structures. Knowing when to accelerate income, defer it, or exit a contract early requires modelling that most standard advisors are not equipped to provide.
Mapping the Holdout onto a Real Career Crossroads
Consider a Canadian equivalent that applies to far more people than NHL goalies. Imagine a 35-year-old senior software architect in Vancouver earning $420,000 annually — a top-1% income with a single-employer dependency not unlike Hellebuyck's. She has been offered a competing role at a US-based tech company and is weighing whether to resign, negotiate her current contract, or accept the external offer without advice.
Her annual gross: $420,000. After federal tax (33% top rate) and BC provincial tax (20.5% at the top bracket), her effective rate on dollars over $246,752 reaches approximately 53.5%. Net annual take-home: roughly $230,000.
Path A — she exits without consulting a wealth advisor or employment lawyer ($0 in fees): She resigns, triggering no severance entitlement under her contract. Her RRSP has $34,000 in unused contribution room she never maximized — contributions she can no longer make after her income drops during a potential 3-month transition. Her stock options, vesting on a 4-year cliff schedule, expire 90 days post-termination. She loses approximately $85,000 in unvested options she could have negotiated into her exit package.
Path B — she consults a wealth advisor and employment lawyer before giving notice (total cost: $4,000–$7,000): The advisor identifies the RRSP gap and helps her maximize contributions in her final high-income year, saving $18,190 in 2026 taxes (the RRSP contribution tax shield at her marginal rate). The employment lawyer reviews her contract and identifies a clause that entitles her to a 4-month notice period with continuation of benefits and option vesting — worth $140,000 gross ($74,000 after tax) in salary she would have otherwise walked away from.
If/then: if she seeks advice before handing in her notice, the combined gain is approximately $92,000 in that single year alone — a 13–23× return on the consulting cost. If she waits until after resignation, the RRSP window closes, the option vesting is gone, and the notice entitlement cannot be retroactively claimed.
Hellebuyck is learning a version of this lesson in real time: the moment the holdout began, certain financial windows closed. The longer it runs, the fewer trade partners remain engaged, and the more of his peak-earning years are consumed by a standoff that a structured exit agreement — negotiated before the training camp suspension — might have resolved in days.
The Pattern Repeats Across High-Income Canada
Hellebuyck's holdout is not primarily a financial story — it's about professional fit and personal priority. But the financial architecture surrounding it reflects a pattern that plays out across the 1.8 million Canadians who earn above $200,000 annually and will face a significant career disruption within the next decade, whether through restructuring, acquisition, disability, or voluntary transition.
Recent coverage on this platform has documented the same dynamic repeatedly: the Hart Trophy contract analysis found that even NHL MVP-level earners routinely leave mid-six-figure sums on the table through suboptimal tax planning during contract transitions; the Carter Bear Red Wings contract coverage showed that entry-level professional earnings — even at $975,000 — create immediate marginal-rate exposure that early wealth management engagement can structurally reduce.
The common thread is timing. The earlier a high-income earner engages qualified financial guidance before a career inflection point, the larger the range of tools available — and the more leverage they hold in any negotiation, whether with the Winnipeg Jets or with an HR director in a Bay Street office.
This article is for informational purposes only and does not constitute financial, legal, or tax advice. Consult a qualified wealth advisor and tax professional before making decisions related to income, investments, or employment transitions.
What You Should Do Before Your Own Crossroads
If you earn above $150,000 and your employment situation is shifting — through your choice or someone else's — the optimal moment to consult a wealth advisor is before any transition, not after it. Three concrete steps apply regardless of whether you're a goalie in Winnipeg or a product manager in Toronto:
Before any negotiation or resignation, have a wealth advisor map your current RRSP contribution room, TFSA capacity, option vesting schedules, and investment tax exposure — all of these windows narrow or close once income stops.
Before accepting a severance package, engage an employment lawyer to assess whether the initial offer reflects your contractual entitlements. Most employers open negotiations at 50–60% of what is actually achievable under applicable provincial employment standards.
If you hold a long-term income agreement — multi-year employment, deferred bonuses, commission arrangements — ask a tax advisor to model the year-by-year income trajectory and identify which years benefit from income acceleration versus deferral.
Hellebuyck will eventually be traded or will eventually report. Either outcome will require careful financial management of a contract reshuffled mid-term. The advisors who get that call first are not waiting for the drama to peak — they're the ones who were consulted before it started.
