 Victoria Stewart
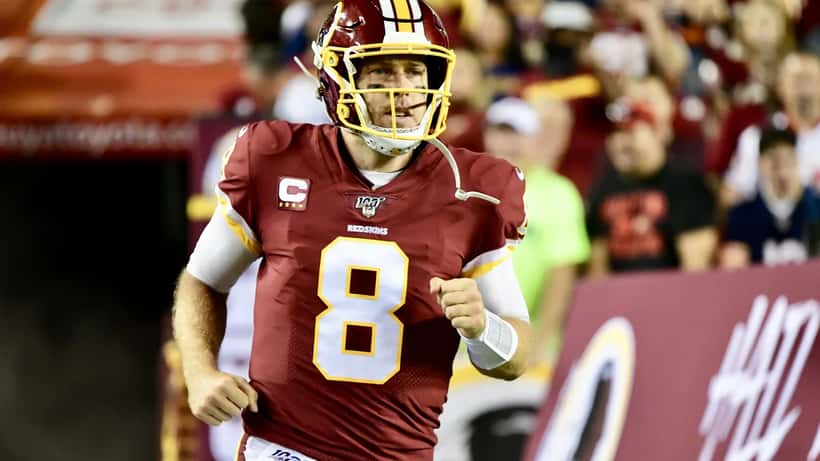
At 38 years old, most professionals are deep in peak-earnings territory — and quietly wondering how long it lasts. Case Keenum, veteran NFL quarterback for the Chicago Bears, answered that question on the field in Week 3 of the 2026 season. With starter Caleb Williams sidelined by a hamstring injury and backup Tyson Bagent recovering from a concussion, Keenum stepped in for his first regular-season start in nearly three years. It was a moment that put his unusual career back in the spotlight — and it offers a surprisingly clear financial planning lesson for every Canadian worker whose income doesn't come with a guaranteed timeline.
The Numbers Behind a $5.5 Million Backup Deal
Case Keenum's current contract with the Chicago Bears is a study in how veteran players and their financial advisors structure late-career earnings. The two-year, $5.5 million deal breaks down to an average annual value of $2.75 million. But the year-to-year structure is deliberately uneven: in 2026, Keenum earns a base salary of $1.3 million, a signing bonus of $1.6 million paid upfront, and a workout bonus of $100,000 — with a total cap hit of $2.2 million.
That structure is not accidental. NFL contracts are not guaranteed the way Canadian employment agreements are. A release in training camp can mean walking away with only the guaranteed portion intact. For a player at 38 who went nearly 36 months without a regular-season start, the front-loaded bonus serves a specific purpose: it locks in cash regardless of what happens next.
According to the NFL Players Association, the average NFL career spans just over three years. Quarterbacks who survive into their late thirties represent a statistical anomaly. Keenum's 14-year career — across seven franchises — isn't just an athletic achievement. It's a financial planning challenge that the vast majority of high earners will eventually recognize in their own lives.
Variable Income: A Canadian Parallel
Keenum's financial situation echoes a reality that millions of Canadians navigate every year. The contractor in Calgary whose project budget gets cut in Q3. The commission-based sales professional in Toronto who has a record year followed by a flat one. The consultant in Halifax who lands a major retainer — and then watches it expire without renewal.
These workers earn well during active periods but carry the same structural uncertainty as an NFL backup quarterback: they don't know when the income stops.
The Financial Consumer Agency of Canada reports that self-employment and contract-based work now account for a significant share of the Canadian labour force — a category that includes not just the formally self-employed but also workers whose variable compensation makes traditional retirement planning difficult to execute on autopilot.
The stat that matters here: workers with variable income consistently under-save during strong years and over-rely on those years to compensate for lean ones. A wealth advisor's role is to interrupt that pattern before the lean year arrives — not after.
If Your Income Looked Like Keenum's: A Concrete Case
Consider this scenario. A 40-year-old project manager in Ottawa — call her Sandra — has spent twelve years as a senior IT contractor. Her income between 2019 and 2024 ranged from $95,000 to $165,000 per year, depending on project volume. In early 2025, her anchor client restructured and her contract was not renewed.
Sandra's peak years were 2021 and 2022, when she earned $155,000 and $165,000 respectively. During those two years, her RRSP contribution room totalled approximately $58,000 (roughly $29,000 per year under the limits in effect). If she maximized those contributions, she would have:
- Reduced her taxable income in both years, generating combined federal and provincial tax refunds of approximately $20,000–$24,000 at Ontario marginal rates of 43.41%
- Built a tax-sheltered investment account generating growth on roughly $58,000 in principal
- Created a buffer she could draw down in 2025–2026 at a lower marginal rate during her lower-income period
The if/then logic: if Sandra had directed her 2021–2022 surpluses into her RRSP rather than into lifestyle upgrades or a non-registered savings account, she would have entered 2025 with approximately $82,000–$90,000 in total additional financial position (tax refunds reinvested + compounded RRSP growth at a conservative 5%). If she did not, she likely entered 2025 with a fraction of that cushion — and no structured drawdown strategy.
The difference between those two paths is not luck. It is the outcome of a wealth planning conversation that ideally happened in 2021, not in 2025.
The Veteran's Financial Playbook: Four Principles
What distinguishes athletes like Keenum — who have extended careers well beyond their expected shelf life — from those who struggle financially in retirement? Four principles appear consistently in sports financial planning research and map directly onto the challenges of any variable-income professional.
1. Treat every contract as potentially your last. Keenum's contract structure reflects this: the signing bonus is guaranteed, the base salary is not. Canadian contractors should mirror this mentally — treat the retainer or project as the guaranteed portion and plan conservatively against the variable elements.
2. Separate the lump sum from spendable income. A $1.6 million signing bonus feels like $1.6 million. At combined federal and provincial Canadian tax rates of 45–53% on high income, the net is closer to $800,000–$880,000. Wealth advisors help clients establish the correct tax-efficient allocation at the moment of receipt — not months later when the refund arrives and the mental accounting has already occurred.
3. Maintain a 36-month liquidity bridge. For high-income professionals with episodic income, the standard guideline is to hold liquid reserves equivalent to three years of essential living costs in low-risk, accessible instruments. For someone earning $140,000 in peak years, that means holding $150,000–$200,000 in a high-interest savings account or GICs outside the RRSP, available without penalty.
4. Revisit the plan after every major income event. Keenum's Week 3 start against the Eagles wasn't just a football game — it was an income event. A new performance incentive could vest. A strong game could trigger contract re-negotiation. An injury could end everything. Each scenario has specific financial implications that require an updated plan, not a static one written when the contract was signed.
What a Wealth Advisor Provides That Your Accountant Doesn't
A common gap in financial planning for variable-income Canadians is the assumption that tax filing covers wealth management. It doesn't. An accountant looks backward — at what happened last fiscal year. A wealth advisor builds forward-looking scenarios across multiple income trajectories.
For a professional with Keenum-style financials — variable multi-year contract, substantial assets, a clear but uncertain endpoint — a certified wealth advisor typically works through:
- Income splitting for couples where one partner has variable income and one does not, reducing household tax burden in peak years
- Spousal RRSP contributions that convert high-marginal-rate deposits into lower-rate withdrawals at retirement
- Corporate structure options for incorporated contractors — holding company investment portfolios, dividend extraction strategies, passive income thresholds
- CPP optimization — particularly relevant for workers whose career income may end before 60, affecting contribution years and optimal start timing for benefits
These decisions are not one-size-fits-all. They depend on the specific income trajectory, family structure, projected career horizon, and existing asset base — exactly the kind of modelling that requires a professional working with your actual numbers.
Wealth management specialists available through Expert Zoom can provide this analysis through a direct consultation, without the lead time or minimum asset thresholds common at traditional financial planning firms. For Canadians navigating NFL-style financial complexity around athlete contracts and career transitions, or the equivalent challenges in contract-heavy professional careers, the same principles apply.
When to Act — Before the Contract Ends
Case Keenum's Week 3 return to starting duty was a reminder that professional careers can last longer than anyone expects — and end faster than anyone plans. At 38, he remains a functioning NFL starter. He may not be one at 39.
The financial message is not about football. It is about timing. The best moment to engage a wealth advisor is not when the contract ends, the retainer expires, or the project runs out. It is during the period of highest income — when tax-efficiency decisions have the most leverage and the runway for compound growth is longest.
Whether you are a veteran quarterback clearing $2.75 million in base and bonus or a senior contractor in Ottawa projecting the next 36 months of income, the decisions made during strong years shape your options during uncertain ones. Keenum's 2026 start gives Canadian workers a useful frame: staying in the game requires a plan that accounts for the possibility that the game ends without warning.
Connect with a wealth management expert on Expert Zoom for a consultation tailored to your income structure and career timeline.
This article provides general financial information only and does not constitute personalized financial, tax, or investment advice. Please consult a qualified wealth management professional licensed in Canada for guidance specific to your situation.
