 Isla Henderson
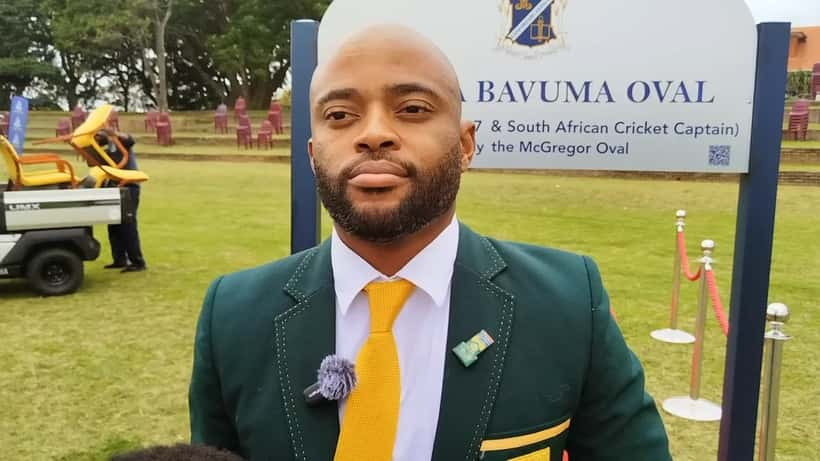
Temba Bavuma's name sits alongside Cristiano Ronaldo and Lionel Messi on TIME magazine's 100 Most Influential Sports People of 2026 — a recognition that landed just as South Africa's Test champion captain prepares to lead his squad at the ICC T20 World Cup on Australian soil this October.
The honour caps a remarkable 12 months for the 36-year-old right-hander, who guided South Africa to the ICC World Test Championship title at Lord's in June 2025 and won 11 of his first 12 Tests as captain. It followed his recovery from an elbow injury that temporarily sidelined him before he returned to lead the Proteas through a home ODI series against Australia in late September 2026. Yet behind the trophies, global recognition, and the theatre of a World Cup in Australia lies a financial reality every professional cricketer eventually confronts: careers are finite, earnings front-loaded, and the tax office does not pause for an off-season.
Wealth management specialists say this moment — a South African cricket icon headlining an ICC tournament in Australia — is an ideal lens through which to examine what elite athlete earnings actually look like, and why even high-earning cricketers leave significant wealth on the table without structured financial planning.
What TIME100 Recognition Means for an Athlete's Financial Profile
When a cricketer makes TIME's most influential sports list, it is not merely a PR milestone. It is a brand-inflection point that multiplies the financial complexity of a career. At Bavuma's level — a central-contracted Test captain, ICC champion, and now global name — income streams stack quickly: base Cricket South Africa retainer, ICC match fees, T20 franchise deals (SA20, The Hundred, or IPL), image rights, endorsements, and speaking or appearance fees.
Industry estimates place CSA's top-tier central contracts at ZAR 3.5–4.5 million annually (approximately AUD 290,000–375,000 at October 2026 exchange rates). For context, Cricket Australia's highest-tier contracts — held by players like Pat Cummins — carry reported base retainers above AUD 1.2 million before IPL or franchise earnings. Across all professional tiers, the structural challenge is identical: income arrives in large irregular tranches, careers end early, and few cricketers have built an investment base capable of replacing those earnings when the contracts stop.
According to Sports Australia data, the average professional cricket career in domestic competition spans 8–12 years. A player who peaks at 28 and retires at 36 has, at most, a decade to build the financial foundation that needs to last 50 more years. Without structured planning, that window closes without compounding.
The T20 World Cup Effect: Cross-Border Tax Complexity in October 2026
The ICC T20 World Cup on Australian soil in October 2026 creates a specific tax scenario: South African players earn Australian-sourced income during their time in the country. Under the Australia–South Africa double taxation arrangements, certain income — including ICC performance fees and commercial payments made in Australia — can be taxable in Australia, in South Africa, or in both jurisdictions, depending on residency days, contract structure, and how the ICC classifies each payment.
For Australian-contracted players, the inverse also applies. Domestic earnings surge during a major home tournament. Match fees for CA-contracted players at ICC events sit on top of the base retainer, and those mid-year surges push total annual income into higher marginal tax brackets without any change to lifestyle spending. Without pre-emptive planning, high-earning Australian cricketers can face an unexpected tax bill in May the following year — and spent the surplus in the interim.
This specific scenario is precisely what wealth management advisers are structured to prevent. The combination of irregular income timing, cross-border obligations, and superannuation contribution windows makes the window between October and 30 June the most financially consequential period of the calendar for any professional cricketer.
Why Elite Athletes Need a Financial Planner, Not Just a Bookkeeper
The narrative of athletes who earn millions and retire broke is clichéd but statistically persistent. In Australian cricket, as in AFL, rugby, and other professional sports, the earning window is typically 10–15 years, with peak earnings concentrated in a 5–8 year window. An accountant files tax returns. A wealth management adviser builds a structure ensuring those peak earnings compound into permanent capital.
The specific tools available to Australian athletes include concessional superannuation contributions (the annual cap is AUD 30,000 in 2025–26), income protection insurance, compliant trust structures for endorsement income, and diversified investment strategies that account for the lumpy nature of athlete income. For players earning above AUD 180,000 — which includes all CA-contracted cricketers — the marginal tax rate is 45 cents in the dollar plus the 2% Medicare levy. Every unstructured dollar above that threshold is taxed at the maximum rate.
MoneySmart, the official financial guidance site run by the Australian Securities and Investments Commission, outlines how super contributions interact with high-income scenarios — a starting point for any cricketer or high-income professional who has not yet mapped their contribution strategy.
Related: ZIM vs SA T20 2026: What Cricket's Prize Money Reveals About Athlete Wealth Planning | Eng vs Ind T20 2026: What Cricket's Millionaire Stars Should Know About Australian Wealth Management
Concrete Case: What a $320,000 Cricket Year Looks Like After Tax — With and Without a Wealth Adviser
Consider Thabo, a composite but financially realistic scenario based on a 31-year-old South African cricketer playing in Australia during the 2026 T20 World Cup.
Thabo holds a top-tier CSA central contract worth ZAR 3.8 million (AUD 316,000 at October 2026 rates). The ICC pays him AUD 18,500 in match fees for games played on Australian soil. An Australian sportswear brand pays him AUD 25,000 under a global endorsement deal, processed through its Sydney account. His total Australian-sourced income for the World Cup period: AUD 43,500.
Without structured advice: The ATO applies default non-resident withholding of 45% to the endorsement payment, treating it as personal services income without a treaty relief claim. That is AUD 11,250 withheld. His match fees are also liable to Australian tax assessment without treaty documentation in place. Combined, his unplanned Australian tax exposure is approximately AUD 18,000–22,000 on AUD 43,500 of income.
With a wealth management adviser acting before arrival: The adviser lodges a Tax File Number application and a treaty relief claim, classifying the endorsement payment correctly under the Australia–South Africa DTA at a 15% withholding rate (applicable to personal services income under treaty provisions). Match fees are structured through the ICC tournament agreement, reducing Australian-source liability. Total Australian tax on AUD 43,500 drops to approximately AUD 6,500–8,000.
The if/then: If Thabo arrives with no documentation, he loses AUD 18,000–22,000 to Australian withholding on a single six-week tournament. If his adviser acts three business days before his first game — the typical processing time for treaty documentation — the same income costs AUD 6,500–8,000 in Australian tax. The structural saving: AUD 11,500–15,500 on a single trip, before any superannuation optimisation, income protection, or investment structuring is counted.
Over a career spanning multiple tours to Australia, New Zealand, England, and the UAE, the cumulative difference exceeds AUD 100,000 — entirely legal, entirely based on correct documentation and timing.
What Bavuma's Moment Tells Australian Fans and High-Income Earners
Bavuma's TIME100 listing alongside the world's most bankable sports stars is a reminder that professional cricket has become a global wealth-generating machine — complex to navigate without professional guidance. But the financial planning principles extend far beyond elite cricketers.
Any Australian earning above AUD 180,000 per year — from salary, freelance income, consulting fees, or investments — faces the same structural challenge: peak-earning years are finite, marginal tax rates at the top are punishing, and the gap between those who structure their finances and those who do not compounds over decades.
The players who leave cricket with genuine financial security are not necessarily the highest earners. They are the ones who engaged a wealth management adviser early, made concessional super contributions consistently, protected their income, and diversified before the career peak passed.
When to Talk to a Wealth Management Expert
The Bavuma TIME100 news cycle is a natural prompt. For Australians watching the T20 World Cup this October — or any high-income earner whose annual income has recently crossed the AUD 150,000 threshold — the optimal time to engage a wealth management adviser is now, before the financial year's largest income events occur, not after 30 June when the options narrow.
An initial wealth management review with a qualified financial adviser typically costs AUD 1,000–3,000 depending on complexity. For a high-income earner, the tax savings available from a properly implemented strategy in year one routinely return AUD 10,000–30,000 — and that's before compounding over the following decade.
This article is for general informational purposes only and does not constitute personal financial advice. Consult a licensed financial adviser or wealth management expert for guidance specific to your circumstances.
