 Isabelle Torres
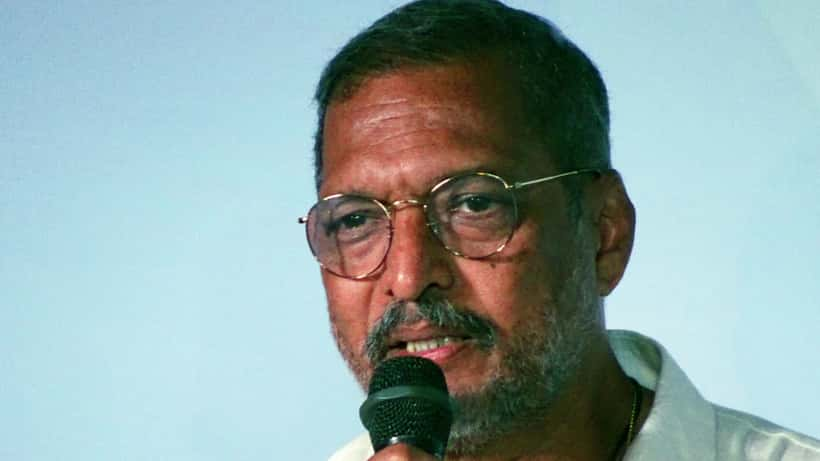
The news shook Bollywood fans worldwide on 8 October 2026. Nana Patekar, one of Hindi cinema's most formidable actors, died of cardiac arrest at his Goa home aged 75. Despite 45 minutes of continuous CPR by doctors at Manipal Hospital, he could not be revived. For the more than 700,000 Australians of Indian heritage who grew up watching his films — from Parinda to Welcome — the grief is immediate and personal. But his sudden, unplanned passing also raises a question that too many Indian Australians have left unanswered for years: if you hold assets in India and in Australia, who actually gets what when you die — and how long will it take?
A career that spanned five decades — and a family left to navigate two legal systems
Vishwanath Patekar was born on 1 January 1951 in Murud-Janjira, Maharashtra, and built one of the most distinctive careers in Hindi film. He won a National Film Award for Best Supporting Actor for Parinda (1989), and his roles in Krantiveer and Ab Tak Chhappan cemented his reputation as one of cinema's most intense performers. His death at 75, with no prolonged illness to prompt estate planning, is a stark reminder of how rapidly a family's legal situation can crystallise — and how different the outcome can be depending on whether the paperwork was in order.
For Indian Australians watching the tributes flow in, the question is uncomfortable but practical: is your own estate ready for both jurisdictions?
Why one will is almost never enough
India and Australia each operate entirely separate succession systems, and they do not recognise each other's documents automatically. An Australian will, even a properly executed one, has no legal authority over assets held in India. It cannot direct the transfer of a bank account in Mumbai, release a fixed deposit in Chennai, or facilitate the sale of an apartment in Pune.
Under Indian law, the applicable succession rules depend on religion:
- Hindu Succession Act 1956 — applies to Hindus, Sikhs, Jains, and Buddhists
- Muslim Personal Law — applies to Muslims
- Indian Succession Act 1925 — applies to Christians, Parsis, and those whose religious community is not separately codified
Each framework has different rules about who inherits movable and immovable property, what a surviving spouse is entitled to, and how an NRI (Non-Resident Indian) living in Australia can prove their claim. Without a valid Indian will, the family must apply to an Indian court for letters of administration — a process that can run to 18–36 months and generate significant legal fees in both countries.
Most cross-border estate lawyers who work on India–Australia matters recommend maintaining two coordinated wills: one Australian will covering all assets held here (property, superannuation, bank accounts, investments), and one Indian will covering all assets located in India (property, fixed deposits, shares, mutual fund units). The critical detail is precise cross-referencing language in each document — each will must explicitly state that it governs only the assets in its own jurisdiction and must not inadvertently revoke the other.
The capital gains trap most Indian Australians don't see coming
Neither India nor Australia imposes a traditional inheritance tax — a fact that many Indian Australians know and take comfort in. But the Australian tax picture is more nuanced than it appears. The Australian Taxation Office's guidance on inherited assets and capital gains tax makes clear that while the transfer itself is generally exempt from capital gains tax (CGT), the CGT obligation is deferred, not eliminated.
When the inherited Australian assets are eventually sold, CGT is assessed on the gain calculated from the original acquisition cost — not from the value on the date of inheritance. For second-generation Indian Australians inheriting property that parents bought in the 1990s, the embedded gain can be enormous. A Sydney property bought for AUD $320,000 in 1998 and worth AUD $1.8 million today carries a potential taxable gain of approximately AUD $1.48 million. At a marginal rate of 47% — after the 50% CGT discount for assets held over 12 months — the tax liability on a sale could still exceed AUD $350,000.
Structuring an estate properly before any transfer takes place — for example, through a testamentary trust that manages when and how assets are distributed — can materially reduce this exposure. It is not something to resolve after the death; it requires planning while both parties are alive and legally competent.
The concrete case: what happens to Priya's estate without a plan
Priya is a 54-year-old GP in Sydney, born in Pune, Australian citizen since 2002. Her mother still lives in Pune and owns an apartment worth approximately AUD $175,000 and ₹28 lakh (~AUD $52,000) in fixed deposits. Priya herself owns a joint investment property in Brisbane, purchased with her husband in 2004 for AUD $295,000 and now valued at approximately AUD $880,000.
Without cross-border planning:
When Priya's mother passes without an Indian will, Priya must engage an Indian lawyer to apply for letters of administration from the Pune District Court. The average timeline for this in Maharashtra is 24–36 months. Court fees, translation costs, and lawyer charges typically run to ₹1.5–3 lakh (roughly AUD $2,800–5,600). The Pune apartment also cannot be transferred to Priya unless she holds OCI (Overseas Citizen of India) status — without that, the asset may be frozen until a legal heir residing in India can be established.
On the Australian side, when Priya's Brisbane property eventually passes to her children, their future sale will be assessed against the original 2004 purchase price of AUD $295,000. At a projected sale value of AUD $1.4 million, the taxable gain is approximately AUD $1.105 million — or AUD $552,500 after the CGT discount. At their marginal tax rate, the liability could reach AUD $230,000 or more.
With two coordinated wills and basic estate structuring:
An Indian will, drawn up now by a qualified Maharashtra solicitor and naming Priya as sole beneficiary with a power of attorney for a trusted local executor, reduces the Pune probate timeline to 6–9 months and eliminates the uncertainty about who holds legal authority over the fixed deposits. For the Brisbane property, a testamentary trust structured to distribute income over several years — rather than triggering an immediate deemed disposal — can reduce the CGT liability by tens of thousands of dollars.
Total cost of this cross-border estate planning, coordinated between an Australian estate lawyer and an Indian succession lawyer: approximately AUD $4,500–8,000 in professional fees across both sides. That is less than 0.5% of the combined estate value — and a fraction of what disorganised succession typically costs in time, legal fees, and avoidable tax.
The if/then rule is simple: if Priya and her mother have no valid wills in place in either jurisdiction, then the Indian court process defaults to the most administratively complex path and the Australian CGT exposure defaults to the original cost base. If both wills are in place now, the timelines compress, the costs are predictable, and Priya's children do not inherit a legal problem alongside the property.
Indian property restrictions: what non-residents cannot do
One additional complexity that catches many Indian Australians off guard: Indian real estate has specific rules about who can hold and sell it. Under the Foreign Exchange Management Act (FEMA), a non-resident — including an Australian citizen of Indian origin without OCI status — generally cannot purchase agricultural land in India, and may face restrictions on holding residential or commercial property received by inheritance if the transfer is not properly documented.
Agricultural land inherited from Indian parents is the most restrictive category: it can only be transferred to an Indian resident. If the deceased owned farmland and the intended beneficiary lives in Sydney, a lawyer in both jurisdictions will need to determine whether the asset can be lawfully inherited or whether it must be sold to an Indian-resident buyer.
Checking OCI card status and confirming which categories of Indian property you are lawfully permitted to hold — before any inheritance event — is a task that takes weeks, not months. Leaving it to after the death means doing it under duress.
Three steps to take before the next crisis
Nana Patekar's death at 75 was not anticipated. Most estate crises are not. Here is what Indian Australians holding assets in both countries should do now:
Map every asset by jurisdiction. List each bank account, property, fixed deposit, mutual fund, superannuation fund, and share portfolio — noting the country where it is legally held and the approximate current value.
Confirm whether you have valid, current wills in both Australia and India. An Australian will that is more than five years old may not reflect current assets. An Indian will that was drafted in India before you moved to Australia may not function correctly for an NRI estate.
Consult a lawyer who handles cross-border succession. One who understands both Australian estate law and Indian personal law can draft coordinated wills, model the CGT implications, and flag any property-transfer restrictions — before they become expensive problems.
As the tributes pour in for Nana Patekar, his legacy on screen is secure. The inheritance he leaves his family — and the questions his sudden passing raises for Indian Australians everywhere — is a reminder that the one document most people delay is the one their family will need most.
For personalised guidance on India–Australia estate planning, Expert Zoom connects you with estate and succession lawyers who understand both legal systems. Earlier this year, a similar question arose when Tim Curry's sudden death without an updated Australian estate plan prompted many Australians to review their own wills — the same questions now apply for Indian Australians with assets in both countries.
YMYL Disclaimer: This article is for general informational purposes only and does not constitute legal, tax, or financial advice. Succession law and tax treatment vary by jurisdiction and individual circumstances. Please consult a qualified estate lawyer in both Australia and India before making any decisions about your estate.
