 Olivia Thompson
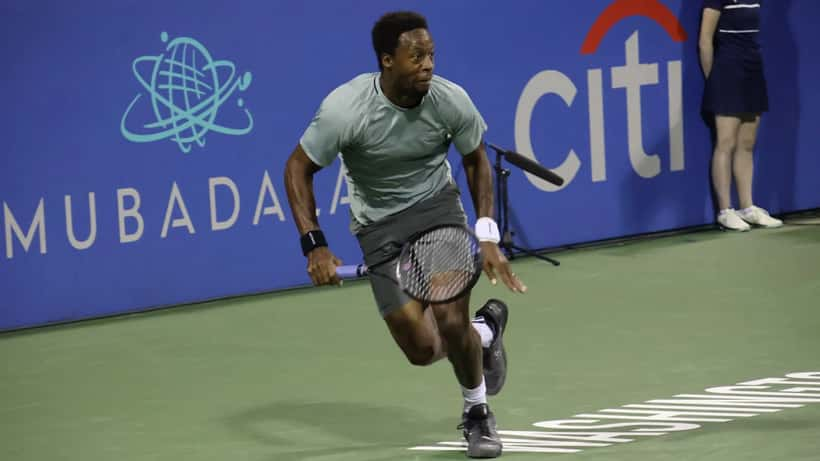
Gaël Monfils, the 40-year-old Frenchman who reached a career-high world No. 6 in 2016, appears to have retired from professional tennis. The International Tennis Integrity Agency (ITIA) listed him as inactive from 5 October 2026, and confirmed the change to Reuters and AFP on 14 October. Monfils has not publicly confirmed the decision himself, according to Field Level Media.
What we know about Monfils's exit
Monfils had said that 2026 would be his final season. He had a wild card for the Paris Masters in early November, which was expected to be his last match at home. Instead, his final appearance now looks to be a second-round loss to Learner Tien at the 2026 US Open.
On 14 October, organisers of the Lyon ATP 250 said he had pulled out of an exhibition with Jo-Wilfried Tsonga, Gilles Simon and Richard Gasquet for personal reasons. Reports also say he has signed with a Swiss company to work in wealth management.
He leaves with 13 ATP singles titles and Grand Slam semifinals at the 2008 French Open and the 2016 US Open. Being listed as inactive means he is no longer subject to anti-doping rules and cannot enter tournaments. As with Serena Williams, a comeback would require six months of availability for drug testing, according to the same report.
Why a sudden exit matters for the money
Most coverage focuses on the sporting legacy. The financial side deserves attention too, because Monfils's case shows what happens when a planned, staged retirement turns into an abrupt one.
A planned farewell tour comes with scheduled appearance fees, sponsor activations and a known last paycheque. An abrupt stop can pull those dates forward, cancel them, or trigger clauses in sponsorship contracts that were written around an expected playing career.
Australians in a similar position, whether athletes, tradies who sell a business, or professionals leaving a high-paying role early, face the same question: how do you turn a few high-earning years into decades of income?
What a wealth manager looks at first
Income from a short, intense career is lumpy. A licensed financial adviser would typically start with four things.
First, the income stream that stops. Prize money, appearance fees and endorsements often end together. Contracts should be checked for termination or "retirement" clauses.
Second, the tax position on the final year. In Australia, the timing of income and the sale of assets can change the tax payable materially. A person who stops work in October can still have a full financial year of income to manage by 30 June.
Third, superannuation. Self-employed people and sportspeople paid through companies often have thin super balances for their age. Concessional and non-concessional contributions, and carry-forward unused cap amounts, can help catch up.
Fourth, the next career. Moving into financial services, as Monfils is reported to be doing, brings its own obligations. In Australia, anyone giving personal financial advice must be a registered, qualified adviser, which you can check on the Financial Advisers Register.
Expert take: sequencing beats chasing returns
Advisers tend to agree that the order of decisions matters more than any single investment. Build a cash buffer first, usually covering 6 to 12 months of spending. Then deal with debt and insurance. Only then commit to long-term investing.
A sudden retirement also exposes gaps in insurance. Income protection generally stops being available once you no longer earn a work income, so cover decisions should be made before the stop, not after.
A worked example: the early stop in practice
Consider a hypothetical Australian professional athlete, 38, who earns $400,000 a year, with $150,000 in super and a $600,000 mortgage. She planned to play until the end of the 2027 season but suddenly stops in October 2026.
If her income falls to $0 and her household spends $120,000 a year, a 12-month buffer means she needs $120,000 in accessible cash. If she only has $60,000, she has about 6 months before she must sell investments or draw on the mortgage offset.
Now the tax angle. If she has already earned $200,000 between 1 July and her last match, her taxable income for the 2026-27 year is capped near $200,000 unless she earns more. If she then sells an investment property with a $150,000 capital gain, held longer than 12 months, a 50% discount applies, so only $75,000 is added to income. That takes her to about $275,000 taxable, which is a materially different outcome from selling in the next financial year when her income could be near zero.
So the if/then logic is simple. If income has stopped mid-year, then the cheapest time to realise a large gain may be this financial year or next, depending on what other income is expected. A qualified adviser can model both options in an afternoon, and the difference can reach tens of thousands of dollars.
The identity shift behind the numbers
Money decisions after a career ends are rarely only about money. Athletes and other people who retire early often describe losing structure, status and a daily routine at the same moment their income changes. That combination leads to rushed choices: buying property, backing a friend's business, or switching into a new industry before the budget is settled.
A common adviser rule of thumb is to avoid irreversible commitments for the first few months after a large life change. Monfils's reported move into wealth management suggests a planned second act, but even a planned second act usually starts on a lower income than the playing years.
For readers who want a broader view of how elite tennis income translates into long-term planning, our earlier piece on what every Australian can learn from Medvedev's US Open run covers prize money and tax timing in more detail.
Questions to put to an adviser
Before a first meeting, it helps to bring a short list. Ask how the adviser is paid, whether they are paid commissions, and what they are required to do in your best interests. Ask for a written statement of advice for any significant recommendation. Ask what happens to the plan if your income is zero for 12 months, not only if it grows.
Most importantly, ask the adviser to show you the downside case. A plan that works only when markets rise and income resumes on schedule is not a plan for an abrupt career stop.
Also keep records. Appearance fees, sponsorship payments and any overseas income can involve foreign tax paid, residency questions and currency conversions. A tidy folder of contracts, payment summaries and tax documents saves hours of adviser time and often reduces the bill.
What to do now
Whether you are an elite sportsperson or simply facing an unexpected exit from work, take these steps:
- List every income stream that ends, with the date and the contract clause behind it.
- Calculate your monthly spending and set a cash buffer target.
- Ask a licensed adviser to model the tax impact of timing asset sales and super contributions.
- Review insurance before income stops.
- Check any adviser against the official register before you share financial details. The government's MoneySmart service explains how to find and check a financial adviser.
This article is general information, not personal financial or tax advice. Speak with a licensed financial adviser or registered tax agent about your own circumstances.
If a career change or an early retirement is on your mind, Expert Zoom connects you with a vetted wealth management expert who can map out your next 12 months.
