 Olivia Thompson
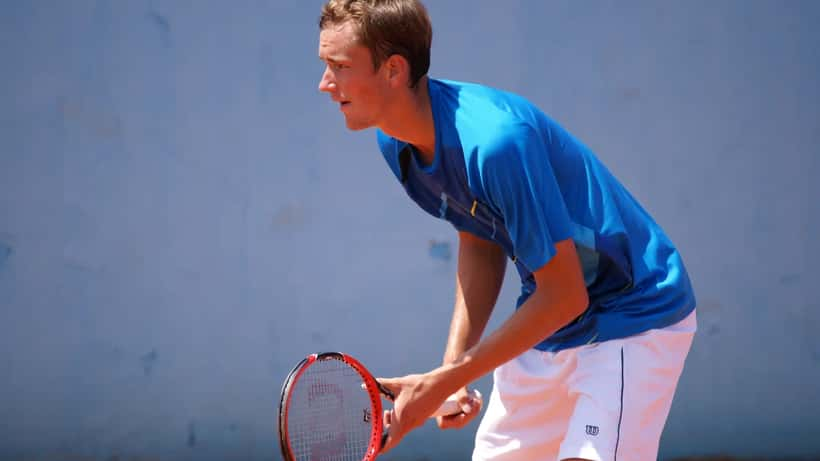
Daniil Medvedev rolled into the fourth round of the 2026 US Open on 4 September. He is there for the seventh time in ten appearances — confirming he still belongs among the world's best at 30. The No. 7 seed has endured what he himself has described as the most difficult two seasons of his career. Yet at Arthur Ashe Stadium this fortnight, he has rediscovered his form and his enjoyment of the game. With the tournament's total prize pool at a record $108 million — a 20 per cent jump on 2025 — his run already guarantees a six-figure payday. For Australian tennis professionals watching from the locker room or the Challenger circuit, Medvedev's story this week carries a subtler lesson. Peak athletic income can disappear faster than it arrives. The time to plan for that reality is now.
Still Competing at the Top: What Round 4 Signals
Medvedev dispatched American wildcard Sebastian Gorzny in straight sets in Round 2 and has looked, round by round, like the player who ended Novak Djokovic's calendar-year Grand Slam bid in 2021. He told reporters at Flushing Meadows this week: "Being on the court, I was happy with my level. I love this court and I love you guys." That remark drew attention for what it implied — that over the past two years, that happiness had been harder to find.
The 2026 US Open prize structure makes each round consequential. A quarterfinal result earns $780,000 in singles. Even a Round of 16 exit guarantees a substantial payday. These are real sums. But they arrive in peaks and troughs across a career that, for most players, has a clearly defined ceiling by the mid-thirties. Medvedev's own trajectory shows this clearly: after winning the 2021 US Open and reaching world No. 1 in early 2022, two seasons of inconsistency followed. That is how quickly income and ranking can shift, even for a player of his calibre.
The Earnings Curve Athletes Are Reluctant to Discuss
ATP tour data shows that prize money earnings for male professional tennis players tend to peak between the ages of 26 and 32. After 32, physical resilience declines gradually. Ranking points become harder to defend as recovery time lengthens. Sponsorship and endorsement contracts — often the largest income component for elite players — are renegotiated sharply downward, or terminated, when rankings slip. For Australian tennis professionals operating between ATP rankings 50 and 150, the window is even more compressed. A player earning $400,000 to $700,000 in a strong season may sustain that level for four to seven years at best.
The challenge is what comes after. According to the Australian Bureau of Statistics, the average Australian retires at around 64. That means a 30-year-old professional athlete faces more than three decades of post-peak financial life to fund. The mismatch between the earning window and the retirement horizon is one of the defining financial challenges of professional sport — and most players address it far too late.
Three Priorities a Wealth Manager Flags at 30
Australian wealth managers who specialise in high-income professionals consistently identify three levers that matter most in the 28-to-33-year window.
The first is superannuation optimisation. The Australian Taxation Office sets the concessional contributions cap for 2025–26 at $30,000. Contributions within this cap are taxed at just 15 per cent inside a super fund. Compare that with the 45 per cent marginal rate applied to individual income above $190,000. For an athlete generating several hundred thousand dollars in prize money, that differential is substantial. Non-concessional contributions — after-tax money deposited directly into super — allow up to $120,000 per year, or up to $360,000 in a single year under the three-year bring-forward rule. A self-managed superannuation fund (SMSF) can add further investment control, though compliance obligations require qualified advice.
The second priority is income diversification. Relying solely on prize money and a small suite of sponsorships creates dangerous concentration risk. Wealth managers typically recommend building passive income streams — investment property, equities, or managed funds — during peak earning years. The goal is ensuring the end of a playing career does not also mean the end of meaningful income.
The third lever is the least discussed: income averaging under Division 405 of the Income Tax Assessment Act 1997. This provision explicitly covers individuals with "special professional income," a category that includes sportspeople. It allows athletes to apply for a tax offset on irregular, lumpy prize-money income by spreading it across a five-year period for tax calculation purposes. In a year where prize money spikes well above average, this mechanism can generate a meaningful reduction in the final tax bill — but only if the right advice is in place before the income is assessed.
The Scenario That Makes the Numbers Real
Consider an Australian ATP professional in the 2025–26 financial year who has a breakthrough season. They earn $500,000 in prize money across the Australian Open, two ATP 500 events, and a quarterfinal run at another Grand Slam. Under standard individual income tax rates, income above $190,000 is taxed at 45 per cent. That means approximately $140,000 in tax on the top portion of their earnings alone, before the Medicare levy.
Now apply a structured approach. The player maximises their $30,000 concessional super contribution. Tax on that amount drops from 45 per cent to 15 per cent — a direct saving of $9,000. They then direct $120,000 of after-tax earnings into a non-concessional super contribution, moving those funds into an environment where earnings are taxed at 15 per cent instead of up to 45 per cent. Finally, they apply the Division 405 income averaging provisions to reduce the effective rate on an exceptional prize-money year.
Over five years of $500,000 annual prize money, this structured approach versus an unstructured one could produce an additional $250,000 to $380,000 in after-tax wealth by age 40. That gap compounds further across subsequent decades inside a superannuation environment. The difference between acting at 30 and waiting until 35 is not just five years of contributions — it is the loss of compounding growth on funds never efficiently deployed.
For Australian players navigating exactly these decisions — from Popyrin's Geneva Open prize money run to the irregular income question that faces a lucky loser at Roland Garros — the pattern is consistent: structured advice early produces materially better outcomes than reactive planning later.
What Watching Medvedev Should Prompt You to Do
Medvedev reaching the fourth round of the 2026 US Open at 30 is a sporting achievement. But for Australian tennis professionals, his week at Flushing Meadows also crystallises a financial question worth sitting with: what is your plan for when the prize money peaks and then contracts?
Australia produces a steady stream of ATP and WTA professionals in their late twenties and early thirties. Many are generating meaningful prize-money income without yet having engaged a wealth management specialist with experience in professional sport. The Australian Open's record 2026 prize structure means even first-week Grand Slam exits now produce six-figure paydays. That income deserves a plan proportionate to what is at stake.
The right moment to start is not after the ranking slips or the contract expires. It is now — during the peak — when there is still maximum choice about how income is structured, invested, and protected. A specialist in athlete wealth planning on Expert Zoom can assess your specific earning profile, superannuation position, and tax exposure, and build a plan calibrated to the precise length of your competitive window.
This article is for general informational purposes only and does not constitute financial, tax, or superannuation advice. Readers should seek independent advice from a licensed financial adviser before making any investment or superannuation decision.
format_used: Expert reaction
