 Isobel Fraser
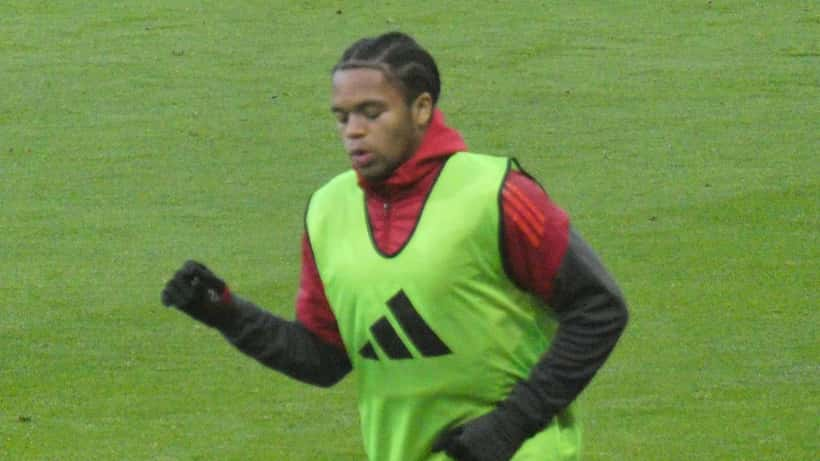
Rio Ngumoha became England's third-youngest competitive debutant on 1 October 2026, stepping off the bench in the 71st minute as the Three Lions beat Czechia 2-0 in a Nations League clash. Just 18 years and 31 days old, the Liverpool winger joined Wayne Rooney and Jude Bellingham in an elite club — and with that landmark appearance came a spotlight not just on his football ability, but on the financial decisions that will define the next decade of his life.
A Record That Rewrites the History Books
On a cool autumn evening in Prague, Ngumoha collected a pass from Phil Foden and drove at the Czech defence in a cameo lasting fewer than 20 minutes. It was enough to etch his name beside two of England's most commercially successful players ever. Wayne Rooney earned an estimated £160 million over his career; Jude Bellingham's image rights deals alone are reportedly worth tens of millions annually. At 18, Ngumoha has just knocked on the same door.
At Liverpool, the teenager is believed to be earning approximately £25,000 per week — around £1.3 million per year — after signing his first professional contract in late 2025. Negotiations for a new, significantly more lucrative long-term deal are at an advanced stage, with Bayern Munich and Arsenal both closely monitoring the situation. Once that deal is signed, his weekly wage could realistically double or treble his current terms, sources close to the club have indicated.
The question is no longer whether Ngumoha will become wealthy. The question is whether he will stay wealthy.
What £25,000 a Week Actually Looks Like After Tax
England's income tax system is unforgiving at the top end. A footballer earning £1.3 million per year falls squarely into the highest rate bracket:
- Income tax at 45% on earnings above £125,140 (HMRC 2026-27 rates)
- National Insurance contributions of 2% on earnings above £50,270
- Agent fees typically deducted at 3-5% of gross salary
Before a single luxury has been purchased, Ngumoha is taking home closer to £680,000 to £720,000 per year net. That remains a life-changing sum — but it is approximately half what is printed on his contract, a reality many young athletes encounter only after their first payslip. "The gross figure is what players celebrate," one independent financial adviser told The Athletic in 2025. "The net figure is what they actually have to work with — and if nobody sits them down before they sign, they're already behind."
You can estimate any salary's true take-home position using the official HMRC income tax calculator on gov.uk — a tool more young professionals should bookmark long before their agent does.
Three Financial Risks That Derail Young Athletes
Premier League history is littered with cautionary tales. The Professional Footballers' Association has repeatedly warned that a significant minority of retired players face financial difficulty within five years of hanging up their boots. For young players, the risks cluster around three areas.
Lifestyle inflation happens fast. A player earning £25,000 a week at 18 may feel entirely justified buying a £300,000 car and a £1.5 million property. By 22, expectations grow — and so do fixed costs. When earnings plateau or drop through injury, those fixed costs don't shrink.
Short career windows are a structural reality of the game. The average Premier League career lasts fewer than eight seasons at the elite level, according to CIES Football Observatory data. An injury at 26 can end a career that once seemed limitless, leaving decades of post-football life to fund from savings accumulated in a narrow window.
Image rights structures can go badly wrong without expert guidance. Many top-flight players legitimately channel image rights income through a personal services company, taxed at the 25% corporation tax rate rather than the 45% personal income tax rate. But when these structures are set up incorrectly or fall foul of HMRC scrutiny, the consequences are severe — as several high-profile footballers have discovered at tax tribunals. The structure must be built correctly from the start, not retrofitted years later. Similar challenges have faced players like James Trafford, whose transfer decisions highlighted the importance of early financial planning for young athletes at pivotal career moments.
If Ngumoha Signs a New Deal Worth £50,000 a Week — Two Very Different Futures
Suppose Ngumoha signs a new five-year contract at £50,000 per week — a plausible figure given Liverpool's stated desire to reward their most exciting academy graduate in years, and the competitive interest from Munich and North London. Over five years, gross contract earnings total approximately £13 million.
Path A — without professional financial advice:
- Income tax and NI reduce the net amount to roughly £6.8 million
- Lifestyle costs (mortgage, cars, family support, agent fees, security, travel) absorb a further £2 million conservatively
- Pension contributions: £0 — the most common outcome for players who have never been guided toward long-term planning
- Net savings at the end of five years: approximately £4.5–4.8 million
Path B — with a qualified independent financial adviser from day one:
- A personal services company for image rights (assumed to be 20% of total earnings) taxed at 25% corporation tax rather than 45% income tax saves approximately £80,000 per year — over £400,000 across the contract
- A Self-Invested Personal Pension (SIPP) funded at the annual allowance of £60,000 per year generates a 45% tax relief — equivalent to a £27,000 annual Government contribution on top of his own
- ISA contributions of £20,000 per year invested in diversified index funds, compounding at a conservative 6% annual return, accumulate approximately £118,000 over five years — completely sheltered from capital gains or income tax
The difference between Path A and Path B: between £900,000 and £1.2 million in additional wealth over five years — achieved not through extra earnings, but through structuring and timing.
If Ngumoha delays financial planning until his late twenties, then the compounding advantage of a decade-long SIPP from age 18 cannot be recovered. A seven-year head start, assuming a 7% annual return, generates roughly £500,000 more in retirement wealth than starting at 25 — a sum that grows larger with every year of inaction.
For context, Felix Nmecha's experience navigating a €10 million deal illustrated similar structural decisions — underscoring that these challenges are not unique to British players, but universal to any young professional receiving a sudden, significant uplift in earnings.
What Qualified Advisers Recommend for Young High Earners
Financial advisers who specialise in professional athletes consistently outline the same sequence of priorities, regardless of whether their client has just made their England debut or simply received their first significant salary increase.
Understand your net position before you spend. Use HMRC's official tools to model what you actually take home. The shock of a first payslip is real, and planning should begin before the money arrives, not after.
Appoint an independent financial adviser regulated by the Financial Conduct Authority — crucially, not the same agent who negotiated your contract. An FCA-regulated IFA has a fiduciary duty to act in your interest. An agent's interests and your long-term financial health are not always identical.
Structure image rights from the outset. Setting up a personal services company is a well-established and entirely legitimate practice, but it requires qualified legal and accountancy advice before income begins flowing. Retrospective structuring creates HMRC exposure that early planning entirely avoids.
Automate saving before lifestyle adjusts to the new income. A standing order into a SIPP and an ISA, established in the first month of a new contract, removes the behavioural trap of spending first and saving whatever is left. Very little tends to be left.
Plan as if the career ends at 28. Not because it will — but because a financial plan built on the assumption of another decade of elite earnings is one that has not honestly reckoned with the statistical realities of professional sport.
Rio Ngumoha has written himself into the history of English football at an age when most young people are deciding their A-level results. The decisions he makes in the next twelve months — and the advisers he chooses to surround himself with — will determine whether that historic status translates into lifelong financial security. For any young professional entering a period of rapidly rising income, the lesson is the same: the best time to consult a financial expert is the moment before you think you need one.
This article is for informational purposes only and does not constitute financial advice. Consult a qualified, FCA-regulated financial adviser for guidance specific to your circumstances.
format_used: Expert reaction
