 Imogen Bennett
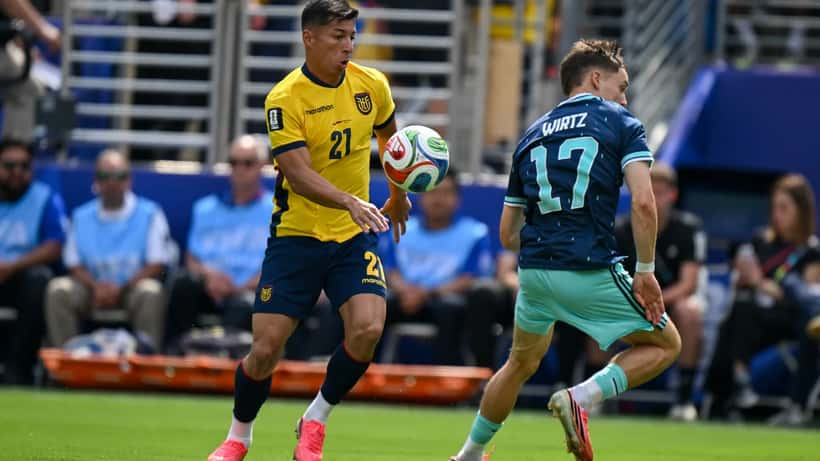
Fifteen months after arriving at Anfield in a deal worth up to £100 million, Florian Wirtz is trending across British football media for entirely the wrong reasons. Former Manchester United scout Mick Brown stated publicly this week that Liverpool would "definitely explore the possibility of getting back some of the transfer fee" paid for the German playmaker in the summer of 2025 — a stunning reversal for a player who was once considered one of Europe's most coveted talents. With just nine goal contributions across 44 Premier League appearances, and Germany's elimination in the Round of 32 at the 2026 FIFA World Cup in September, the 23-year-old's future at the club is now genuinely uncertain.
From Bundesliga Favourite to Premier League Question Mark
At Bayer Leverkusen, Wirtz was electric. He played a central role in Xabi Alonso's unbeaten Bundesliga title campaign, contributing directly to 18 goals across the 2023/24 season, earning plaudits from coaches and scouts across Europe. His profile — technically gifted, able to operate in tight spaces, consistently decisive in the final third — convinced Liverpool to smash their transfer record. The reported fee of £100 million placed him in the company of the most expensive players in Premier League history.
The adaptation to English football, however, has not gone to plan. Nine goal contributions in 44 appearances falls well short of what that level of investment demands. Germany's World Cup 2026 campaign — in which Wirtz contributed three assists across four matches before exiting in the Round of 32 — kept him in the headlines throughout the summer, but not always in the way he would have wanted. A difficult outing in Germany's shock defeat by Slovakia drew particularly sharp criticism from pundits on both sides of the Channel.
Reports now suggest that Bayern Munich are monitoring his situation ahead of a potential approach in 2027, with speculation that Liverpool could accept a fee significantly below their original outlay — in the region of £60-70 million, according to FootballTransfers.
Career Risk Hits Every Sector — Not Just the Premier League
For wealth management professionals in the UK, the Wirtz saga is not an unusual story. What changes between cases is the scale, not the structure. A professional at the peak of their perceived market value accepts a large career move, builds a financial life around projected income, and then finds that income is suddenly at risk.
Wirtz earns an estimated £200,000 per week at Liverpool. Even at that level — or precisely because of it — the risks of career concentration are significant. If his market value has dropped from £100 million to £60-70 million in 15 months, as reports suggest, the downstream effects on endorsement deals, image rights arrangements, and long-term earning projections are real and measurable.
The principle wealth advisers consistently draw from situations like this: income today is not guaranteed income tomorrow. The more visible, performance-dependent, or contract-specific your earnings, the more exposed you are when performance dips, market conditions shift, or a new employer decides to cut their losses. This pattern is familiar to the Financial Conduct Authority (FCA), which explicitly recommends regulated financial advice at major career transition points — including high-value job moves — rather than only at the point of retirement planning.
As we explored in our analysis of how Premier League transfers affect financial decision-making, large one-time career moves carry underappreciated risks that extend well beyond sporting performance. The Wirtz situation makes those risks vivid in a way that pure numbers rarely do.
The Concrete Case: When a High-Salary Contract Hits an Exit Clause
Consider a scenario that wealth planners encounter with regularity in the UK. A senior fund manager in London accepts a position at a US-headquartered asset management firm expanding into Britain, on a total package worth £250,000 per year — including a base salary of £180,000, a discretionary bonus of up to £50,000, and unvested equity worth approximately £80,000 at grant date.
The contract includes an 18-month performance review clause, triggered if the European division does not reach 70% of its revenue target within that window.
Twelve months in, revenue sits at 58% of target. The clause is invoked, and the fund manager's employment is terminated with six months' notice.
Under UK employment law, the manager is entitled to their notice period at full salary — approximately £90,000 gross. Pension contributions during gardening leave, however, may cease immediately depending on the scheme's terms, with the manager responsible for making their own contributions during that period. More critically: the unvested equity worth £80,000 is forfeited entirely, because the company's scheme requires 24 months of continuous service to qualify for good-leaver status.
If the termination had come at month 25 rather than month 12, the equity would have vested and the financial picture would have been roughly £80,000 better. If the manager had built an emergency fund of six months' take-home pay — approximately £90,000 net in this bracket — the transition would be survivable. Without it, a professional earning £250,000 per year can face a genuine liquidity crisis within weeks of departure, with a mortgage, fixed household costs, and potential private school fees continuing regardless.
This is the financial structure beneath the Florian Wirtz headline. The gap between what he was worth when he signed and what the market may offer now is not abstract — it is a specific number, and every financial decision from endorsement structuring to property purchases should have been made with the possibility of that gap in mind.
What UK Wealth Advisers Recommend at High-Income Career Transitions
The FCA's guidance on financial resilience identifies three consistent vulnerabilities among high earners facing sudden career disruption: insufficient liquid reserves, over-reliance on a single employer's pension scheme, and absence of income diversification.
For anyone in a position similar to Wirtz's — a professional with a large salary, performance-contingent bonuses, or a career move made at peak market value — the immediate priorities a qualified wealth manager would address are the following.
Liquidity: Can you meet six to twelve months of fixed outgoings entirely from liquid savings, without touching pension assets or investment portfolios at an unfavourable moment? For high earners, the answer is often no — a six-figure salary does not automatically produce a six-figure emergency fund, particularly where lifestyle costs have scaled with income.
Pension structure: Is your pension tied to your employer's defined contribution scheme, or does it sit in a self-invested personal pension (SIPP) you control independently? In a career transition, the cost and timing of a transfer can affect the final pot materially, and understanding the mechanics before a crisis is essential.
Income diversification: A professional earning above £100,000 annually with no income source outside their primary employment is carrying a level of concentration risk that most independent advisers would recommend reducing. Dividend-generating investments, buy-to-let property, or structured savings outside employer vehicles are not luxuries at this income level — they are risk management.
The Right Time to Plan Is Not During the Crisis
The most important detail in the Wirtz story is timing. When he signed for Liverpool in June 2025, he was among the most sought-after players on the planet. That was the moment to build a financial plan that could withstand a difficult season, a long injury absence, or a transfer at a significant loss. Waiting until the transfer rumours start means working with fewer options, less time, and higher emotional pressure.
The same logic applies to anyone who has recently received a promotion, accepted a large contract, or had a strong year at work. The moment of strength is precisely the moment to stress-test the plan. The broader Premier League transfer market in 2026 has produced several similar stories — high-value moves that did not deliver expected returns, and professionals on both sides of those transactions who were better or worse prepared depending on their planning.
Florian Wirtz will recover — he is 23 and has the talent to rebuild his reputation wherever he plays next. The financial principles his situation illustrates, however, are not unique to football, and they are not reversed by talent or previous achievement. Career risk is real at every income level. The professionals who navigate it successfully are, almost without exception, the ones who planned for it before it arrived.
This article provides general financial information for educational purposes only. It does not constitute regulated financial advice. For guidance tailored to your personal circumstances, consult a qualified Independent Financial Adviser or wealth management professional.
