 John Green
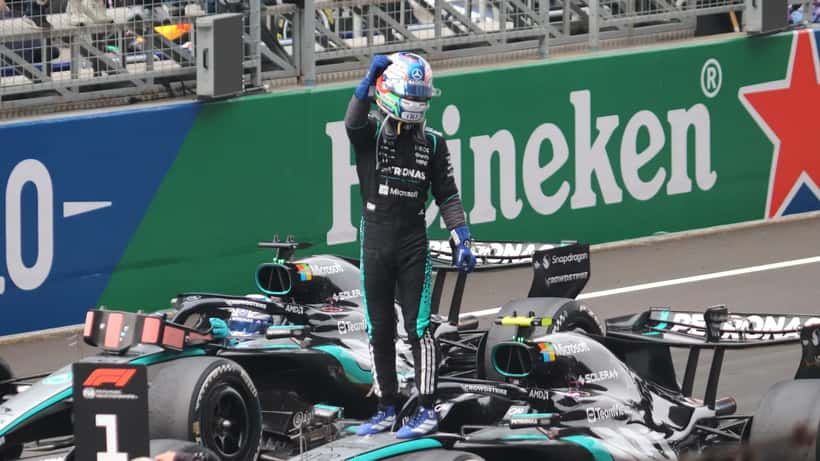
Formula 1's 2026 season has delivered one of motorsport's most compelling financial spectacles: a teenage Mercedes prodigy leading the World Drivers' Championship by 91 points heading into today's Bahrain Grand Prix, while the FIA enforces a $215 million budget cap that has fundamentally redefined how billion-dollar teams allocate resources. Behind the on-track drama lies a masterclass in structured financial discipline — one with surprisingly practical lessons for UK investors, business owners, and anyone managing a significant sum of money.
The $215 Million Figure Reshaping Motorsport Finance
The FIA's Financial Regulations were first introduced in 2021 at a ceiling of $145 million, a radical concept in a sport that had never known spending limits. For 2026, that ceiling rose to $215 million — an increase driven by three factors: cumulative inflation since inception, the extraordinary development costs of an entirely new hybrid power unit architecture, and expanded definitions of what counts as "performance spend."
The 2026 cars represent the biggest technical overhaul in over a decade. New V6 turbo hybrid units now deliver power on a 50/50 split between combustion engine and electric motor, running on 100% sustainable fuel. Meanwhile, two brand-new manufacturers — Audi and Cadillac — entered the grid for the first time in a generation, each spending hundreds of millions before a single race was run. According to the FIA's official Financial Regulations, driver salaries, senior staff pay, marketing, and travel costs remain outside the cap entirely. Only performance-related operational expenditure counts toward the $215m limit.
That single distinction — what is "inside" the cap versus what is not — is one of the most instructive financial architecture decisions in professional sport.
A Stat Grid: The Numbers Behind F1's Financial Era
| Metric | Figure |
|---|---|
| 2026 budget cap ceiling | $215 million |
| Original 2021 cap | $145 million |
| Cap increase since launch | +48% |
| Red Bull's 2022 breach penalty | $7m fine + 10% aero testing reduction |
| Kimi Antonelli's points lead (October 2026) | 91 points over George Russell |
| Number of new manufacturers entering in 2026 | 2 (Audi, Cadillac) |
The Red Bull precedent matters beyond motorsport. In 2022, the team exceeded the cap by approximately $7 million — around 5% over the limit. The FIA responded with both a financial penalty and a sporting sanction: a 10% reduction in aerodynamic testing allowance for a full year. The lesson for anyone managing structured capital is stark: breaching agreed financial boundaries has consequences that compound over time.
How F1 Teams Think About Structural Allocation
A championship-contending team like Mercedes — whose 18-year-old driver Kimi Antonelli has accumulated 722 points this season — doesn't simply "spend money on cars." It operates a ring-fenced framework. The $215m cap is the performance budget: every pound spent on parts, simulations, and track operations must be justified, tracked, and reported to an independent auditor.
Everything outside the cap — driver pay, senior leadership salaries, hospitality — is treated as a separate, discretionary budget category. The two pools never contaminate each other. This is precisely the structure that experienced UK wealth managers advocate for their clients: separating your "productive capital" from your "lifestyle capital," and ensuring each has its own management framework.
F1 teams also maintain mandatory cash reserves, governed by the Financial Regulations, to cover operational continuity. The smallest teams on the grid — often operating closer to the cap's lower boundaries — must demonstrate to the FIA that they can meet liabilities even mid-season. This requirement mirrors an essential personal finance principle: the emergency fund, held separately from investments, never raided for performance spending.
A Concrete Case: The £500,000 Windfall and the Budget Cap Principle
Consider this scenario, which reflects real situations UK wealth managers encounter regularly: a 34-year-old software engineer in Bristol receives a £500,000 cash payout after their employer is acquired. No inheritance, no lottery — a direct sum from a business exit event, taxed at income rates.
Much like an F1 team suddenly operating with a larger budget cap, the challenge is not whether to spend, but how to ring-fence each allocation so each category works independently.
If you invest 60% — £300,000 — in a diversified Stocks and Shares ISA-based portfolio in the 2026/27 tax year (annual ISA allowance: £20,000, maximised across multiple years via forward planning), then at an assumed 6% average annual return you could expect approximately £537,000 in ten years, within a tax-free wrapper.
If you place 20% — £100,000 — in a high-yield cash ISA or fixed-rate savings account at 4.3% (the average UK easy-access rate in Q4 2026, according to Moneyfacts data), then you maintain a liquid emergency fund generating £4,300 per year without touching capital — the direct equivalent of an F1 team's mandatory operational reserve.
If you fail to ring-fence the remaining 20% — £100,000 — for tax and professional fees before allocating lifestyle spending, then an HMRC investigation or miscalculated capital gains exposure could erode £40,000 or more of the total sum. Employment Income tax on a £500,000 business exit payout places the entire amount above the £125,140 additional rate threshold, triggering 45% income tax on the excess. The tax liability alone on such a sum, without specialist advice, can exceed £170,000 — a bill that surprises many first-time beneficiaries of windfall events.
An independent financial adviser or chartered wealth manager models all three pools simultaneously, adjusting for pension contribution opportunities, capital gains annual exemptions, and business asset disposal relief where applicable. This is exactly what F1's highly paid accountants do with the budget cap: not just spend within the limit, but optimise every category within its own framework.
For a UK parallel to George Russell's experience navigating F1's performance bonus structures, the professional sports world is full of high earners who discovered too late that earning at elite level requires an elite financial strategy.
What Happens When Financial Discipline Breaks Down
The 2022 Red Bull cost cap breach is a useful case study in what happens when financial management is reactive rather than proactive. The team didn't exceed the cap out of negligence — they simply failed to categorise certain catering and hospitality costs accurately within the reporting framework. A $7m error on a $145m budget: roughly 4.8%. On an individual financial level, a 5% error on a £500,000 windfall — £25,000 of misallocated funds — may not sound catastrophic. But the downstream effects of being underprepared for HMRC enquiries, pension annual allowance tapering, or inheritance tax implications can multiply that figure significantly over a decade.
The key insight from F1 is this: the most financially disciplined teams are not the ones who spend the most. They are the ones who understand exactly where every unit of resource is allocated, what return it generates, and when it crosses from one budget category into another. Ferrari, Red Bull, and Mercedes all employ teams of analysts whose entire function is to track this in real time.
For a private individual, that analytical function is replaced by a qualified chartered financial planner — someone who understands the interaction between pension contributions, ISA allowances, property ownership, and income tax bands.
Finding the Right Wealth Management Expert
Not all financial advisers are built for complexity. In the same way that a midfield F1 team's analyst team cannot compete with the depth of a factory operation, a generalist independent financial adviser may lack the specialist knowledge required for:
- Business exit events and business asset disposal relief
- Complex inheritance tax planning with multiple asset classes
- Offshore or international considerations (increasingly relevant for UK residents with global employment history)
- Pension annual allowance tapering for high earners above £260,000
The Chartered Institute for Securities and Investment (CISI) and the Personal Finance Society both maintain registers of qualified advisers by specialism. For significant life events — whether a business sale, a sudden inheritance, or a career shift — an initial consultation with a specialist can prevent decisions that look straightforward but carry five-figure tax consequences.
Disclaimer: This article is for informational purposes only and does not constitute regulated financial advice. You should seek advice from a qualified financial adviser before making investment or tax decisions.
F1's 2026 season — with its new cars, new rules, and a $215m financial framework keeping competitive ambition in check — is, at its core, a story about structure. The fastest teams are not necessarily the wealthiest. They are the ones who know exactly what to protect, what to grow, and when to bring in an expert to make sense of the boundary between the two. Consult a wealth management specialist on Expert Zoom to put the same discipline to work for your own financial situation.
