 Isobel Fraser
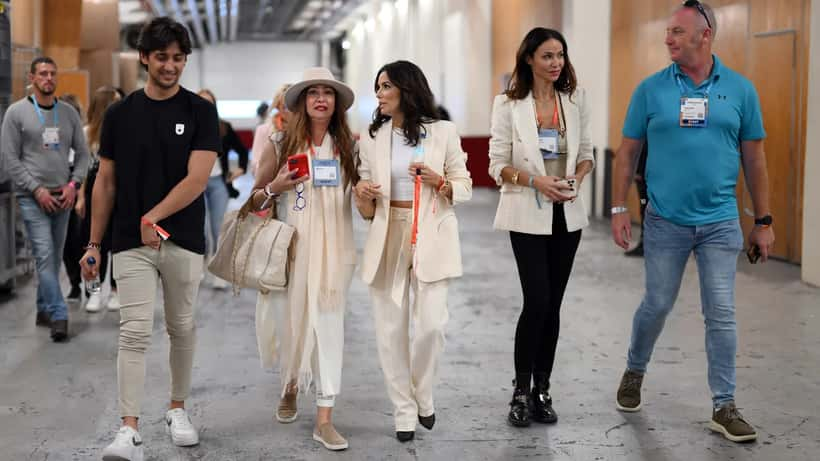
When Eva Longoria hosted the 15th anniversary of the Global Gift Gala in Marbella in July 2026, she was not a visiting celebrity lending glamour to someone else's event — she was the host in her own city. The 51-year-old actress has made the Andalusian coast her permanent home since relocating from Los Angeles in 2024, swapping Hollywood's hills for Spanish sunshine with husband José Bastón and their young son Santiago. For a growing wave of high-earning Brits watching from across the Channel, her move is more than aspirational: it is a prompt to call a wealth adviser.
A Move That Resonates Far Beyond Showbiz
Longoria's choice of Spain was not spontaneous. Bastón, a Mexican media executive with deep European business ties, had reasons to be closer to the continent. Spain's culture, language, and lifestyle aligned with the family's priorities. But for UK nationals considering a similar transition, the calculation in 2026 carries an additional, distinctly financial dimension — one that has become significantly more urgent since the UK government abolished non-domicile tax status in 2024.
That change removed a shelter used by thousands of high earners holding significant overseas assets, effectively raising the effective UK tax burden for many in the top income brackets. Spain, meanwhile, has been actively marketing its own preferential tax regime to international arrivals. According to reporting in The Local Spain from January 2026, the country is deliberately capitalising on the exodus of wealthy Britons seeking a more favourable fiscal environment — and the numbers of enquiries and relocations have accelerated sharply as a result.
What Wealth Advisers Want You to Know Before You Pack
At the centre of Spain's appeal for high earners is a 2004 fiscal mechanism officially known as the Régimen Especial de Impatriados — widely called the Beckham Law after the footballer whose move to Real Madrid first publicised it. In 2026, the regime remains among the most competitive in Europe for newly arrived earners.
Qualifying applicants pay a flat 24% income tax rate on Spanish-sourced employment income up to €600,000 annually, for a period of six consecutive tax years. For context, the UK's additional rate stands at 45% for income over £125,140, while Spain's own standard top rate reaches approximately 47% for residents earning above €300,000. The differential can be substantial.
Equally significant: most foreign-sourced income — including investment returns, dividends, and rental income from overseas properties — falls largely outside the scope of Spanish taxation during the regime period. For a UK professional with pension savings, an investment portfolio, and property rental income, the combined benefit across six years can run into hundreds of thousands of pounds.
The regime does, however, come with strict procedural requirements — and this is where wealth advisers consistently flag the greatest risk of costly error. The application must be submitted within six months of registering with the Spanish Social Security system. Applicants must also not have been Spanish tax residents at any point during the previous ten years. These conditions are firm: there are no appeals and no extensions.
A Concrete Case — When a Delayed Signature Costs £70,000
Consider a 44-year-old financial services executive based in Canary Wharf, earning £110,000 per year, who decides in January 2026 to join their partner who has already relocated to Seville. They register with the Spanish Social Security in February 2026. Uncertain about long-term plans — and distracted by the logistics of the move itself — they wait until September 2026 to formally apply for the Beckham Law regime.
The six-month submission window from a February 2026 registration closed on 31 August 2026. The September application is rejected.
In the 2026–27 tax year, the executive's equivalent €125,000 Spanish gross income now falls under the standard progressive scale. After standard deductions, the effective Spanish income tax rate on that income band rises to approximately 37% — 13 percentage points above the 24% Beckham rate they could have secured. On an annualised basis, that gap represents approximately €16,250 (roughly £13,800) in additional tax for that year alone. Across the five remaining years of the window they forfeited, the cumulative shortfall approaches £69,000.
A single consultation with a cross-border wealth adviser in January — before boarding the flight — would have flagged the deadline, clarified the registration sequencing, and preserved the full benefit. A procedural delay became a six-figure financial consequence.
The Three Wealth Moves Before You Fly
For UK nationals considering a Spanish relocation in the next 12 to 24 months, wealth advisers working in this space consistently identify three priority areas that require attention well before any departure date is booked.
1. Map your UK residency exit date with precision. Under the UK's Statutory Residency Test, the number of days spent in the UK in the year of departure determines whether you owe UK income tax on a full year's earnings or only a partial year. For high earners, leaving in April rather than September can represent a meaningful difference in UK liability. This is one calculation that genuinely rewards early planning.
2. Audit your pension and ISA exposure. UK Individual Savings Accounts do not travel with their tax protections intact. Once you become a Spanish tax resident, income and gains generated inside an ISA become declarable under Spanish tax law — the ISA wrapper offers no shield abroad. Similarly, UK pension withdrawals made after establishing Spanish residency may be partially taxable under the bilateral UK-Spain double taxation treaty, depending on the type of pension and the withdrawal method. Sequencing these decisions correctly before departure can preserve significant value.
3. Review overseas asset declarations from day one. If you already own a property in Spain — a holiday flat in Malaga, for example, which you have been letting out — your obligations change the moment you become a Spanish tax resident. The Modelo 720, Spain's overseas asset declaration form, carries heavy automatic penalties for late or incorrect submission. Getting this form right in year one is not optional.
For official guidance on the legal framework for British nationals living in Spain after Brexit, the UK government maintains an updated resource at gov.uk/guidance/living-in-spain.
The Timing Window That Most Movers Miss
There is a common misconception that the Beckham Law can be arranged during or after the relocation process. In practice, the six-month window begins from the date of Social Security registration — not from the date you decide to apply, and not from the date your Spanish lease begins. By the time many expats realise the deadline exists, it has already passed.
Wealth advisers who work specifically with UK-to-Spain relocations recommend beginning planning at least twelve months before the intended move. This creates the space to address the UK exit tax year position, restructure ISA and investment holdings where appropriate, and ensure the Spanish registration and application process runs in the correct sequence. Much of the work is coordination, not complexity — but it needs to happen in the right order and within a compressed calendar.
Finding the Right Specialist
The UK has a well-established community of advisers who specialise in cross-border transitions for British nationals moving to Spain. The best are regulated across both jurisdictions and understand the interaction between the two tax systems — not just one in isolation.
If you are planning a relocation in the next 18 months, the window for advance planning is open now. If you have already moved and are navigating your first Spanish tax filing — or managing an inheritance that crosses borders — specialist advice at this stage is considerably cheaper than correcting avoidable errors later.
The wealth management specialists on Expert Zoom have mapped the full financial picture that cross-border relocators in this situation face. The real lesson from watching Eva Longoria settle into Marbella life is not that Spain is beautiful — it is that the people who make the move successfully have the right team in place before they land.
This article is for informational purposes only and does not constitute financial or tax advice. Cross-border tax planning involves complex legal obligations specific to individual circumstances. Always consult a qualified, regulated wealth management adviser before making relocation decisions.
