 Isobel Fraser
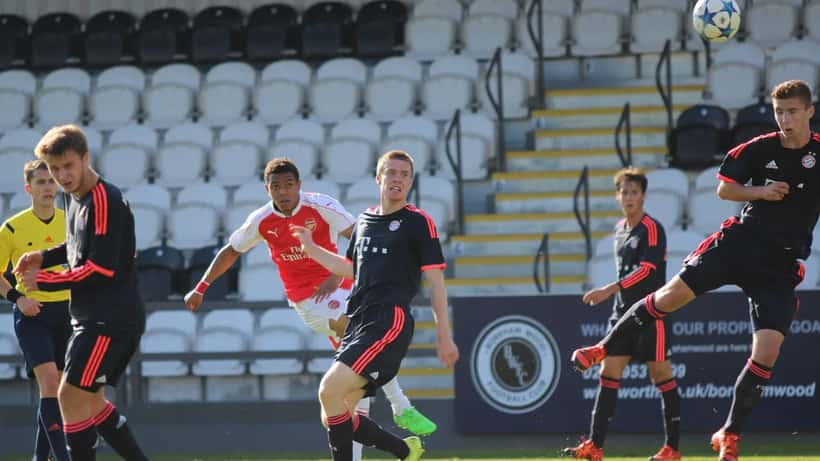
Donyell Malen scored twice for Roma against Real Madrid in the Champions League at the Stadio Olimpico on 14 October 2026, according to live coverage from VAVEL, leaving the Dutch forward at the centre of another big European night. The goals revive a question that goes well beyond football: what happens to your money when a large part of your pay depends on a milestone being hit?
What happened in Rome
According to VAVEL's live blog of the matchday-two league-phase tie, Marten De Roon put Roma ahead after 20 minutes before Kylian Mbappé levelled for Real Madrid in the 25th minute. Malen then struck at 50 minutes, with a shot that deflected off Federico Valverde and beat Thibaut Courtois, and again at 58 minutes, finishing a through ball after a VAR check upheld the goal.
The live reports were still updating at the time of writing, and sources differed on the final score, so this article does not rely on the result. What is not in doubt is Malen's form. Reports from early September 2026 credited him with 19 goals in 20 league matches since joining Roma from Aston Villa in January, including a hat-trick against Fiorentina.
Why a transfer clause matters to ordinary earners
Malen's move is a textbook example of pay and price tied to milestones. He joined on loan with an option to buy. Reports in May 2026, including beIN SPORTS coverage of the permanent move, said the option became an obligation after Roma secured Champions League football. He is reported to have signed a deal running to June 2030.
You can read more on how that clause worked in our earlier piece on Malen's Roma hat-trick and the contract clause behind it. The point for readers is simple: a single trigger turned an uncertain arrangement into a fixed commitment worth millions.
Most people will never negotiate a loan-to-buy clause. Many, though, have pay that moves on a trigger: a sales bonus, a retention payment, an earn-out on a business sale, a completion bonus on a contract. The tax and planning problems are the same in miniature.
The expert angle: bonuses are taxed at your top rate
A wealth manager or tax adviser will tell you the same thing first. A bonus is not taxed on its own. It is added to the rest of your income for the year, and the extra slice lands on top, where your highest rate applies.
For 2026/27, the personal allowance is £12,570 and the higher-rate threshold is £50,270, according to the government's income tax rates and bands page for England, Wales and Northern Ireland. Income above that is taxed at 40%, and above £125,140 at 45%. Scotland sets its own bands. The personal allowance is also withdrawn gradually once income passes £100,000, which creates a very steep effective rate in that range.
This is why timing and structure matter. A bonus paid in one tax year can cost noticeably more than the same money spread over two, and a lump sum can push someone over a threshold they would otherwise never touch.
A worked example: the £20,000 milestone bonus
Take a hypothetical sales manager in Manchester, paid a £48,000 salary, with a £20,000 bonus due if the team hits a target by March 2027. This is an illustration, not a forecast of any real person's tax bill.
- Without the bonus: £48,000 sits below the £50,270 threshold, so none of it is taxed at 40%.
- With the bonus: total income is £68,000. Taxable income after the allowance is £55,430, of which £17,730 sits above the higher-rate threshold. That slice is taxed at 40%, not 20%, so the extra tax on it is roughly £3,546 more than basic rate would have cost.
- If they pay £10,000 gross into a pension: the basic-rate band is extended by that amount. Only £7,730 is now taxed at 40%. Higher-rate relief on the £10,000 is worth about £2,000 more than the 20% already added at source, which they typically claim through self assessment or their payroll arrangement.
So the if/then logic is straightforward. If the bonus lands in the same tax year and takes the manager across £50,270, then a pension contribution, salary sacrifice or charitable gift can pull part of it back below the line. If the manager waits until the bonus is paid before asking, the options narrow, because contributions normally need to be made within the tax year, and annual pension limits and individual circumstances apply.
The same manager could also ask whether the employer can pay part of the bonus after 5 April 2027 rather than before it. That is a conversation to have in January, not April.
Bigger earners: the £100,000 trap
The effect is sharper for someone near £100,000. Every £2 earned above that level removes £1 of personal allowance, so the effective marginal rate in that band is far above 40%. A £15,000 bonus that moves someone from £95,000 to £110,000 can cost much more than the headline rate suggests. Pension contributions can again reduce adjusted income, but only an adviser who sees the whole picture can say how far that goes.
Other milestone payments worth a second look
Bonuses are only one version of the pattern. Business owners selling a company often receive part of the price as an earn-out, paid only if the firm hits agreed targets over the following years. Contractors can have completion payments tied to sign-off. Employees may hold share awards that vest on a date or a performance condition.
Each of these can be taxed differently. An earn-out may be treated as a capital gain in one structure and as employment income in another, and the difference in rate can run to thousands of pounds. The wording of the agreement, not the label on the payment, usually decides the outcome, which is why advice before signing is worth far more than advice after.
What an expert can do that a calculator cannot
Online calculators handle the arithmetic. They do not tell you whether your contract allows the bonus to be deferred, whether a share-based award is taxed as income or as a gain, or how a bonus interacts with student loan repayments, child benefit charges or a partner's income.
A wealth manager can map those interactions before the money arrives. A solicitor can read the bonus clause itself: what counts as the trigger, what happens if you leave, and who decides whether a milestone was met. Milestone disputes are common precisely because, like the Roma clause, they turn on a single defined event.
What to do now
- Check your contract or bonus letter for the exact trigger and the payment date.
- Work out your expected total income for the 2026/27 tax year, using the government's rates page above.
- Ask whether pension, salary sacrifice or timing options exist before 5 April 2027.
- If your income is near £100,000 or £125,140, get advice before the payment, not after.
This article is general information, not personalised financial or tax advice. Tax rules change and depend on your circumstances; speak to a qualified adviser before acting.
If a milestone payment is coming your way, a regulated wealth management expert on Expert Zoom can model the numbers with you and help you keep more of what you earn.
