 John Green
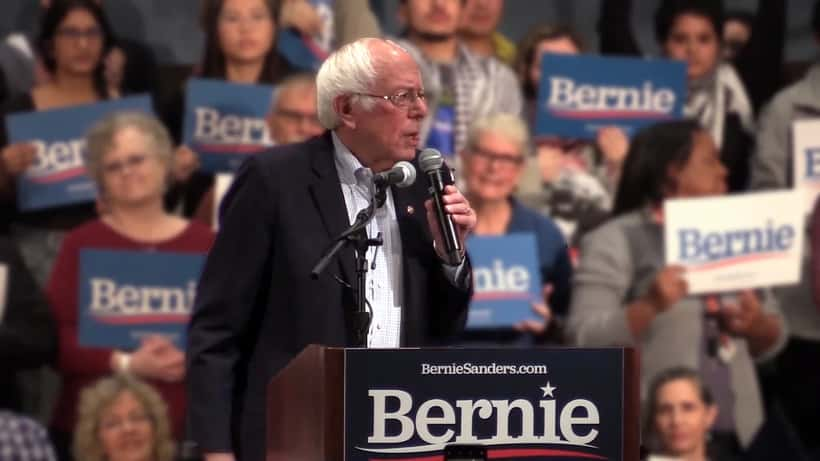
Bernie Sanders' move against Social Security debt seizures in the United States has landed with unusual resonance in the UK. His Stop Social Security Garnishment Act, introduced in August 2026, targets a practice that has quietly devastated tens of thousands of American retirees — the federal government withholding up to 15% of their Social Security payments to recover decades-old student loan debt and tax arrears. For British pension savers watching from afar, the question it forces into the open is an uncomfortable one: when old debts catch up with you in retirement, how much of your pension income is actually protected?
What Sanders Actually Proposed — And Why It Matters Beyond the US
Senator Bernie Sanders introduced the Stop Social Security Garnishment Act after a series of reports revealed that pensioners in their seventies and eighties were seeing their monthly Social Security payments slashed to recover government debts they had accumulated in some cases forty years earlier. In one documented case, a 74-year-old retiree had $300 removed from her monthly $1,100 Social Security payment to recover a student loan she had taken out in 1987.
Sanders described the practice as morally indefensible: "Seniors who spent their lives working and contributing to our society are now having their retirement security stripped away because of decades-old debt." His bill would permanently prohibit federal agencies from garnishing Social Security income for any purpose, placing it on the same protective footing as disability and veterans' benefits.
The political response was swift. CBS News polling published in September 2026 found that 73% of Americans across party lines support the prohibition — a rare example of bipartisan consensus in today's polarised Washington. Sanders has used that momentum to build broader support for progressive economic candidates ahead of the November 2026 midterms, framing retirement security as the defining economic issue of the decade.
The UK Equivalent: What Protection Does Your Pension Actually Have?
Wealth management consultants across the UK are fielding a surge of enquiries from clients in their late fifties who have read about the Sanders bill and suddenly want to know where they stand. The answer is that the UK framework is substantially more protective than the American one — but it contains important gaps that most savers are unaware of.
Under the Welfare Reform and Pensions Act 1999, most registered occupational and personal pension schemes carry statutory protection against creditors in bankruptcy proceedings. If you were declared bankrupt before reaching your pension's normal minimum access age, the pension pot itself cannot generally be seized by the bankruptcy trustee. This is a deliberately generous protection, designed to ensure that financial misfortune does not follow workers entirely into retirement.
However — and this is the gap that catches people out — the protection applies to the accumulated pot, not to the income drawn from it. Once you crystallise your pension and begin receiving monthly payments, that income has the same legal status as ordinary earnings. And ordinary earnings are subject to debt recovery in ways the pension pot is not.
For HMRC debts specifically, the position is particularly pointed. A formal HMRC demand that remains unresolved when a debtor begins taking pension income can result in attachment-of-earnings equivalent orders that redirect a portion of each monthly drawdown payment to HMRC before it reaches the pension holder's bank account. State Pension payments, while generally insulated from private creditor action, are not fully protected from government recovery for overpaid benefits in certain circumstances.
A Concrete Case: The £22,000 That Could Cost £54,000
Consider the situation facing a 58-year-old self-employed IT contractor in Leeds — call him David — who has a self-invested personal pension (SIPP) worth £210,000 and a deferred occupational pension from previous employment worth £87,000 in projected annual income of £4,200. He also carries an unresolved HMRC liability of £22,000, dating from a tax dispute covering the 2020-21 and 2021-22 tax years when his contracting income collapsed.
Under current rules, both pension pots are protected while they remain uncrystallised. However, David plans to begin pension drawdown at 60 — the new minimum access age under the Pension Schemes Act 2021 — to supplement reduced contracting income as he transitions toward full retirement.
Here is the if/then logic: if David begins drawing £1,800 per month from his SIPP at age 60 with the HMRC £22,000 still unresolved, HMRC can apply for recovery from his drawdown income at rates of up to 20-30% of monthly receipts. That means £360-£540 per month redirected to HMRC, reducing his effective monthly income to £1,260-£1,440. Over the period it would take to recover £22,000 at £360-£540 per month, David would lose between 41 and 61 months of full pension income — worth between £73,800 and £109,800 in total drawdown. The original £22,000 debt, if left unresolved until pension access, could ultimately cost him more than twice the debt amount in disrupted retirement income.
By contrast, if David reaches a time-to-pay arrangement with HMRC before age 60 — paying down the £22,000 over 24 months at approximately £917 per month while still earning contracting income — he retains full control of his pension drawdown from day one of retirement, protecting the entire income stream.
A wealth management consultant can model both scenarios and help clients like David determine whether early resolution, structured drawdown sequencing, or formal insolvency proceedings offer the best path to protecting retirement income. The maths are rarely intuitive, and the stakes are high.
Where Private Creditors Stand
For private debts — credit cards, personal loans, or unsecured business borrowings — the picture is more reassuring. A County Court Judgement (CCJ) does not give a private creditor direct access to pension drawdown income in the way HMRC recovery mechanisms potentially do, and a private creditor cannot attach the pension pot held within a registered scheme.
That said, private creditors are not without tools. Charging orders can be placed on other assets, and if the cumulative burden of private and government debt triggers formal insolvency proceedings, the interaction between pension protections, trustee-in-bankruptcy powers, and excess contribution unwinding rules becomes technically complex.
Under the 1999 Act, pensions accrued before bankruptcy are generally excluded from the bankruptcy estate. However, if HMRC or a trustee in bankruptcy can demonstrate that contributions were made with the specific intent of sheltering assets from creditors — particularly large lump-sum contributions made shortly before insolvency — those contributions can be unwound and recovered.
For anyone with defined benefit pension entitlements, the picture is different again. DB pensions, once in payment, are generally administered by scheme trustees under their own governance frameworks and are substantially harder for creditors to access than drawdown income from a SIPP or defined contribution arrangement.
Sanders' Bill and the Global Retirement Security Conversation
The Sanders bill has done something politically useful: it has made retirement debt protection a mainstream topic of conversation, not just a technical matter for insolvency practitioners. That shift in public attention is already being felt in the UK.
Searches for "pension protection from creditors" and "can HMRC take my pension" have risen sharply in August and September 2026, according to UK financial services analytics. The underlying anxiety is real: a generation of self-employed workers and small business owners, many of whom faced serious financial disruption during the pandemic years of 2020-22, are now approaching pension access age with unresolved legacy liabilities.
The gap between awareness and professional engagement remains wide. Financial wellbeing data published in the UK this year suggests that fewer than one in three adults aged 55-65 with unresolved debts above £10,000 have sought wealth management advice about the interaction between their pension and those liabilities. Most assume the pension is simply safe — and in many respects, it is. But "many respects" is not the same as "entirely," and the difference can be worth tens of thousands of pounds.
What to Do If You Are Approaching Pension Age with Unresolved Debt
If you are within ten years of pension access and carrying any form of outstanding financial obligation — whether to HMRC, a former business partner, or a private lender — the optimal window for professional intervention is now, not when drawdown begins.
Key questions to work through with a wealth management specialist include: whether your specific scheme type (SIPP, occupational DC, DB) affects the protection available; whether HMRC or DWP liabilities can be formally resolved before you crystallise your pension; whether drawdown sequencing strategies can reduce the income available to creditors in early retirement; and how your spouse's entitlements might be affected by any formal insolvency proceedings.
Bernie Sanders is fighting this battle for American retirees in Washington. In the UK, the fight is waged in the detail of scheme rules, recovery timetables, and drawdown strategies. Getting specialist advice before you reach the access age is the closest British equivalent to what his bill is trying to achieve by statute.
This article discusses general principles and does not constitute personalised financial or legal advice. Pension rules and debt recovery mechanisms depend on individual circumstances. Consult a qualified wealth management adviser for guidance specific to your situation.
