 John Green
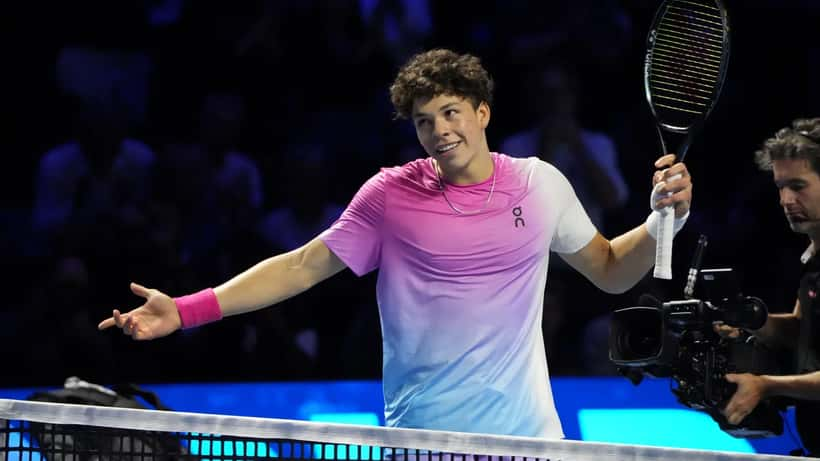
Ben Shelton is in the quarter-finals of the 2026 US Open facing Carlos Alcaraz, with a potential prize of over $675,000 on the line — his fourth major payday in a season that has already seen him lift titles in Dallas, Munich, Stuttgart, and Montreal. Since January 2026, the 24-year-old American has banked over $1.8 million in prize money alone, pushing his career total beyond $15 million. Yet his estimated net worth stands at roughly $4 million. That gap — between what elite athletes earn and what they retain — is a pattern wealth management professionals see repeatedly, and it carries lessons for anyone whose income is about to spike dramatically.
A Breakout Season With Real Numbers
Shelton entered 2026 already ranked in the world's top 15, but this year has been transformative. He claimed the ATP 500 title in Dallas in February, defeating Taylor Fritz. Two months later he took the Munich ATP 500 crown, then added his first grass-court trophy at the Stuttgart Open in June. He then defended his Canadian Open title in Montreal — earning $1.15 million from that event alone — before arriving at the US Open ranked No. 9 in the world.
Each title has come with a cheque, a tax event, and a set of financial decisions that most 24-year-olds are simply not equipped to navigate without professional help. Shelton's endorsement portfolio — which includes Rolex, On Running, Yonex, and Bose — adds another layer of contractual complexity on top of the prize money.
When asked about his quarter-final matchup with Alcaraz after dispatching Stefanos Tsitsipas in straight sets, Shelton answered with characteristic directness: "Special tennis." The same phrase might describe the financial acuity required to manage what happens next.
Why Sudden Income Creates Wealth Management Urgency
Most people encounter income growth gradually. A pay rise here, a promotion there. The financial system — PAYE, pension auto-enrolment, a modest ISA — handles the increments without demanding much attention.
That mechanism breaks down entirely when income jumps rapidly. Professional athletes, tech founders, authors with breakout bestsellers, and executives receiving large share vestings all face the same structural problem: the tax system and financial products are not automatically calibrated for sudden large income, and acting too slowly can mean a permanent, recoverable loss.
In the UK, this issue is acute. The income tax system charges 45p on every pound earned above £125,140 (the 2026 additional rate threshold, per HMRC guidance). For someone whose income crosses that threshold for the first time — whether they are a rising tennis professional, a contractor landing a lucrative project, or a consultant in a banner year — the default outcome without planning is to pay the maximum tax, retain the minimum, and lose the opportunity to use legal structures that require forward planning to activate.
The problem is compounded by timing. Pension contributions, for example, must be made in the same tax year the income arrives to offset it at the higher rate. You cannot go back to April 2025 once it is October. This is precisely the moment when a wealth management consultation is not a luxury — it is a financial imperative.
A Concrete Scenario: From £42,000 to £520,000 in One Year
Take a hypothetical young British athlete — a 26-year-old tennis professional from Hertfordshire who has ground through the Challenger circuit for four years earning approximately £42,000 annually. In 2026, they reach two ATP 500 finals, winning one, and receive a sponsorship deal worth £130,000. Their total income for the tax year reaches £520,000.
Without any wealth management intervention, the picture is stark. On £520,000 of income:
- Personal allowance: £0 (phased out entirely above £100,000)
- Tax on the first £50,270 at 20%: £10,054
- Tax on the next £74,870 at 40%: £29,948
- Tax on the remaining £394,860 at 45%: £177,687
- Total income tax: approximately £217,689
- National Insurance contributions (Class 4, at 2% above the upper threshold for self-employed): a further ~£5,600
- Agent commission at 15% of gross prize money (£390,000 × 15%): £58,500
- Net retained income: approximately £238,000 from £520,000 earned
Now, if the same athlete had consulted a wealth manager six months earlier — before the sponsorship contract was signed and before the season began — the structure looks different:
- Annual pension contribution of £60,000 (the maximum annual allowance in 2026) reduces taxable income to £460,000
- A portion of the sponsorship income routed through a limited company structure, with advice taken on timing distributions
- Carry-forward pension allowances from three prior years of low earnings allow a further one-off contribution, reducing the effective higher-rate exposure
The result: the same athlete retains an additional £27,000–£42,000 in the same tax year, and begins compounding pension growth at 45p-in-the-pound tax relief rather than paying that away. Over a four-year earning window — roughly the length of a peak-performance sports career — the cumulative difference can exceed £150,000.
This is not tax avoidance. Every vehicle used is HMRC-approved. The difference is simply whether the structures are in place when the money arrives.
What the Shelton Pattern Tells Us
Shelton's career arc is instructive beyond tennis. He turned professional in 2022, ranked 200th in the world. By mid-2023 he was a Grand Slam semi-finalist. By 2026 he holds four titles in a single season and faces the world No. 2 in a US Open quarter-final. The trajectory — from modest income to life-changing earnings inside four years — mirrors what happens to a meaningful minority of high-skilled professionals across many fields.
Wealth managers who work with athletes, entertainers, and high-performance professionals report that the most common error is not reckless spending. It is inertia: continuing to treat money as it arrives in the same way it was treated when much less arrived. The default structures — a current account, a basic pension, a few ISA contributions — were designed for gradual accumulation, not for $1.8 million years.
A Wealth Management expert consulted through ExpertZoom will typically start with three questions in a sudden-income scenario: What legal structures exist or could be created before the next payment? What tax-year-end deadline is approaching and what options close after it? And what are the medium-term income projections — is this a one-year spike or a sustained step-change? The answers determine urgency and strategy.
For Shelton, a quarter-final win against Alcaraz would trigger another significant financial event in addition to an enormous career milestone. For anyone watching and seeing parallels in their own professional trajectory, the lesson is the same: by the time the money has arrived, the window for some of the most effective planning may have already closed.
What to Do If Your Income Is About to Spike
If you have had — or anticipate — a significantly higher-income year than your baseline, three actions are time-sensitive:
Check your pension annual allowance. The maximum contribution for the 2026–27 tax year is £60,000 (or 100% of relevant UK earnings if lower). Contributions made this year receive tax relief at your marginal rate. If you are crossing into the 40% or 45% band, this relief is substantial and available only in the current tax year.
Review your company structure. If you receive endorsement, consultancy, or freelance income, the vehicle through which it is received has tax implications. Changing that structure after the money has been received is often too late to change the outcome.
Get specialist advice before the April 5th tax year end. For any income earned before April 5, 2027, the planning window closes on that date. Wealth management consultations typically need four to eight weeks to produce an actionable plan, which means the effective deadline for action — for high-income earners in the current tax year — is February 2027 at the latest.
Ben Shelton may or may not beat Alcaraz on the Arthur Ashe Stadium court. Either way, his 2026 season has already produced an income event that most people will never experience. The more interesting question — for anyone watching from the stands or a living room in the UK — is whether a similar inflection point in their own career has the financial infrastructure to match it.
This article is for general informational purposes only and does not constitute financial advice. Consult a qualified financial adviser before making decisions based on your personal circumstances.
