 John Green
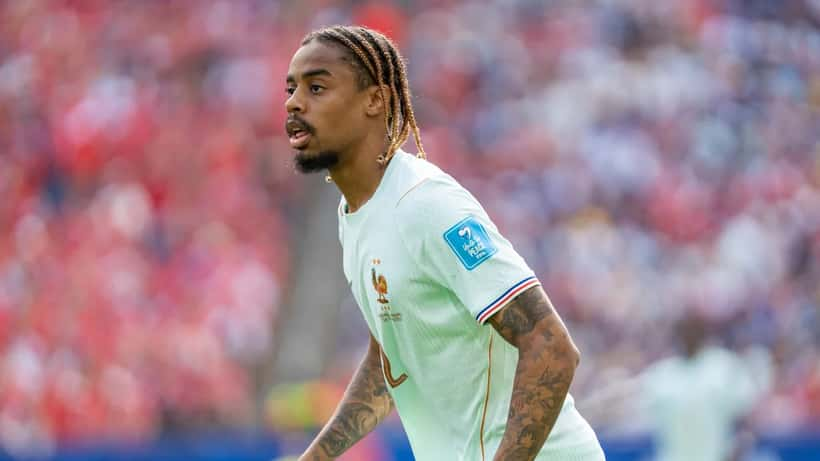
Liverpool and PSG are locked in one of the summer's most-watched transfer sagas, with 23-year-old French winger Bradley Barcola reportedly edging towards a move to Anfield worth in the region of £109.7m. While supporters on both sides debate the fee, there is a financial question few are asking: what does crossing the Channel actually cost Barcola personally?
The Transfer That's Reshaping Liverpool's Attack
Reports confirmed this week that Liverpool have agreed a fee close to £109.7m with PSG for Barcola, who had already signalled to the French club his desire to move. The Reds, backed by fresh capital from a consortium linked to Amazon founder Jeff Bezos, submitted multiple bids over the summer — starting at €100m (£86m), then €115m (£98m) — before landing on a figure PSG could accept. A five-year contract is understood to have been agreed with the player.
It is one of the largest transfer fees paid by an English club in 2026, placing Barcola firmly in the bracket of footballers whose earnings demand serious, specialist financial planning.
What Moving From France to England Really Means for a Player's Wallet
The Premier League offers footballers higher wages, bigger crowds, and global visibility. But the UK tax system carries a sting that surprises even experienced agents.
In France, the top marginal income tax rate is 45% on earnings above approximately €160,000 per year. In England, the same 45% rate applies on income above just £125,140 — a threshold a Premier League player exceeds within the first week of January. That part is comparable. The critical differences lie in image rights, signing bonuses, and how HM Revenue & Customs now treats foreign-source income following a landmark rule change.
Until 6 April 2025, players arriving in England could structure earnings through offshore companies, benefiting from the non-domicile (non-dom) regime. Under that system, foreign-sourced income was only taxed if "remitted" to the UK. The Chancellor abolished the non-dom regime entirely in the Spring Budget 2024. From April 2025 onwards, every pound a footballer like Barcola earns — worldwide — is within HMRC's reach.
This is not a minor accounting footnote. It is a structural shift that fundamentally changes what net income looks like for any footballer relocating to England, and it has prompted wealth managers who specialise in professional sport to revisit the planning assumptions that underpinned transfers just two years ago.
Why Wealth Managers Are Watching This Deal Closely
HMRC has been stepping up enforcement in professional football for several years. By March 2023, the authority had clawed back £124.8m in unpaid tax from Premier League clubs — more than double the £58.7m recovered the previous year. At the time of publication, 171 players and 44 clubs are subject to active HMRC enquiries relating to image rights and related commercial arrangements, according to government data.
The attention is focused primarily on image rights deals. Clubs pay players a salary taxed at 45%, but they may also pay a separate fee for the right to use the player's name, likeness, and brand in commercial activity. If that image rights payment is genuinely arm's length — proportionate to the player's real commercial value — it can be taxed through a corporate vehicle at the 19% corporation tax rate rather than the 45% income tax rate. The problem arises when HMRC views the payment as disguised salary, in which case the full 45% applies, plus interest and penalties.
For Barcola, who has built a strong commercial profile through France's international campaigns and Champions League success with PSG, image rights are not a trivial number. A structured deal could easily involve £4m–£6m annually in image rights payments alongside his salary.
Whether that structure survives HMRC scrutiny depends entirely on whether the arrangements are documented with evidence of genuine commercial value — licensing agreements, third-party brand deals, and contemporaneous valuations prepared before the contract is signed.
The recent changes to the Summer 2026 transfer window rules have also tightened the regulatory environment for agent fees and intermediary arrangements — an added layer of complexity that wealth managers must now factor in alongside the tax planning. For a detailed breakdown of how these new transfer window regulations affect contracts, read our earlier analysis.
The Real Numbers: What Barcola's Take-Home Could Look Like
Consider a scenario that closely mirrors what a deal of this magnitude typically looks like on paper. A 23-year-old French winger, rated among the top attackers in Ligue 1, signs a five-year contract at a Premier League club on a weekly wage of £250,000.
Over a full year, the headline salary is £13m. After 45% income tax applies on earnings above £125,140, and National Insurance contributions are deducted, the player's take-home from salary alone falls to roughly £7m — approximately 54p in every pound, once all statutory deductions are applied.
Now add an image rights arrangement. The club agrees to pay £5m per year to a company holding the player's image rights, priced based on a third-party commercial valuation prepared before the signing. If the structure is correctly documented and the payment is genuinely arm's length, the company pays 19% corporation tax, leaving approximately £4.05m accessible to the player through dividends or further investment.
If the structure is robust and HMRC-compliant: total accessible income across salary and image rights ≈ £11m per year.
If HMRC reclassifies the image rights as salary: total accessible income ≈ £8.5m per year.
The gap is £2.5m per year — or more than £12m over a five-year contract, before interest or penalties are applied. For a player earning at this level, the return on professional wealth management advice is not marginal. It is material.
The Timing Problem Nobody Talks About
Barcola's move also creates a transitional tax exposure that is frequently overlooked in the immediate excitement of a transfer window. UK tax residency kicks in under the Statutory Residence Test — published by HMRC — relatively quickly. A player who spends more than 183 days in England in a given tax year is UK tax resident for that entire year, including any portion spent abroad before the move.
Timing therefore matters enormously. A transfer completed in late July rather than early August may mean the player is treated as UK resident for a longer portion of the tax year, affecting how any signing bonus or lump-sum image rights payment is taxed. Properly structured, a signing bonus can be spread across the contract term for tax purposes. Poorly timed, it can fall entirely within the most expensive tax year.
There is also a French exit tax dimension. When a player leaves France, unrealised gains on assets held at the point of departure — shareholdings in companies, investment portfolios, deferred bonuses — can trigger a French exit tax charge. Managing the interaction between French departure tax and UK arrival rules requires coordination between advisers in both jurisdictions, and ideally begins months before the transfer is announced publicly.
What This Means Beyond Football
The Barcola story is exceptional in scale, but the underlying issues are not unique to elite footballers. Any high-earning professional relocating from France to the UK — whether a company executive joining a London-headquartered firm, a medical specialist taking a hospital contract, or a consultant moving for a major client — faces a version of the same questions.
At what point does UK tax residency begin? How should existing assets and income streams be structured before the move? Are there pension arrangements, carried interest entitlements, or deferred compensation payments that need reviewing in light of the post-April 2025 world, in which the non-dom regime no longer exists as a planning tool?
The best time to consult a wealth management specialist is before the contract is signed, not after. Once residence is established and income has been paid, the structural options narrow significantly. Earlier planning means more levers are available — and, in a deal of this magnitude, the difference between thorough planning and none at all is measured in millions.
This article is for informational purposes only and does not constitute financial or tax advice. Individual circumstances vary. Consult a qualified wealth management adviser before making decisions based on tax or financial planning.
Speak to a vetted wealth management expert on Expert Zoom to understand how a cross-border move affects your personal financial position.
