 Imogen Bennett
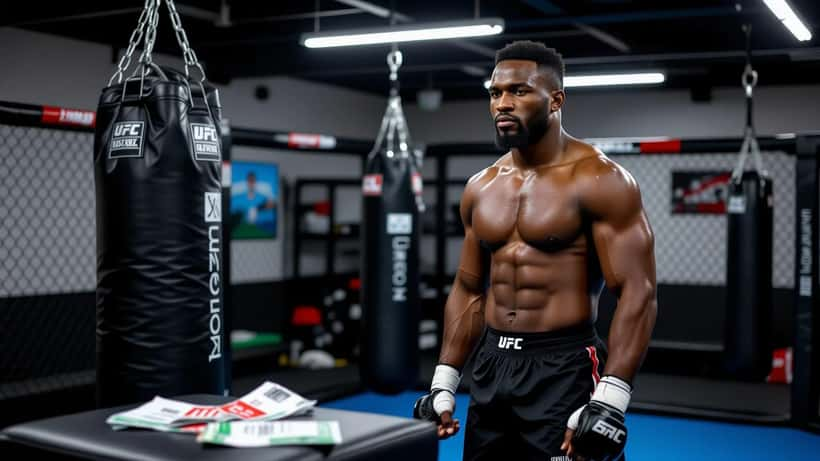
Anthony Wint steps into the octagon at UFC 332 on 3 October 2026 carrying a record that tells one story and a personal history that tells another. Two wins inside the UFC, a heavyweight division on notice — but behind the powerful frame of the man known as "Bow Down" is a period of profound financial collapse driven by gambling addiction that left him homeless. As millions of UK viewers tune in tonight, his journey raises a question that financial experts say is asked too rarely and too late: how do you recognise when gambling has crossed from entertainment into financial crisis, and who can actually help?
This article covers gambling addiction and personal finance. If you are affected by problem gambling, the National Gambling Helpline is available 24 hours a day on 0808 8020 133. For financial advice tailored to your situation, consulting a regulated specialist is recommended before making major decisions.
From the NFL to the Streets: The Making of a UFC Fighter
Wint's path to professional MMA is built on contrasts. A former linebacker for the New York Jets, he combined a professional football career with combat sports training before gambling losses stripped away the financial foundation beneath him. In August 2026, he submitted his case to Dana White's Contender Series 87 and won in 34 seconds — a technical knockout that announced his arrival and earned him a UFC contract on the spot.
Eleven days later, on 22 August 2026 at UFC Fight Night 285, Wint defeated Terrance Chatman via arm-triangle choke in the first round. Tonight's bout against Lucas Armand at UFC 332 is his third performance in under six weeks — a pace that reflects a man acutely aware of how much time was lost.
In several interviews ahead of tonight's card, Wint has been candid about his lowest point: chasing sports bets that compounded, borrowing from family and friends, ultimately losing his housing entirely. The MMA gym became a form of stability before it became a career. His openness has made him one of the most-discussed athletes among UK fans this weekend — not just for what he does in the octagon, but for what he has survived outside it.
What His Story Reveals About Gambling Addiction in the UK
What makes Wint's story resonate so powerfully in the United Kingdom is not its extreme outcome — it is its ordinary beginning. Sports betting, normalised by pervasive advertising and deep integration with live broadcasts, is one of the most common entry points into problem gambling behaviour.
According to the UK Gambling Commission, approximately 2.7 per cent of UK adults meet the clinical criteria for problem gambling — roughly 1.4 million people. A further 7 per cent are considered "at risk." Sports betting accounts for the largest single category of gross gambling yield in the remote sector, exceeding £3.4 billion annually. With major UFC events now drawing record betting volumes from UK customers, the scale of exposure is significant.
The escalation pattern is well-documented. What begins as a £10 accumulator on a weekend Premier League fixture becomes, for a subset of people, a mechanism for chasing losses. The psychology is not a character flaw — it is a recognised behavioural addiction with neurological underpinnings. Dopamine responses triggered by near-misses and variable rewards drive continued betting even when the financial consequences are visible.
Financial professionals working in debt management report that gambling-related debt is among the most concealed. Unlike a mortgage arrears notice or a credit card statement, there is rarely a single document that captures the scale of the problem. By the time a client approaches an adviser, the damage typically spans multiple accounts, informal loans from family members, and a credit profile that has deteriorated significantly over months.
More information on recognising gambling harm is available directly from the UK Gambling Commission's official guidance for the public.
When the Numbers Tell a Story You Have Not Told Anyone
Financial advisers working in debt and gambling-related cases identify several thresholds that signal a habit has become a financial emergency. The first is loss of liquidity: using money earmarked for rent, bills, or mortgage payments to cover betting losses. The second is concealment: actively hiding transaction histories or using separate accounts to obscure the activity. The third — and the one most closely linked to the kind of collapse Wint described — is leverage: borrowing money, whether from institutions or personal contacts, to fund continued betting.
At each stage, the recovery pathway changes meaningfully. Early-stage problem gambling with moderate losses may be manageable through budgeting discipline and blocking tools offered by banks and betting platforms. But once debt accumulates and the credit profile is affected, specialist financial advice becomes essential rather than optional. Waiting is not neutral — it costs options.
The Gambling Commission's own data notes that for every person in acute gambling-related financial distress, an average of six to ten people in their immediate circle are affected by secondary economic impact. The harm rarely stays contained.
A Concrete Case: What £12,000 in Losses Actually Means in Practice
Consider a 34-year-old employed professional in Manchester — a composite profile that reflects patterns financial advisers report regularly. He earns £38,000 per year, holds a mortgage with £60,000 of equity, and over 14 months has accumulated £12,000 in gambling losses spread across two online betting accounts. To cover an earlier run of losses, he took out a £3,500 personal loan. He also owes £2,200 to a family member. His credit score has dropped 89 points following a missed minimum payment on a credit card used to fund a single high-stakes bet in February 2026.
On paper, his income and mortgage are still current. But his disposable income is functionally zero after minimum loan repayments, and he has used three months of his annual performance bonus to cover debts without disclosing this to his partner.
If he approaches a regulated financial adviser now — at the 14-month mark — the recovery options are materially different from what they would be six months later.
At this stage, a Debt Management Plan is feasible. His equity position means he can avoid the worst outcomes. A financial adviser specialising in this area can also coordinate a referral to a gambling-specific therapist working in parallel — because addressing the behaviour and the debt simultaneously is considerably more effective than sequential treatment.
If the debt reaches £20,000+ and property equity cannot cover the gap, the conversation shifts toward Individual Voluntary Arrangements or, in more severe cases, bankruptcy proceedings. Those options carry long-term consequences for employment, housing access, and financial products. The difference between the £12,000 and £20,000 scenarios is often not time or income — it is the decision to act.
What a Financial Expert Can Actually Do
A qualified financial adviser with experience in gambling-related debt brings three things that self-help cannot replicate. First, a complete picture: by reviewing all liabilities across accounts, credit reports, and informal debts, they can map the true scale of the problem — which is almost always larger than the client initially presents. People experiencing this kind of distress tend to undercount, not from dishonesty, but because the full number is too painful to face alone.
Second, a neutral framework. The shame associated with gambling-related financial loss is substantial and well-evidenced. A regulated professional relationship is non-judgmental by training and by obligation, enabling disclosure that does not happen in personal conversations and that is essential for building an accurate financial picture.
Third, a structured plan with legal safeguards. From negotiating with creditors through a formal Debt Management Plan to utilising insolvency protections, an adviser can construct a recovery timeline grounded in actual income rather than optimistic projection. The Financial Conduct Authority registers and supervises debt management firms in the UK, and the FCA's Financial Services Register is publicly searchable — a starting point for identifying regulated professionals.
Free services including StepChange and Citizens Advice complement paid specialist advice and remain sufficient for many people in the earlier stages of difficulty.
What Anthony Wint's Story Is Really Asking
Not everyone watching UFC 332 tonight is placing bets on the outcome. But in the UK, approximately one in three adults will wager on a sports event at least once in 2026. The boundary between recreational and harmful gambling is not visible in the moment — it is only clear looking back.
Wint rebuilt his life through discipline, physical training, and — by his own account — by accepting help when it was offered. He did not attempt to trade his way back to solvency. He stopped, changed the conditions, and found a new foundation.
The financial equivalent of that decision is available earlier than most people realise, and more accessible than most people assume. A consultation with a regulated financial adviser does not begin with judgment — it begins with a question: where are you now, and where do you need to get to?
If your relationship with gambling has moved beyond what you can discuss openly with people close to you, that is the moment to act — not when the statements arrive.
