 Isabelle Torres
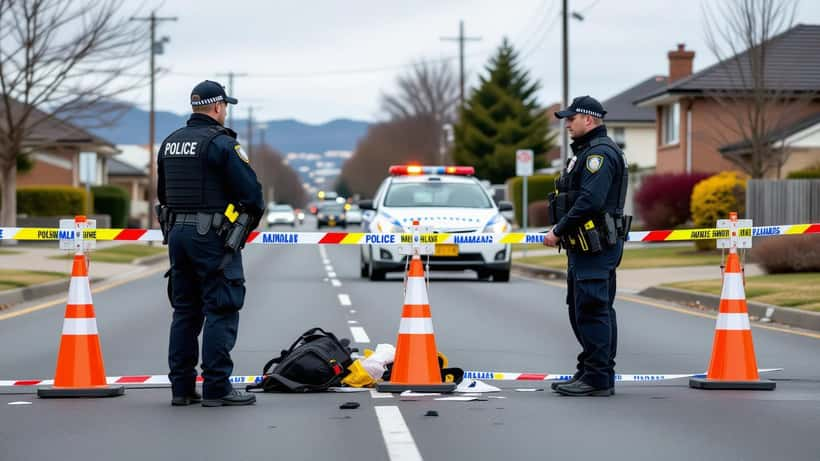
Ten Newcastle Knights supporters — including a five-year-old girl and a two-year-old toddler — were mowed down by a car on Newcastle Link Road at Wallsend on Saturday 3 October 2026, just as hundreds gathered to farewell their team before the NRL grand final. An 18-year-old P-plater, identified in court as Indika Bambrick Samarasinghe, was refused bail and charged with three counts of dangerous driving occasioning grievous bodily harm, three counts of negligent driving occasioning grievous bodily harm, and three counts of causing bodily harm by misconduct. As of Sunday 4 October, the five-year-old girl and a 67-year-old man remained in a serious but stable condition at John Hunter Hospital; four other people, including a 31-year-old woman, were still hospitalised.
For the families caught up in this incident, the shock of injury will soon give way to urgent practical questions: who pays the medical bills? Can the injured claim lost income? What if the driver has no money to pay? The answer in New South Wales is that a specific government-backed insurance scheme — the Compulsory Third Party (CTP) Green Slip system — was designed precisely for moments like this.
What Happened at Wallsend — and Why the CTP Scheme Matters
At approximately 9:30 am on 3 October 2026, a vehicle entered the roundabout on Newcastle Link Road at the intersection of Transfield Avenue, lost control, and ploughed into the crowd on the footpath. Witnesses described the scene as "horrific". Newcastle City Council confirmed the incident in a formal media statement and offered support to the affected families.
Under the Motor Accidents Injuries Act 2017 (NSW), every registered vehicle in New South Wales must carry CTP insurance — the Green Slip. That insurance does not just protect drivers. It covers anyone injured by the vehicle: passengers, pedestrians, cyclists, and bystanders standing on a footpath watching a football team leave town.
This is a critical point that many Australians miss. The 10 people injured at Wallsend were not in a car. They were on a public road, watching an event. Yet every one of them has a statutory right to lodge a CTP claim against the insurer of the vehicle that struck them.
The CTP Claim Process: Two Tiers of Benefits
NSW's CTP system, administered by the State Insurance Regulatory Authority (SIRA), operates in two tiers.
Tier 1 — Statutory benefits (no-fault, up to 26 weeks): These kick in regardless of who caused the accident. They cover weekly income replacement (up to 95% of pre-injury earnings in the first 13 weeks, then 80% for weeks 14–26), reasonable treatment costs (ambulance, hospital, physiotherapy, psychology), and care costs if you need help at home. There is no need to prove fault. Severely injured victims can access these benefits immediately.
Tier 2 — At-fault benefits (beyond 26 weeks for serious injuries): For injuries that persist beyond 26 weeks and are assessed as more than "minor" under the Act, victims can access extended weekly payments (up to five years), further treatment costs, and — critically — common law damages for non-economic loss (pain and suffering) if permanent impairment reaches or exceeds 10% Whole Person Impairment (WPI). For the most seriously injured, damages can extend to past and future economic loss and the full cost of ongoing care.
In a crowd-strike incident like Wallsend, where the driver has been charged with serious offences, blameworthiness is not in dispute. The victims are, legally speaking, entirely "not at fault", which puts them in the strongest possible position under the scheme.
What Should Victims Do Right Now?
Time matters in CTP claims. According to SIRA, injured people should:
Lodge a notification within 28 days. Victims must notify the CTP insurer (via a Claim Notification Form, available from SIRA or any motor accident insurer) within 28 days of the accident to access immediate benefits. Missing this window does not bar a claim outright, but it complicates early payments.
Preserve all documentation. Medical reports, ambulance records, receipts for transport to hospital, and employer payslips to establish pre-injury earnings are all essential from day one.
Do not accept an initial offer without legal advice. Insurers may contact claimants early with offers to finalise statutory benefits. These offers are calculated by the insurer, not a court, and may undervalue long-term impairment that is not yet apparent, particularly for the children involved.
Consult a personal injury lawyer. A specialised personal injury lawyer — one with experience in NSW motor accident claims — can assess the likely impairment rating, identify whether a common law claim is viable, and negotiate with or litigate against the insurer on your behalf.
When the Driver Has No Assets: The Nominal Defendant
One practical concern for victims is whether the at-fault driver — an 18-year-old on P-plates who was refused bail — has any meaningful assets or income to meet a damages award. Under the NSW CTP scheme, this concern is almost entirely irrelevant. The claim is made against the insurer, not the driver personally. As long as the vehicle was registered and insured — which a court will establish — the insurer pays.
If for any reason the vehicle was unregistered or uninsured, a "Nominal Defendant" scheme administered by SIRA steps in as insurer of last resort. Victims of uninsured or unidentified vehicles in NSW still have the right to claim. The key deadline in that scenario is three months from the date of the accident to lodge a preliminary notice.
The Wallsend crash occurred on a public road, on a Saturday morning, involving a registered vehicle. There is every reason to expect standard CTP insurance coverage to apply in full.
The Concrete Case: What a 31-Year-Old Parent Could Realistically Claim
Consider a composite scenario grounded in the Wallsend facts: a 31-year-old woman — consistent with the age reported for one of the hospitalised victims — who worked full-time as a medical receptionist earning $68,000 per year. She sustained a fractured tibia and soft tissue injuries to her knee, requiring surgery and a minimum 14 weeks off work.
If she navigates the claim alone:
- Tier 1 statutory weekly income payments cover 95% of $68,000 for 13 weeks = ~$12,977, then 80% for weeks 14–26 = ~$4,152 for the remaining two weeks. Total income replacement: approximately $17,129.
- Treatment costs (hospital gap, physio, occupational therapy) reimbursed directly under the scheme.
- If she accepts SIRA's "minor injury" classification without challenge — which insurers may attempt — her claim ends there. Total: roughly $17,000–$22,000.
If she engages a personal injury lawyer within 30 days:
- The lawyer assesses the knee damage as likely exceeding 10% WPI following surgery and potential ongoing instability.
- A formal independent medical assessment is obtained; impairment is rated at 14% WPI — clearing the threshold for common law damages.
- Common law damages on assessment: approximately $95,000 in non-economic loss (pain and suffering, loss of enjoyment of life), $11,500 in past economic loss beyond statutory benefits, $18,500 in future income impact, and $9,000 in out-of-pocket costs = total settlement approximately $134,000.
- Legal costs: typically deducted from the settlement on a no-win-no-fee basis at 15–20% = approximately $20,000–$27,000.
- Net outcome: ~$107,000–$114,000 versus the unadvised ~$17,000.
The difference — roughly $90,000–$97,000 — flows entirely from understanding whether the injury clears the impairment threshold for common law access, and from refusing an early inadequate offer. That threshold assessment requires specialist medical and legal expertise that the average claimant does not have.
For children, the calculation is handled differently: minors cannot finalise a settlement without court approval, which provides an additional procedural protection. The five-year-old girl and two-year-old toddler injured at Wallsend will have their claims managed by a parent or guardian, and any settlement must be approved by a judge — a safeguard designed precisely to prevent under-settlement of childhood injuries.
What Comes Next
As of 7 October 2026, the driver remains before the courts. Criminal proceedings will unfold independently of civil CTP claims — the two streams do not interfere with each other, and a guilty verdict in the criminal matter can, in fact, strengthen a civil claim by establishing fault conclusively.
For anyone affected by the Wallsend crash — whether directly injured, a parent of an injured child, or a family member who incurred care costs — the practical priority right now is to register a claim with the CTP insurer and seek a free initial consultation from a personal injury lawyer experienced in NSW motor accident law.
Expert Zoom connects Australians with qualified personal injury lawyers and legal specialists who can assess CTP claims, negotiate with insurers, and advise on whether a common law action is warranted — without upfront cost.
This article is general information only and does not constitute legal advice. For advice specific to your situation, consult a qualified legal practitioner.
