 Chloe Kennedy
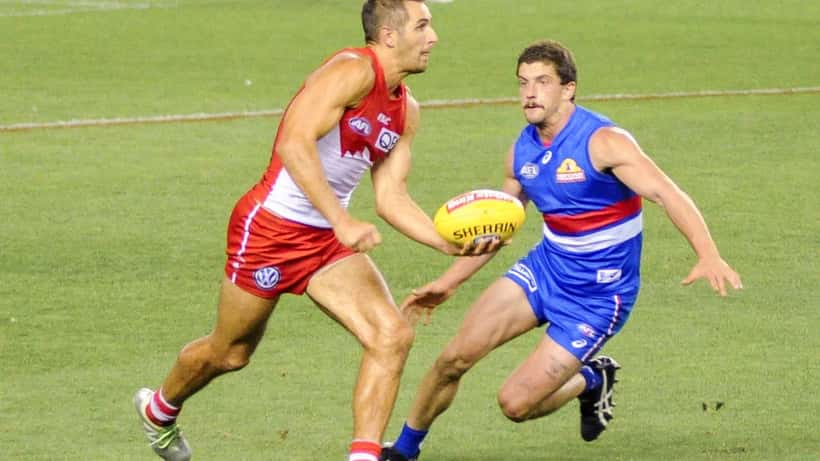
Tom Liberatore stood in the Western Bulldogs' rooms following their 2026 elimination final loss to Adelaide and announced what many had feared: his 16-year AFL career was over. The 34-year-old midfielder, who managed just 11 games this season due to persistent injury and concussion concerns, retires having played 268 games — a figure that places him among the most decorated Bulldogs of his generation.
But beyond the tributes and the tears, Liberatore's retirement raises a question that applies to thousands of Australians each year who step away from high-income careers in their thirties: what happens to your financial life when your playing days end early?
The Financial Reality Behind an AFL Retirement
AFL players occupy a peculiar position in the Australian workforce. They earn above-average incomes from age 18, have employer superannuation contributions made throughout their careers, and retire decades before most Australians. For a player like Liberatore — who has been on the AFL list since 2010 — that means roughly 16 years of superannuation contributions accumulated during peak earning years, locked away until preservation age.
The problem? Under current Australian Tax Office rules, you cannot access your superannuation until you reach preservation age — which for anyone born after 1 July 1964 is 60 years old. For a 34-year-old AFL retiree, that means 26 years without access to what may be their largest financial asset.
The ATO superannuation access rules make clear that even when you cease employment permanently, your super remains locked until preservation age, with very limited exceptions — terminal illness, permanent incapacity, and severe financial hardship being the primary pathways.
This is not a niche problem. It affects every AFL player who retires in their thirties, and the financial planning decisions made in the 12 months before and after retirement can determine whether a player enjoys long-term financial security or faces a decade of unexpected cash-flow pressure.
What the AFLPA Provides — and What It Doesn't
The AFL Players' Association has dedicated financial infrastructure for retiring players. AMP serves as the default superannuation fund for more than 3,500 past and present AFL players under the AFLPA's Industry Superannuation Plan, while Shadforth Financial Group provides financial planning services to AFLPA members both during and after their playing days.
Retiring players also have access to the Player Retirement Scheme — a structured support program that includes Education and Training Grants available for up to five years post-retirement, giving former players resources to fund further education, TAFE courses, and professional development.
These are meaningful supports. But they do not resolve the core financial challenge: an AFL player retiring at 34 will need to fund approximately 26 years of living expenses before preservation age is met, then potentially another 25 years of retirement thereafter. The AFLPA programs provide a bridge, not a complete blueprint.
A qualified wealth management adviser — particularly one familiar with professional athlete finances — can model income drawdown strategies, tax-efficient investment structures outside of super, and transition-to-career pathways that protect long-term wealth. For players on senior AFL contracts, which in 2026 can range from $200,000 to well over $1 million per year, the stakes are very high.
Superannuation, Investment, and the Locked Asset Challenge
When a professional AFL career ends at 34, the player typically has a superannuation balance reflecting 16-plus years of employer contributions at a rate of 11.5% (the legislated rate in 2026). For a player who has averaged $350,000 per year over eight seasons, employer contributions alone amount to approximately $322,000 — before investment returns and any personal salary sacrifice contributions.
That balance compounds untouched until age 60. In the meantime, the former player needs income from somewhere.
The strategies available are more varied — and more complex — than many retirees realise:
- Investment trusts and family trusts can hold capital outside superannuation and distribute income tax-efficiently, reducing the effective rate from 47% (top marginal) to a blended rate potentially as low as 25% if income is spread across lower-income family members.
- Diversified investment portfolios outside super — ETFs, direct shares, property — can generate returns that supplement post-football income.
- Income protection insurance held inside the AFLPA's superannuation plan may be claimable during the period immediately post-retirement if retirement is driven by ongoing injury or medical incapacity.
- Total and Permanent Disability (TPD) claims are available through most Australian superannuation funds for members who demonstrate they are permanently unable to work in their usual occupation — including professional sport.
For a player like Liberatore, who has documented injury and concussion problems throughout 2026, a TPD or permanent incapacity claim could potentially unlock a portion of his superannuation earlier than preservation age. The eligibility threshold is high and policies vary, making specialist advice essential.
Players who have accumulated super across multiple funds during their career — a common occurrence for those who moved states, changed clubs, or held part-time roles during transitions — may also be leaving dormant balances behind. Consolidating accounts before fees and duplicate insurance premiums erode those balances is a priority step. A wealth management expert familiar with the current superannuation changes taking effect in 2026 can ensure that consolidation decisions are timed to maximise insurance entitlements.
What Liberatore's Retirement Might Look Like, Financially
Consider a realistic composite scenario that reflects the financial position of a long-serving AFL midfielder retiring at 34.
The situation: A player finishes their final AFL season having averaged $380,000 per year over the past nine years. They have an estimated superannuation balance of $720,000 — accumulated through employer contributions, personal salary sacrifice, and 16 years of compound investment growth. That super cannot be accessed until age 60, creating a 26-year gap. Outside super, the player has $420,000 in liquid savings and investments.
The cash-flow problem: Without AFL salary, the player needs to fund annual living costs of approximately $95,000 (indexed at 3% inflation) from non-super assets and any post-football income. At that rate, drawing $95,000 per year from $420,000 with no investment return exhausts available funds in under five years — before the player turns 39.
The if/then calculation: If the player invests the $420,000 in a broadly diversified portfolio returning 6% per annum and draws only $75,000 per year in the early years (supplemented by AFL alumni grants and part-time work), the non-super assets extend to approximately age 48. Combine that with a structured family trust distributing income at a blended tax rate of 28% rather than 47%, and the player saves approximately $19,000 per year in tax alone — further extending the runway. At age 48, 12 years remain before preservation age, bridgeable through part-time employment or ongoing investment income.
The critical insight: The difference between running out of money at 39 and remaining financially stable until 60 is not the size of the initial savings. It is the quality of the financial plan implemented in the first 12 months after hanging up the boots. Every year of delay compounds the disadvantage.
This scenario reflects why post-career financial planning for AFL players — who often accumulate wealth rapidly but lose income abruptly — is a specialist discipline, not a standard financial planning exercise.
Concussion History and TPD Insurance: An Often-Overlooked Pathway
Liberatore's injury challenges in 2026 add a dimension that many former players overlook when examining their superannuation options.
Australian superannuation funds are required to carry Total and Permanent Disability insurance for members. If a player can demonstrate that recurring injury — including concussion — has permanently impaired their capacity to work, not just in professional sport but in any occupation for which they are reasonably suited by education, training, or experience, a TPD claim can unlock superannuation well before preservation age.
The evidentiary bar is high, and policy definitions vary between funds. But for players with documented chronic concussion histories — increasingly common in AFL as awareness grows — this pathway deserves careful examination by a licensed financial adviser who understands both superannuation law and the specific terms of the AFLPA's AMP fund policy.
As AFL concussion protocols continue to evolve and medical understanding of cumulative head injury deepens, more former players are finding that documented injuries they managed through their careers have long-term implications — medical, legal, and financial. Getting specialist advice early, while records and medical histories are current, is important.
Five Steps Every AFL Retiree Should Take in the First 90 Days
Specialist wealth management advisers who work with athletes and high-income early retirees consistently identify the same critical window: the 90 days immediately following retirement. Decisions made — or deferred — in this period have outsized consequences.
- Consolidate superannuation accounts. Identify every fund held across your career and consolidate to stop paying duplicate insurance premiums and administration fees. Do not cancel insurance before first checking whether a claim is available.
- Audit your existing insurance inside super. Review income protection and TPD cover levels, benefit periods, and the specific definitions of disability that apply. Your fund's policy document is the source of truth.
- Build a 5-year cash-flow model. Understand how long your non-super assets will last at your expected spending rate, both with and without investment returns.
- Explore trust structures and investment entities. Family trusts, investment companies, and other structures are most tax-effective when established before large assets are committed.
- Engage a specialist, not a generalist. Wealth management advisers familiar with the AFLPA's superannuation arrangements and professional athlete income patterns will identify options that a general planner is unlikely to raise.
Tom Liberatore gave 16 seasons and 268 games to the Western Bulldogs and the game of AFL. Players who generate substantial wealth during long careers deserve financial advice that matches the complexity of their situation. As other recent AFL retirees have found, getting that advice in place early — before cash flow tightens and before sub-optimal financial structures become entrenched — is the most important move a retiring player can make.
This article is for general information only and does not constitute financial advice. Superannuation rules, insurance entitlements, and tax obligations are complex and individually specific. Always consult a licensed financial adviser before making superannuation or investment decisions.
If you are navigating an AFL retirement or a high-income career transition and want tailored guidance from a specialist wealth management adviser, Expert Zoom can connect you with the right expert for your situation.
