 Chloe Kennedy
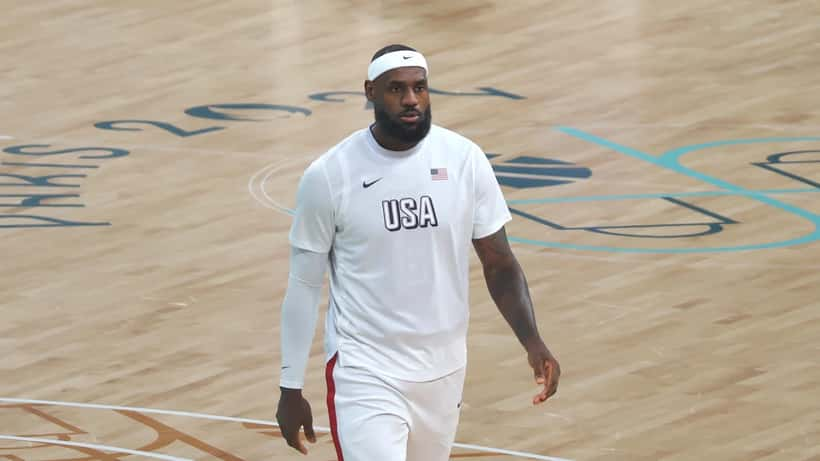
When LeBron James suits up for the Philadelphia 76ers against the New York Knicks at Madison Square Garden on 20 October 2026 — the opening night of the 2026-27 NBA season — he will be 41 years old, earning more than $50 million for the season, and entering his 24th year as a professional athlete.
The sports world is asking: how long can he keep going? Financial advisers are asking a different question: when should he stop?
That question is not unique to LeBron James. Across Australia, hundreds of thousands of workers approaching their late 50s and early 60s face the same calculation — whether to stay in their career "one more year" for the additional income and superannuation contributions, or whether the cost of delay outweighs the financial benefit. With the NBA's 2026-27 season arriving as the Australian tax year enters its second quarter, the timing is a useful prompt for a financial conversation many Australians are deferring.
Why the NBA Season Opening Is a Prompt for Every Australian Approaching 60
The 2026-27 NBA season opens on 20 October with a tripleheader broadcast on NBC and Peacock: Boston Celtics at Detroit Pistons, the Philadelphia 76ers at the New York Knicks, and the Oklahoma City Thunder at San Antonio Spurs. LeBron James — who signed with Philadelphia during the offseason — headlines the marquee match: his 76ers debut against the defending-champion Knicks will draw a global audience.
The financial dimension of LeBron's decision to sign with Philadelphia rather than retire is illuminating. His annual salary is north of $50 million. His total career earnings from NBA contracts alone exceed $500 million. And yet, financial analysts have noted for years that many former elite athletes — earning substantially less than LeBron — retire with far smaller net assets than their peak salaries would suggest. The primary cause is poor timing on tax-advantaged retirement drawdown and excessive concentration in illiquid assets like residential property.
According to the Australian Taxation Office (ATO), Australians who access their superannuation before turning 60 must pay income tax on most withdrawals at their marginal rate — potentially 37% or higher at median professional salary levels. Those who wait until after 60 can access their super tax-free. That gap — between age 58 and age 60 — can represent tens of thousands of dollars in avoided tax for the average Australian with a mid-tier superannuation balance.
The decision LeBron is navigating at 41, at a scale most of us will never experience, is structurally the same decision millions of Australians face in their late 50s: how much is "one more year" actually worth?
The Expert Angle — What Elite Contracts Teach About Late-Career Timing
Australian wealth management advisers frequently identify what they call the "last salary trap" — the tendency for high-earning professionals to defer retirement because their current income feels too valuable to leave on the table. LeBron's $50M season is an extreme version; for an Australian professional earning $110,000 in their early 60s, the psychology is identical.
Three structural parallels between elite athlete contracts and everyday superannuation planning are worth understanding before the NBA season begins:
The superannuation guarantee (SG) rate is now 12%. From 1 July 2025, every Australian employee receives mandatory employer super contributions of 12% of their ordinary time earnings. For a worker earning $100,000, that is $12,000 per year in additional super — tax-advantaged, with earnings taxed at 15% inside the fund rather than at the marginal rate. For someone approaching the transfer balance cap, each additional year in the workforce has diminishing marginal value.
Transition-to-retirement (TTR) income streams allow Australians who have reached their preservation age to begin drawing from their super while still working. For most Australians born after 1 July 1964, that preservation age is 60. The maximum annual drawdown is 10% of the account balance. For a worker with $800,000 in super, this means up to $80,000 per year — tax-free after age 60 — potentially supplementing a reduced work schedule without requiring full retirement.
The concentration risk problem affects both elite athletes and working Australians. LeBron's wealth is partially concentrated in his own brand ventures and media investments. Many Australians approaching retirement hold the majority of their net worth in a single residential property. A qualified wealth adviser can model the risk-adjusted case for diversifying that concentration before retirement — an analysis that, for many Australians, is worth more than another year of salary accumulation.
For further context on how NBA contract structures illuminate Australian financial planning decisions, this earlier analysis on the Clippers' $162M payroll reset explored how team-level trade-offs mirror portfolio rebalancing decisions.
The One More Year Scenario — What the Maths Actually Says
Consider the situation of David, 58, an experienced logistics manager in Melbourne who has worked for the same company for 21 years. His annual salary is $105,000. His superannuation balance is $790,000, invested in a balanced growth option that has returned an average of 6.8% per annum over the past decade. His employer has offered an early retirement package.
David is weighing whether to accept the package now or continue working until 60.
If David accepts now at age 58:
- Super continues to grow for two more years at approximately 6.8%: $790,000 × (1.068²) ≈ $900,700 by age 60
- He forgoes two years of SG contributions: 12% × $105,000 × 2 = $25,200 in employer contributions not received
- Net projected super balance at 60: approximately $925,900
If David continues until 60:
- Two additional years of SG contributions plus ongoing growth bring his estimated balance at 60 to approximately $945,000
The if/then logic:
- If David retires at 58 and begins drawing $78,000 per year from his super immediately (before the tax-free threshold applies at 60), that pension attracts marginal income tax at approximately 32.5%-37%, potentially costing him $18,000–$22,000 in tax per year — a two-year tax bill of up to $44,000.
- If David waits until age 60 and draws the same $78,000 annually, it is entirely tax-free under the tax-free superannuation income stream rules.
- Net difference: waiting two years may save David $36,000–$44,000 in tax, plus an additional $20,000 in super growth — a combined benefit approaching $60,000 for two years of continued employment.
That said, if David's early retirement package includes a genuine redundancy payment (partially tax-free under ATO rules), or if his personal health or personal circumstances favour earlier retirement, the mathematics changes. A financial adviser can model David's specific situation — including Centrelink asset test implications, the impact on any partner's income, and expected investment returns in the current rate environment — in a single consultation.
Three ATO Rules Every Late-Career Australian Should Know Before the Super Withdrawal Conversation
As the NBA season opens and LeBron James writes the final chapter of one of sport's greatest careers, Australians in their late 50s have an opportunity to pressure-test their own exit strategy against three foundational ATO rules:
1. Tax-free super starts at 60. Withdrawals from a taxed superannuation fund after your 60th birthday are generally tax-free, regardless of whether they are taken as a lump sum or as an income stream. Accessing super before 60 typically incurs tax at marginal rates, less a 15% tax offset for the taxed component.
2. The preservation age is 60 for most Australians born on or after 1 July 1964. You can begin a transition-to-retirement income stream at preservation age while continuing to work part-time — but the maximum annual drawdown is capped at 10% of your opening annual balance.
3. The transfer balance cap limits how much super you can transfer into tax-free pension phase. Indexed annually by the ATO, this cap sits around $1.9 million (verify the current figure at the ATO's superannuation information page before making any decisions). Balances above the cap cannot be moved into the tax-free pension phase — meaning entry timing matters significantly for high-balance accounts.
LeBron James has the luxury of choosing when to retire entirely on his own terms, with financial counsel that most people will never access. Australians approaching their preservation age rarely have $50M annual salaries — but they do have a regulated superannuation system specifically designed to reward thoughtful timing decisions. A wealth management expert can help you determine whether "one more year" is genuinely the right play for your super balance, or whether the final whistle is already the optimal call.
Find a qualified wealth management adviser on ExpertZoom to review your superannuation drawdown strategy in a single consultation.
General information only. This article does not constitute financial advice. Superannuation rules and ATO thresholds change annually — always verify current figures directly with the ATO or a licensed financial adviser (AFSL holder).
