 Olivia Thompson
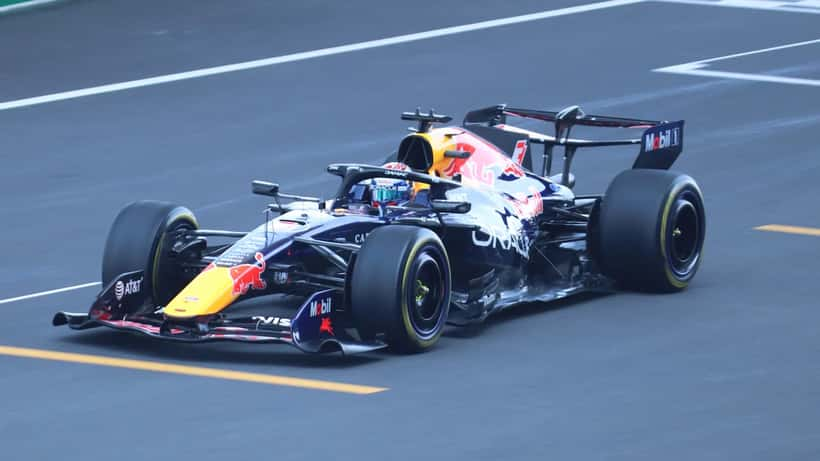
The world's highest-paid racing driver is seriously considering walking away from his sport — at 29. Max Verstappen, whose estimated net worth sits around USD $220 million (approximately AUD $335 million) and whose 2026 Red Bull salary alone runs to an estimated $65–70 million annually, told reporters this year that he is "not enjoying" the sport under its new technical regulations and has contemplated retiring at the end of 2026 — two full years before his contracted end date.
For Australians watching this unfold, the story raises a rarely asked question: how much money do you actually need before walking away from work makes financially sound sense? And crucially — how should you be building toward that number right now?
The Numbers Driving Verstappen's Exit Talk
Verstappen's wealth has accumulated across four Formula 1 world championships and a decade of elite sponsorships with Red Bull, Redline, and Jumbo. His current deal, signed in 2022 and extended in August 2026 through 2030, is reportedly worth $275 million total according to Spotrac. His annual earnings including sponsorships are estimated to exceed €76 million.
What makes his retirement calculus unusual is not the number itself — it is the trigger. After the 2026 Japanese Grand Prix, Verstappen stated publicly that he is frustrated with F1's overhauled technical regulations, which reshaped the performance characteristics of his car. Reports confirmed his contract includes a performance-linked exit clause that could let him walk before the term ends.
"The car just doesn't drive the way I need it to," Verstappen said in a widely reported interview. "If it doesn't get better, I need to be honest with myself about whether this is still right for me."
Red Bull moved to quell the speculation with the contract extension, but the retirement conversation has not gone away. For most Australians — whose median super balance at age 35 sits at approximately $50,000 according to the ABS — the relevant question is not whether you can walk away at 29, but whether you are building the foundation that gives you the choice at 50.
What Financial Independence Actually Requires
The most widely used framework for retirement sustainability is the 4% rule, first established by financial planner William Bengen in 1994 and validated by the Trinity Study. The rule holds that a diversified portfolio can sustain annual withdrawals of 4% indefinitely in real terms. In practical terms, this means accumulating 25 times your expected annual expenses before stopping paid work.
For an Australian spending $80,000 a year — covering rent-free living, private health cover, and modest travel — the threshold is $2 million. For someone spending $120,000 annually, it rises to $3 million.
This is where Australian superannuation becomes both powerful and limiting. For Australians born after 30 June 1964, super cannot be accessed until age 60 (the preservation age). Anyone targeting financial independence before that age must build two separate pools: a non-super bridge to cover living costs from their target retirement age to 60, and a superannuation balance that continues compounding until preservation age unlocks it.
Getting that split right — and optimising concessional contributions (capped at $30,000 per year in 2026–27, including your employer's Super Guarantee) versus non-concessional contributions (capped at $120,000) — is precisely where the difference between reaching your number on time and missing it by a decade becomes visible. As ASIC's MoneySmart notes, even modest increases in contribution rates compounding over 20 years can add hundreds of thousands of dollars to a final super balance.
Emma's Early Retirement Calculation: Two Paths, One Decision Point
Take Emma, a 34-year-old registered nurse in Melbourne earning $95,000 gross. She has $87,000 in superannuation, no financial advisor, and a vague intention to stop clinical work somewhere around age 50. Her employer contributes 11% SG ($10,450 per year), giving her a current annual super inflow of $10,450.
If Emma continues without any restructuring: projecting at a 6.5% annualised real return over the next 26 years, her super balance reaches approximately $575,000 by age 60. Under the 4% rule, that supports withdrawals of $23,000 per year — well below the ASFA Comfortable Retirement Standard for a single Australian (approximately $51,000 annually in today's dollars, updated quarterly). More critically, she has zero accessible funds before 60, meaning if she stopped working at 50, she would need to fund ten years of living costs — potentially $700,000 to $900,000 — from savings she has not built.
If Emma acts now after a single session with a wealth management advisor: she salary-sacrifices an additional $15,000 per year into super (bringing her total annual contribution to $25,450, still within the concessional cap) and simultaneously invests $500 per month into a diversified ASX/global ETF portfolio outside super.
- Her superannuation balance at 60 grows to approximately $870,000 in today's dollars — enough for $34,800 in annual tax-advantaged withdrawals, likely supplemented by Age Pension entitlements.
- Her non-super ETF portfolio, compounding at 7% from age 34 to 50, accumulates to approximately $195,000 — sufficient to contribute $15,000–$19,500 per year for ten years as a bridge to preservation age, supplemented by any part-time income or short-term contract work.
In dollar terms: the cost of an initial consultation ($200–$500) and ongoing advice (typically 0.5–1% of invested assets annually) produces a projected improvement of approximately $295,000 in lifetime wealth, plus the practical ability to stop full-time nursing a decade earlier. The fee-to-outcome ratio flips sharply in advice's favour when you start at 34 rather than 54.
Reading the July 2026 Rule Changes Before You Plan
Emma's calculation also depends on understanding the July 2026 superannuation rule changes, which introduced payday super requirements compelling employers to pay the Super Guarantee at the same time as wages rather than quarterly. For employed Australians, this accelerates compounding — earlier contribution means more time in the market — but requires checking that your employer is actually complying. Many are not, according to the ATO's early compliance monitoring.
If you are self-employed or a contractor — a growing proportion of Australia's nursing, IT, and trades workforce — payday super does not apply to you automatically. You are responsible for making your own contributions, and the default is nothing. A wealth advisor can structure a regular personal contribution schedule that mirrors the compounding benefit employed workers now receive by default.
Three Signals That It's Time to Seek Advice
Most Australians delay professional wealth advice because the conversation feels premature. It almost never is. These three markers indicate the window for high-impact advice is open:
- You are between 30 and 45 with more than $80,000 in super. This is the phase where compounding acceleration is strongest and contribution strategies have the most runway to work.
- Your income exceeds $120,000. Above this threshold, Division 293 tax applies an additional 15% levy on concessional super contributions. Restructuring before this bracket is reached — or immediately after — is one of the highest-value moves available.
- You have never calculated your FIRE number. Not a rough figure — a specific annual living cost estimate multiplied by 25, net of projected super. Without this calculation, any retirement plan is guesswork.
Initial consultations with Australian wealth management advisors typically cost $200–$500 for a comprehensive review. Ongoing advice, when appropriate, is structured as a percentage of invested assets at 0.5–1% annually. For someone at Emma's stage, a single well-structured session can identify optimisations — salary sacrifice levels, contribution splits, insurance inside versus outside super — worth multiples of the upfront cost within the first financial year.
The Actual Question Verstappen Answered
Max Verstappen's retirement story will resolve one way or another over the coming months. He may race on; he may not. But his underlying question — do I have enough, and what happens if I walk away before I was supposed to — is one every Australian earning a salary should be asking of their own situation right now.
The conditions that make early retirement rational are not mysterious: a specific number, two correctly sized portfolios, and the structural knowledge to build them efficiently. The longer that conversation is delayed, the more the answer costs to hear.
This article is for general informational purposes only and does not constitute personal financial advice. Speak with a licensed financial adviser before making any changes to your superannuation or investment strategy.
