 Isla Henderson
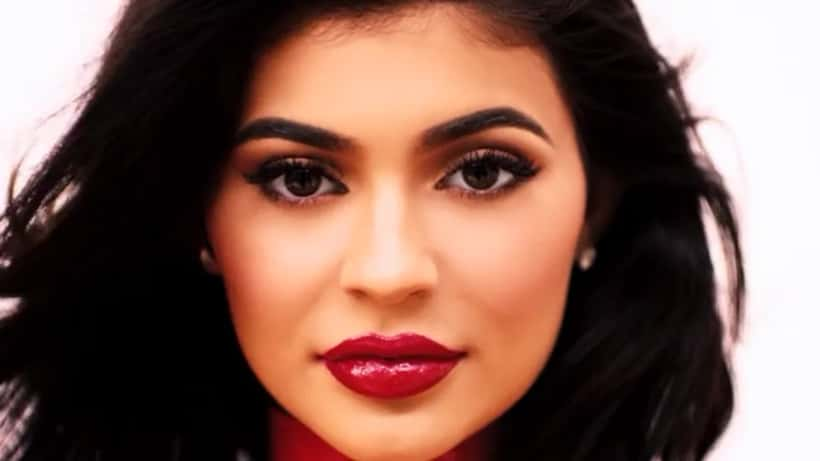
Kylie Jenner made a surprise debut at the 2026 Victoria's Secret Fashion Show on 18 October, closing the runway in a Jacob & Co. Fantasy Bra that the jeweller describes as the most valuable ever made. Reports put its value at US$50 million, about AU$71.7 million. For Australians who own a diamond ring, an heirloom watch or a gold chain, the headline raises a practical question: what is your own jewellery actually worth, and would your insurer pay out that figure?
What was on the runway
According to E! News, the show was held at Sony Pictures Studios in Culver City, California. Jenner was the first non-Victoria's Secret model to wear the Fantasy Bra since Elsa Hosk wore it in 2018. Her partner Timothée Chalamet and her mother Kris Jenner watched from the audience.
Marie Claire Australia reports that the piece was created with Jacob & Co. and features 4,410 natural diamonds, including a 75.54-carat Fancy Vivid Yellow diamond at the centre. Jacob & Co. says it contains 3,218 individually designed components and took about 1,000 hours and 15 artisans to build.
Treat the numbers with care. The valuation, diamond count and labour figures come from the jeweller's own statements, and outlets disagree on the headline value. Men's Journal puts the central diamond alone at US$22 million, while others quote US$50 million for the whole piece. Nobody has published how the valuation was calculated.
That gap between a claimed value and a verified value is the part that matters at home.
Why "value" is not one number
Jewellers and insurers use different yardsticks, and mixing them up is the most common reason owners are underinsured.
- Retail replacement value is what it would cost to buy a comparable piece new from a jeweller today. This is usually what an insurer pays out under a "replace" policy.
- Market or resale value is what a buyer would pay you now. It is often far lower than replacement value.
- Agreed value is a figure you and the insurer settle in advance, typically backed by a valuation certificate.
- Sentimental value is real, but no policy pays for it.
Gold and diamond prices move, so a certificate written several years ago can understate today's replacement cost. Many jewellers and insurers recommend revisiting valuations periodically. Check your policy wording for how often your insurer expects an update.
What this means for ordinary jewellery owners
Most Australian home and contents policies cover jewellery in some form, but with limits. Insurers commonly cap the amount payable for unspecified valuables, and they often require individual items above a set value to be listed separately. The thresholds differ between insurers, so the Product Disclosure Statement (PDS) is the only reliable source.
Cover can also change depending on where the item is. A ring that is covered in the house may be treated differently when worn in public, or when it is in a bank deposit box or a hotel safe. Some policies cover loss away from home only if you pay for an extension.
If you want to understand how insurers are regulated and what disclosure they must give you, the Australian Securities and Investments Commission publishes consumer guidance on general insurance products and your rights to dispute a decision.
A worked example: the engagement ring that was never listed
Consider a hypothetical case. In 2019, a Brisbane couple bought a 1.5-carat diamond ring for AU$18,000 and wore it daily. Their home and contents policy allows AU$3,000 for any single unspecified item. They never listed the ring, and they never updated the original receipt.
In 2026, the ring is stolen during a burglary. A jeweller's current replacement quote for a similar stone and setting comes to AU$24,500, because prices and the exchange rate have shifted since purchase.
Here is the if/then logic:
- If the ring was not specified, then the insurer may pay only up to the AU$3,000 sub-limit, leaving a shortfall of roughly AU$21,500.
- If the ring had been specified at the AU$18,000 purchase price and never revalued, then the payout could still fall about AU$6,500 short of the current replacement cost, depending on whether the policy is "agreed value" or "replacement".
- If the ring had been specified with a recent valuation of AU$24,500, then the couple would be positioned to recover the full replacement figure, less any excess.
The extra premium for listing an item is typically a small fraction of the value, but quotes vary by insurer, location and security. Those figures are illustrative only and are not a quote.
The lesson is not that every owner needs a US$50 million policy. It is that the gap between what you think you own and what your policy actually covers can be tens of thousands of dollars.
Why the Fantasy Bra is a useful reminder
High-profile jewellery is rarely worn without layers of protection. Pieces like this typically travel with security staff, specialist transport and bespoke cover arranged between the jeweller and its insurer. Ordinary owners have none of that, which makes the paperwork they hold even more important.
The Fantasy Bra also shows how much of a jewel's headline value can rest on a single stone. A 75.54-carat diamond is exceptional, but the same principle applies to a 1-carat centre stone: a small change in colour grade, clarity grade or certification can move a valuation by thousands of dollars. Ask your valuer to record those details in writing, because an insurer assessing a claim will look for them.
Finally, remember that valuations expire in practice. A certificate with no date, or one issued many years ago, is much weaker evidence than a recent appraisal accompanied by clear photographs.
Steps worth taking this month
Public attention on a record-breaking piece of jewellery is a reasonable prompt to run a quick household check:
- Find the paperwork. Gather receipts, certificates, photos and any previous valuations.
- Read your PDS. Look for the single-item limit, the total limit for valuables, and what happens outside the home.
- Get current valuations from an independent, qualified jewellery valuer for items above your policy's threshold. Be wary of a valuer who also offers to sell you a replacement.
- List high-value items individually, and ask your insurer whether the cover is agreed value or replacement.
- Photograph and record serial numbers or inscriptions, which can help recovery and claims.
- Review each year or after a major price movement in gold or diamonds.
When to speak to an expert
Insuring and valuing jewellery sits at the crossroads of insurance, asset planning and, for larger collections, estate planning. A wealth management specialist can help you decide whether valuables should be insured under a standalone policy, how they fit in your overall balance sheet, and how they will pass on to beneficiaries. Complex collections, inherited pieces or items held through a company or trust can raise additional questions that a general policy summary will not answer.
This article is general information, not financial or insurance advice. It does not consider your personal circumstances. Check your own policy documents and consider speaking with a licensed professional before making decisions.
If you are unsure whether your jewellery and other valuables are properly protected, you can consult a wealth management expert on Expert Zoom and get tailored guidance before the next headline reminds you.
