 Chloe Kennedy
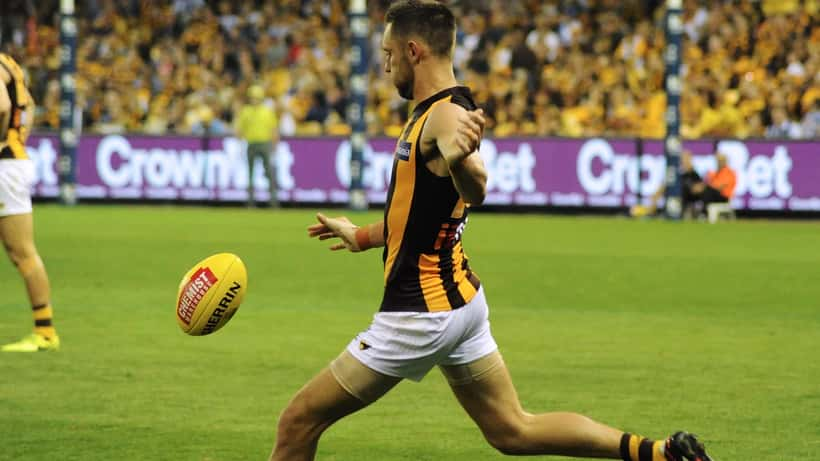
Jack Gunston has done it again. The 34-year-old Hawthorn forward, who many pundits wrote off after a difficult 2023 stint at Brisbane, has signed a one-year contract extension that will take him into a remarkable 18th AFL season in 2027. Averaging 3.3 goals per game in 2026 — the best goal-per-game output of his career — and earning approximately $650,000 annually, Gunston is proof that elite sporting careers can defy the actuarial tables. But when the ink dries on a one-year deal at 34, something else starts running: a financial countdown that demands expert attention.
The Comeback That Changed the Conversation
When Gunston departed Hawthorn for Brisbane at the end of 2022, it looked like the end of a storied career. Instead, his return to Waverley Park has produced two successive All-Australian selections, a second Peter Crimmins Medal, and now a fresh deal announced by Hawthorn Football Club in July 2026. Coach Sam Mitchell confirmed the extension alongside a second player deal, describing Gunston's form as "exceptional by any standard at any age."
What makes this story financially interesting is what the one-year structure signals. A two-year or three-year contract offers income certainty and negotiating leverage for superannuation optimisation over a longer runway. A one-year deal at 34 — however triumphant — is a clear message: this chapter closes in late 2027. For Gunston and any high-earning Australian who knows a career endpoint is fixed in time, that signal demands an immediate wealth management response.
What Wealth Advisors See in a One-Year Extension
A wealth advisor looking at Gunston's situation doesn't just see a football contract. They see a compressed window with three simultaneous pressures: peak taxable income, a mandated superannuation contribution ceiling, and a transition cliff on the other side.
The Division 293 reality. Under Australian tax law, high-income earners whose combined income and concessional super contributions exceed $250,000 pay an additional 15% tax on those contributions — a levy known as Division 293. On $650,000 in earnings, Gunston crosses that threshold by a wide margin. Every dollar contributed to super concessionally is taxed at 30% rather than the standard 15%, effectively halving the traditional super contribution advantage for someone in his bracket. Knowing this, a financial adviser would push hard on the question of where the money should go instead — or alongside — super.
The concessional cap squeeze. From 1 July 2026, Australia's concessional superannuation contributions cap rose to $32,500 per year, as confirmed by the Australian Taxation Office. For someone earning $650,000, the 12% employer Superannuation Guarantee contribution on the Maximum Superannuation Contribution Base ($270,380) already equals approximately $32,500 — consuming virtually the entire concessional cap before a single voluntary contribution is made. There is effectively no room for additional salary sacrifice on a pre-tax basis. That leaves non-concessional contributions (up to $120,000 per year) and investment structures outside super as the primary levers.
The transition cliff. Unlike an office worker who might reduce hours gradually or pivot to part-time, an AFL footballer goes from $650,000 one year to zero contracted income the next. The psychological and financial whiplash of that cliff is something wealth professionals who work with elite athletes identify as the most underestimated risk in sports finance. Building liquidity before the cliff — not after it — is the defining strategy.
For comparable thinking on how AFL players navigate contract structures alongside financial rights, the experience of emerging players managing shorter deals is explored in Nick Coffield's one-year Bulldogs deal and what AFL contracts mean for financial planning.
The Numbers: What a 34-Year-Old on $650K Should Model Right Now
Let's make this concrete. Suppose an Australian in a comparable position — a specialist professional aged 34, earning $650,000 per year, who knows their current income structure ends in roughly 18 months. What does sound wealth planning look like?
Scenario A — the set-and-forget trap. The professional does nothing special beyond standard payroll deductions. Their employer contributes $32,499 into super (maxing the concessional cap via SG). Division 293 applies, so the effective tax on those contributions is 30%, not 15%. Net super contribution benefit is modest. Outside super, their $650,000 income is taxed at the top marginal rate of 47% (including Medicare). After tax and living expenses, they accumulate some savings, but with no structure, much of the end-of-career liquidity is sitting in a high-interest bank account earning interest that is itself taxed at 47%.
Scenario B — with a wealth advisor engaged 18 months out. The same professional, with advice:
- Maximises non-concessional contributions into super: $120,000 per year in after-tax dollars, growing in a 15% concessional environment inside super rather than 47% outside. Over two years (2026 and 2027 seasons), that's $240,000 shifted into a significantly lower-tax structure.
- Reviews the bring-forward rule: by triggering the three-year bring-forward provision, they could potentially contribute up to $360,000 into super in a single year (subject to the total super balance cap of $1.9 million and advice confirmation). If their total balance allows it, this is an acceleration strategy for the transition period.
- Establishes a personal investment portfolio outside super to provide accessible liquidity in the first few years post-career — the crucial period before preserved super benefits can be drawn.
- Structures income protection and risk insurance to step down in line with the contract endpoint, avoiding paying premiums on coverage that will no longer be needed while simultaneously ensuring no gap in the transition window.
The difference between Scenario A and Scenario B is not a marginal one. Modelling by financial planning practices specialising in sports professionals typically shows a gap of $300,000 to $500,000 in net wealth over a ten-year horizon for athletes earning in this bracket who engage advice during the final contract versus those who engage it only after retiring.
If your own situation involves a known income endpoint — a fixed-term senior role, a business sale, a parental leave transition, or a contract that you know is your last at current earnings — the same logic applies. The 18-month window is not a comfort; it is a deadline.
What to Ask a Wealth Advisor Before the Season Ends
The Gunston extension prompts a useful checklist for any Australian entering a known final chapter of high earnings:
1. What is my Division 293 exposure this year, and can I reduce it? Division 293 is assessed after the financial year ends, and the ATO sends an assessment notice — it does not come off automatically. Knowing the figure in advance allows for planning rather than surprise.
2. Have I modelled the bring-forward rule against my total super balance? The eligibility rules changed in recent years. Do not assume you qualify — verify with advice.
3. What structure holds my non-super savings and how is income from it taxed? A family trust, a discretionary investment account, or a bucket company each have different tax profiles. The wrong structure costs real money on a $650,000 income base.
4. When does my income protection insurance need to be reviewed? Most policies are benchmarked to a percentage of current earnings. The policy written for a $650,000 income may have features that become irrelevant or expensive once career income ends.
5. Is my estate planning current? A major financial transition is one of the classic triggers for reviewing wills, beneficiary nominations on super, and power of attorney documents. These documents are often left static while circumstances change dramatically.
A wealth management expert who has worked with athletes or high-income professionals in career transition will address all five questions as a package, not in isolation. The interconnections between super structures, tax timing, insurance, and estate documents are precisely where self-directed planning most often fails.
This article is general information only and does not constitute personal financial advice. Superannuation and tax rules are subject to change. Consult a licensed financial adviser and tax professional before making decisions about your super contributions or investment strategy.
Connect with a verified wealth management expert on Expert Zoom to discuss financial planning for career transitions, superannuation optimisation, and post-career wealth structures.
