 Olivia Thompson
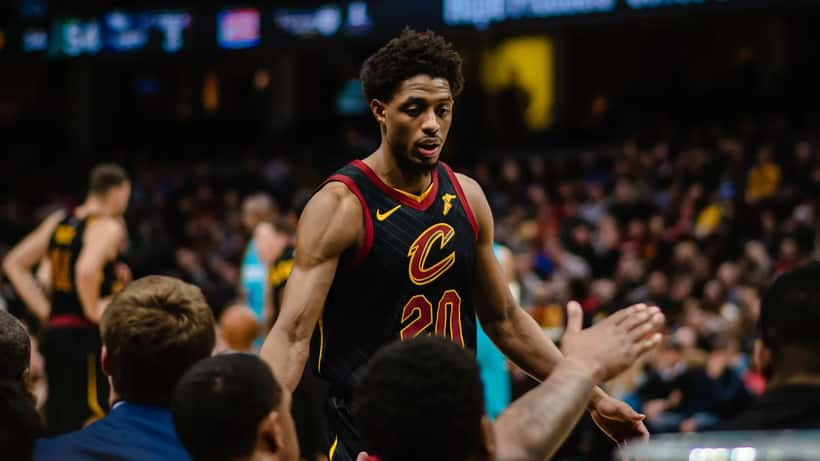
The Perth Wildcats have confirmed one of the NBL's most eye-catching overseas signings just days before the 2026-27 season tips off: Brandon Knight, a 34-year-old guard who accumulated over 450 appearances across nine NBA seasons, will play in Australia's premier basketball competition. Confirmed on 14 September 2026, the deal caps a remarkable career second act for a player whose NBA journey ran from Detroit to Phoenix — and it spotlights a financial and legal minefield that every high-earning athlete crossing borders should navigate carefully before they ink a contract.
Knight's Journey to the NBL
Brandon Knight entered the NBA in 2011 as a first-round pick, spending the bulk of his peak years with the Detroit Pistons and Phoenix Suns. His 2015-16 season with Phoenix remains his statistical high watermark: 19.6 points per game, cementing his status as a legitimate starting-calibre guard. Injuries, roster changes, and the brutal arithmetic of the modern NBA's youth movement gradually pushed him toward the fringes — stints with Milwaukee, Houston, Cleveland, Sacramento, and Dallas followed before his last NBA contract with the Mavericks in 2022.
After Dallas, Knight moved to Puerto Rico's Baloncesto Superior Nacional, suiting up for Mets de Guaynabo. It was a smart career extension move: competitive basketball, a warm climate, and a chance to stay sharp while the NBA door remained theoretically open. Now Perth has convinced him to trade the Caribbean for Western Australia. According to NBL.com.au, the Wildcats landed Knight as a marquee import ahead of a season where they are targeting a return to championship contention.
For basketball fans, the story is straightforward: an experienced NBA veteran brings scoring, playmaking, and composure to a league that punches above its weight globally. For anyone who advises professional athletes — or for athletes themselves planning a similar move — the story behind the story is about money, tax, and what happens when a US dollar career meets Australian law.
The Financial Architecture of an Overseas Sports Contract
When an American athlete signs in Australia, they step into a tax system that treats non-residents very differently from locals. Under Australian Taxation Office rules, a foreign resident playing in the NBL is subject to a flat 32.5 per cent tax rate on Australian-sourced income from the first dollar earned — there is no tax-free threshold. Contrast that with Australian residents, who pay zero per cent on the first $18,200 of annual income, then a tiered scale above that.
According to the Australian Taxation Office, foreign residents must also deal with withholding tax on investment income from Australian sources, and are generally excluded from Medicare levy obligations — but also from Medicare benefits. For an athlete earning a significant NBL salary, the tax math can be the difference between a financially sound decision and a costly one.
Add currency risk to the equation. NBL contracts are denominated in Australian dollars. As of September 2026, the AUD/USD exchange rate means that every $1,000 AUD earned translates to roughly $0.64 USD — a figure that fluctuates with commodity prices, interest rate differentials, and market sentiment. An athlete who signs a one-year deal and spends their savings in US dollars needs to plan around the possibility that the exchange rate deteriorates further during the season. Over a full contract, a 5 per cent swing in the AUD/USD rate can represent thousands of dollars of effective salary difference.
Then there is superannuation: Australia mandates that employers contribute 11.5 per cent of ordinary time earnings into a superannuation fund on behalf of their employees. For a foreign athlete on a short-term contract, accessing that money requires meeting a specific condition of release — generally departing Australia permanently and holding a temporary visa. Without proper structuring, that superannuation contribution can be stranded for years.
Concrete Case: One Season, Real Numbers
Consider a hypothetical based on mid-tier NBL import contracts. Suppose a 33-year-old US athlete signs a one-season NBL deal worth AUD 200,000 in base salary. Here is how the financial picture unfolds — and where an expert can make a material difference.
Tax on Australian income: As a non-resident, the athlete pays 32.5 per cent from dollar one. On AUD 200,000, that is AUD 65,000 in Australian income tax — leaving AUD 135,000 net before any other deductions.
Superannuation: The club contributes an additional AUD 23,000 (11.5% of $200,000) into a super fund. The athlete can claim this back via a Departing Australia Superannuation Payment (DASP) when they leave — but DASP itself is taxed at a withholding rate of 35 per cent. So of the AUD 23,000 contributed, the athlete recovers around AUD 14,950 on departure.
Currency conversion: If the AUD/USD rate is 0.64 when the athlete converts their net salary, AUD 135,000 becomes approximately USD 86,400. If the rate drops to 0.60 during the season — a realistic 6 per cent move — the same AUD sum converts to just USD 81,000 at year end. A difference of USD 5,400 purely from exchange rate drift.
If the athlete had engaged a wealth management expert before signing: they might have arranged a forward currency contract locking in the current exchange rate for a portion of their salary, reducing currency risk. They might have structured their contract to include deductible training and relocation expenses, reducing the taxable base. And they would have had a clear DASP exit strategy in place from day one, rather than leaving it to chance at season end.
The if/then logic is direct: if you sign without independent financial advice, then you absorb full tax at 32.5%, face currency drift with no hedge, and risk losing weeks of productive time at season end untangling the DASP process. If you engage a wealth management specialist before signing, then you can realistically add USD 8,000–15,000 in net value to the same contract through tax structuring, currency management, and exit planning.
Why This Matters Beyond the NBL
Brandon Knight's signing will draw attention because of his NBA pedigree — 450-plus games, a team that drafted him in the top 10, a peak season averaging nearly 20 points per game. But the financial questions his situation raises apply to any athlete, or indeed any high-earning professional, making an international career move.
Australia is one of the most attractive destinations for overseas professionals precisely because its economy is robust, its competition standards are high, and its lifestyle is genuinely compelling. The NBL is not an outlier — Australian professional sport regularly attracts talent from the NFL, MLB, European football, and international rugby. Each time a foreign professional lands in Australia, the same financial architecture applies.
The ATO does not make exceptions for celebrity. The superannuation system does not simplify itself because the player is a former NBA first-round pick. Currency risk does not care about a player's career statistics. The athletes who navigate these moves most successfully are the ones who treat the financial planning as seriously as they treat their pre-season conditioning.
What the Wildcats Signing Tells Us About the Modern Athlete Career
Knight's move to Perth is, viewed charitably, an illustration of elite-level adaptability. The modern professional athlete — particularly in basketball — now operates in a global marketplace where the NBL, EuroLeague, Liga ACB, and dozens of other competitions represent genuine career options, not just post-NBA consolation prizes.
That globalisation of professional sport creates real opportunity. It also creates real complexity. An athlete who played on a $3 million NBA contract for several years has likely accumulated savings, investments, and tax obligations across multiple US states. Adding an Australian income stream to that picture requires careful coordination between US-based advisors who understand international tax treaties (the US-Australia tax treaty provides some protections against double taxation, but only if structured correctly) and local Australian professionals who understand the specifics of superannuation, withholding, and visa-related financial considerations.
What to Do Before Signing an Overseas Sports Contract
For any athlete considering a move like Knight's — or for anyone in a high-income profession crossing borders — the checklist before signing is clear:
Engage a wealth management specialist with international experience. Not every financial advisor understands the interplay between Australian superannuation, foreign resident tax rates, and treaty-based relief. Find one who does.
Model the currency risk. Salary looks different depending on when you convert. A forward contract or staged conversion schedule can meaningfully protect your take-home pay.
Understand your DASP rights from day one. Know exactly when you will be eligible to claim your superannuation back, what rate it will be taxed at, and what documentation you will need to provide.
Check the US-Australia tax treaty. Double taxation is not automatically avoided. Your US accountant and your Australian advisor need to communicate about how your Australian income will be treated when you file your US return.
The Perth Wildcats and their fans will be watching Brandon Knight's on-court contributions. Anyone managing or advising athletes making global career moves should be watching the financial decisions just as closely.
This article is for informational purposes only and does not constitute financial or tax advice. Tax situations vary depending on individual circumstances, residency status, and applicable treaties. Consult a qualified wealth management expert or tax professional before making decisions based on this content.
format_used: News brief
